How Mobile Home Rent To Own Actually Works In Practice
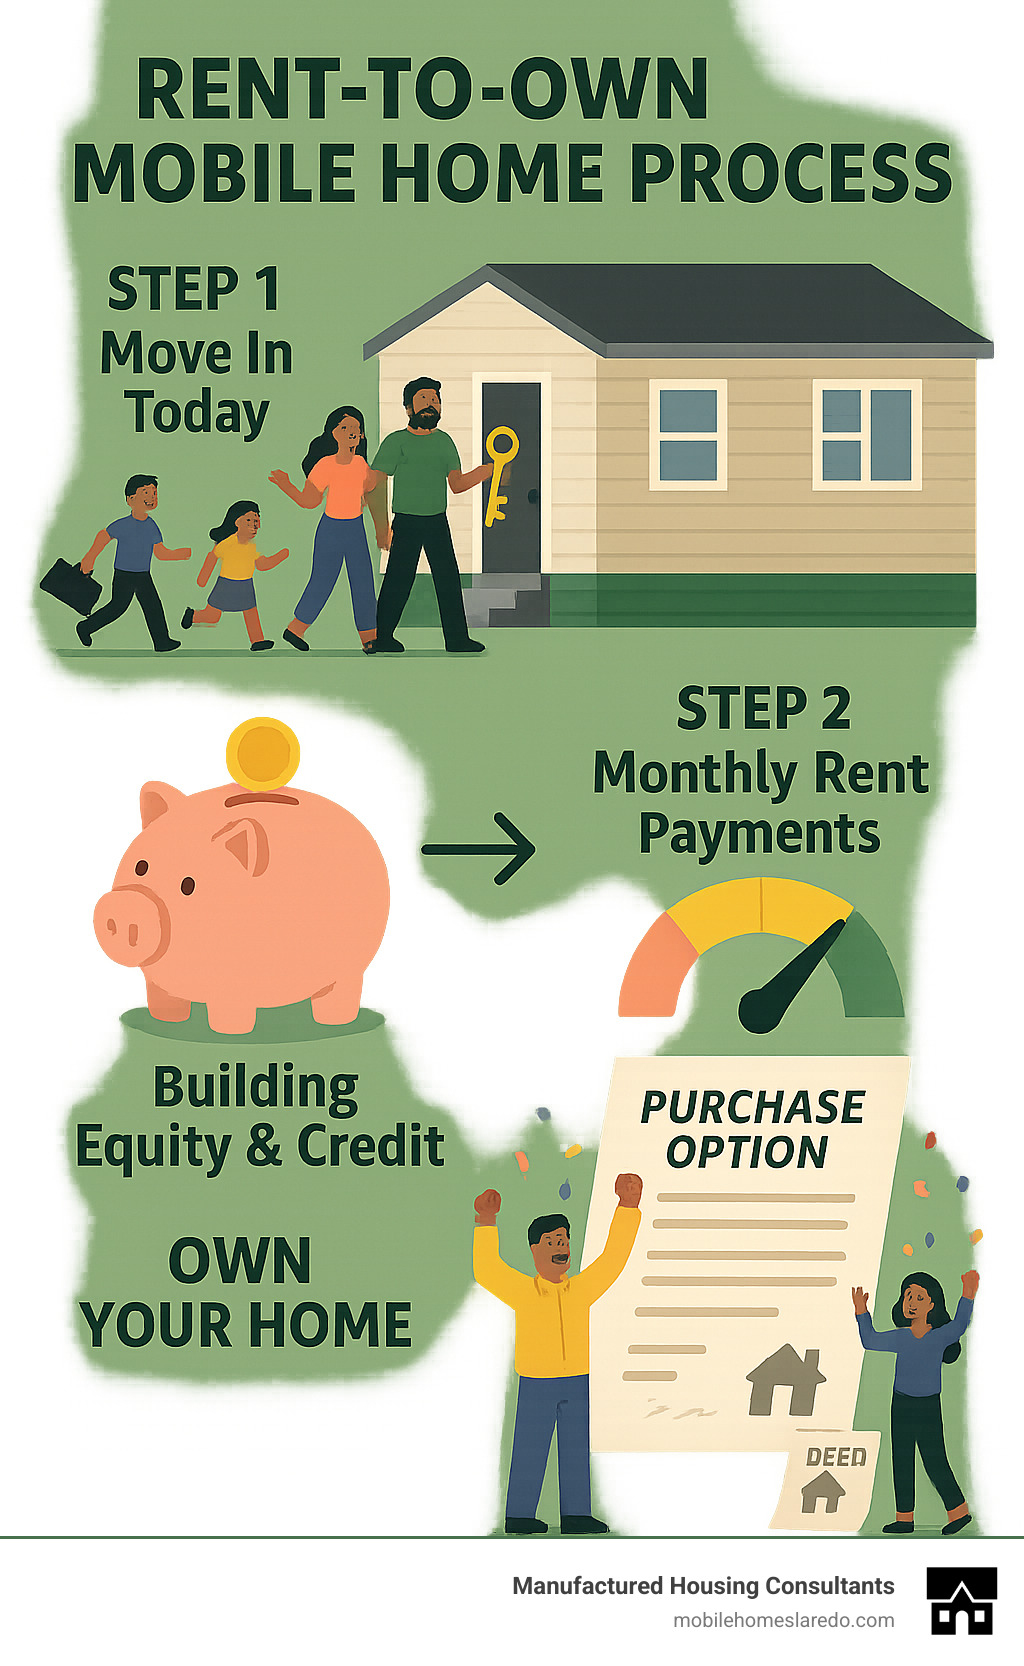
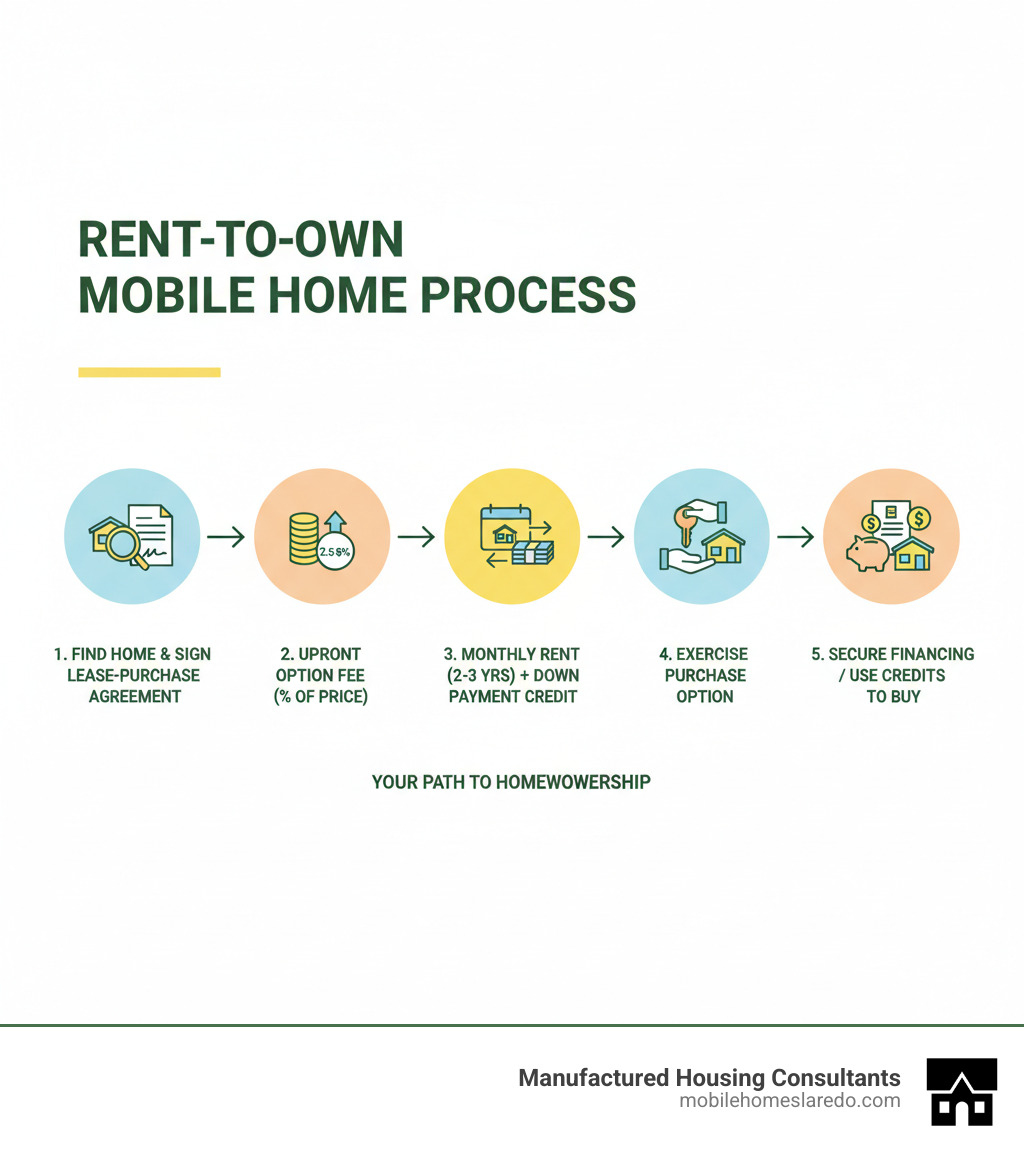
Rent-to-own on manufactured homes is one of those arrangements that sounds simple until you're sitting in a park office trying to figure out who owns what. I spent three years helping people navigate these contracts after my own attempt to buy a used double-wide through a seller-financed deal went sideways. The process works, but the pitfalls are specific enough that generic advice will get you burned. The basic mechanism is straightforward. A property owner — usually a private seller, sometimes a small portfolio holder — agrees to let you live in a mobile home for a set period while you pay an upfront option fee and a portion of your rent that gets credited toward the purchase price. At the end of the term, you either buy the home at a pre-agreed price or walk away and lose your credits. The pre-agreed price is typically locked in at signing, which matters when you're in a market where mobile home values are creeping up. Here's what most guides won't tell you: the biggest risk isn't whether you can qualify for financing at the end of the term. It's whether the contract is structured so that you actually have the right to buy. I had a client whose rent-to-own agreement said she could "purchase the unit at fair market value" at the end of 24 months. Fair market value at the time turned out to be $28,000 higher than what they originally wanted. She'd paid $14,000 in rent credits and had no leverage because the contract gave her an open-ended price mechanism instead of a fixed purchase price. We ended up renegotiating through a mid-contract amendment, but it cost her an extra month of rent and a lot of stress.
Unlock Affordable Homeownership The Lowdown On Mobile Homes Rent To Own
Before you sign anything, you need to understand the difference between a lease-option and a lease-purchase. A lease-option gives you the right but not the obligation to buy. A lease-purchase legally obligates you to buy, regardless of whether you've secured financing or your financial situation has changed. Most sellers push lease-purchase because it guarantees them a sale. For buyers, lease-option is almost always the safer play unless you're already pre-approved and confident about your trajectory. The option fee is your most important negotiating point. Standard practice runs between 1% and 5% of the agreed purchase price. On a $45,000 home, that's $450 to $2,250 upfront, non-refundable, but typically fully credited toward your purchase. Some sellers will let you roll this into your first month's payment. I've seen deals where the option fee was 10% or more — red flag territory. That usually means the seller knows the terms won't work out and they're banking on keeping your deposit. Land ownership changes everything. If you own both the home and the lot, you're dealing with real property and standard mortgage financing becomes available at reasonable rates. If you own the home but rent the lot in a manufactured home park, you're in chattel territory. Chattel loans carry higher interest rates — often 8% to 14% — and shorter terms, usually 10 to 15 years instead of the 15 to 30 you'd get on a traditional mortgage. The monthly payment on a $50,000 chattel loan at 11% over 12 years comes out to roughly $620 per month. Compare that to a traditional FHA loan on the same amount at 6.5% over 30 years, which would be about $316 per month. That gap is why lot ownership matters so much.
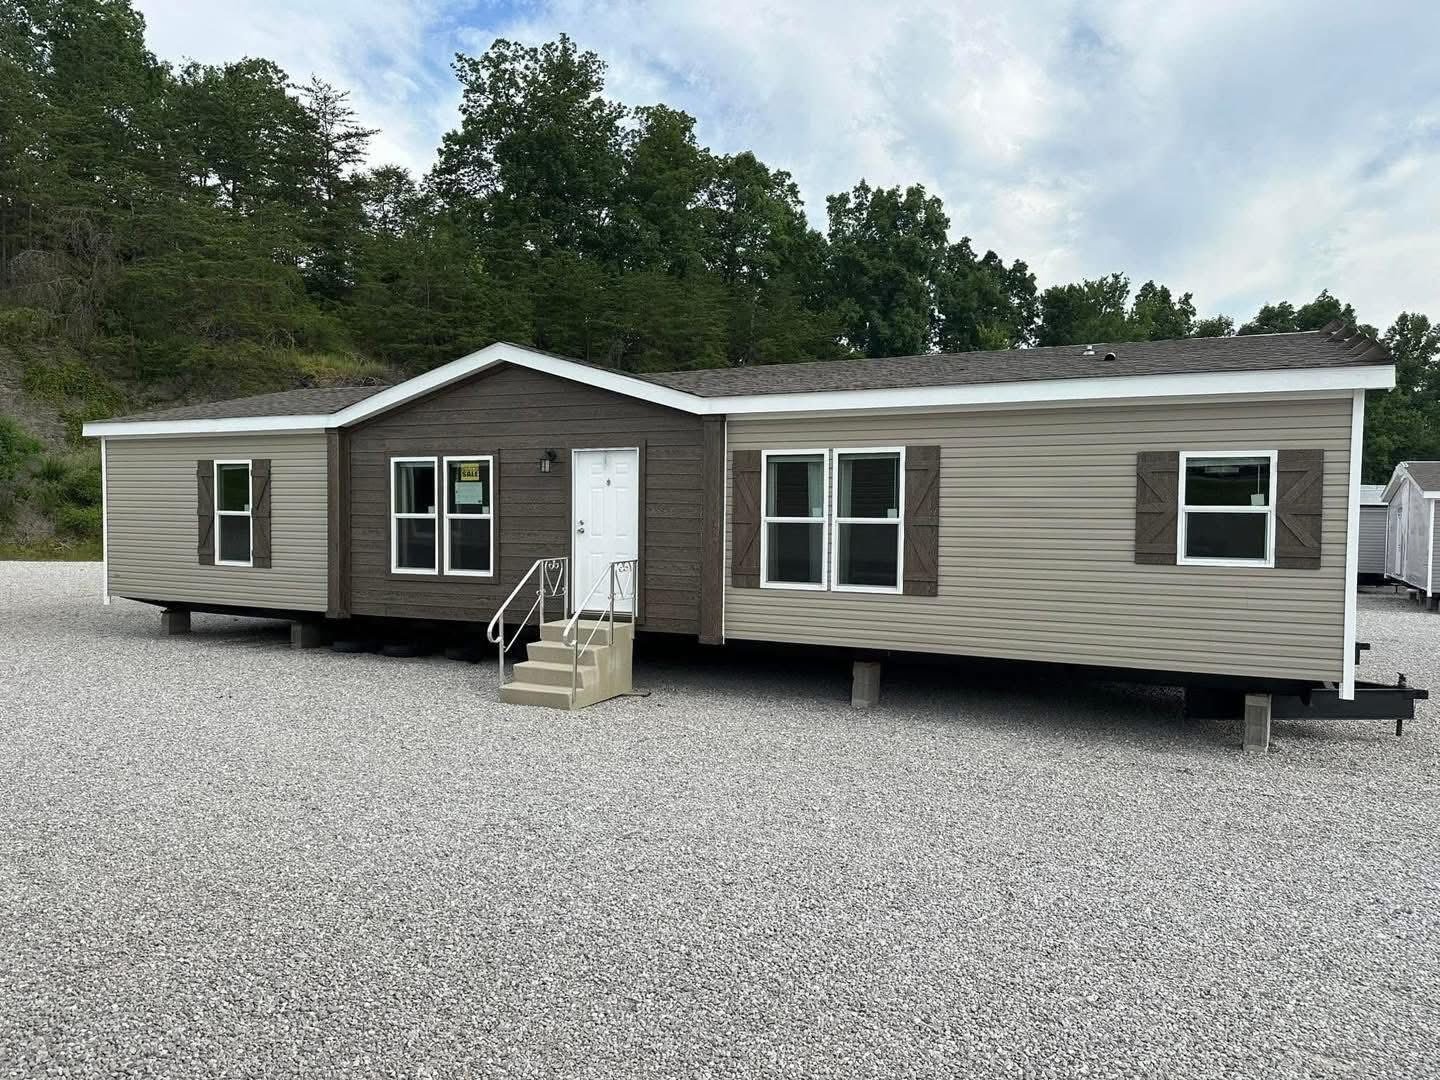
Here's a detail most people miss: the condition of the home when you enter the agreement directly affects your future financing. Lenders require manufactured homes to meet HUD standards and be classified as real property rather than personal property. That means permanent foundations, proper labeling, and compliance with local codes. If the home you're renting has structural issues, missing axles, or hasn't been properly titled, you could be stuck at the end of your term unable to convert the arrangement into a purchase because no lender will touch it. I once walked away from a deal where the home had been through two parks and neither had a permanent foundation. The seller wanted $38,000. The repairs needed to bring it up to code — new skirting, axle repair, possibly a undercarriage replacement — ran about $12,000 before you even started thinking about the lot. Nobody told me that until I brought in a mobile home inspector, which you should absolutely do before signing anything. Tenant screening in rent-to-own is typically lighter than traditional rentals. Sellers often prefer someone who needs a path to ownership over someone with perfect credit looking for a place to stay. This works in your favor when negotiating because there's less competition for the deal. But it also means the terms can be unusually generous or unusually predatory depending on the seller. Read every line. The credit rent provision — how much of your monthly payment goes toward the purchase price — is where sellers can hide unfavorable terms. Some structure it so that 80% of your rent goes to credits and only 20% covers actual occupancy. Others do the opposite, making the credits negligible while charging above-market rent. A typical fair split is 25% to 40% of your monthly payment going toward the purchase credit. Maintenance responsibility during the lease term is another area where contracts routinely favor sellers. In a standard residential lease, the landlord handles major repairs. In a rent-to-own agreement, sellers frequently shift roof, HVAC, and structural maintenance to the tenant. On a 15-year-old mobile home, the roof is likely nearing the end of its service life. If the contract says you're responsible for all maintenance, a single roof replacement at $8,000 to $15,000 can wipe out years of rent credits. Negotiate for shared responsibility or a cap on your annual maintenance obligations.
Get the Full Details
If you're serious about this path, get the contract reviewed by a real estate attorney who understands manufactured housing. The cost is usually $300 to $600 and it will catch clauses that would cost you tens of thousands later. You should also pull the title history on the home before signing. Some sellers have homes with open liens or unclear ownership that surface only during the closing process. I've seen at least four cases where the rent-to-own buyer had no idea the seller wasn't the legal owner until they tried to close. The home was owned by a trust or a former owner who died, and the buyer lost everything they'd paid in credits and deposits over 18 months. The timing of when you enter these agreements matters too. Mobile home values tend to lag behind site-built home appreciation, which means you can lock in a purchase price now that might look reasonable two years from now even if the market shifts. But manufactured homes depreciate faster than traditional houses once they're more than five years old. A 20-year-old double-wide on a rented lot may actually lose value over the course of your rent-to-own term, which means you could end up owing more than the home is worth when you try to refinance at the end. That underwater position is real and it happens more often than people expect. Documentation you should request before signing: the current title or certificate of origin, any lien disclosures, the most recent park rules if you'll be in a community, and a written breakdown of exactly how rent credits accumulate. Verbal promises about credits don't hold up in court. Get it in writing with specific dollar amounts and dates.
If the seller won't provide a detailed written breakdown of the credit structure, walk away. That alone tells you more about how honest the deal will be than any contract clause you could read.