IRA Accounts Are Not Complicated, But the People Selling Them Will Make Them Seem That Way
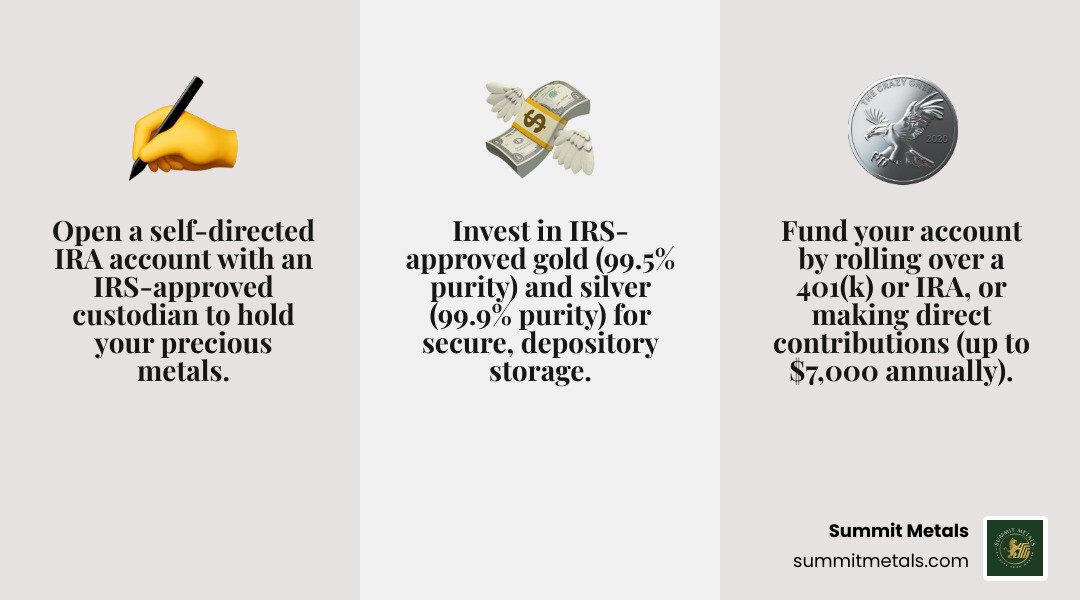
The actual mechanics of opening and managing an IRA are straightforward. You pick a type, you fund it, you pick investments inside it, and you wait. The friction comes from the sheer number of providers, the subtle differences in fees, and the way most financial websites describe these accounts as if they're solving some existential crisis. They aren't. They're just tax-advantaged savings containers with specific rules you need to know before you put money in. Most people open an IRA through a brokerage like Fidelity, Vanguard, or Charles Schwab. You go online, fill out a form with your Social Security number, link a bank account, and decide how much to contribute for the year. That's it. The contributions deadline for most years is April 15th of the following calendar year, so if you're reading this in late January and haven't funded your IRA yet, you still have time. The 2025 contribution limit is $7,000 if you're under fifty, or $8,000 if you're fifty or older due to the catch-up provision. Those numbers adjust for inflation periodically, so check the current year's limits before you transfer anything. The real question isn't whether you can open one, it's what kind you should open. A traditional IRA gives you a potential upfront tax deduction depending on your income and whether you or your spouse has a retirement plan at work. A Roth IRA gives you tax-free withdrawals in retirement instead. The choice between them depends almost entirely on whether you expect to be in a higher tax bracket later than you are now. If you're making decent money now and your income puts you above the Roth eligibility thresholds, a traditional IRA might be the only option you have. The 2025 phase-out ranges for Roth contributions start at $146,000 for single filers and $230,000 for married filing jointly. You can always do a backdoor Roth if you're income-limited, but that's a separate process I'll get to.
I opened my first IRA in 2009 at a large brokerage because my employer's 401(k) plan was terrible, and the fees were eating about two percent of my returns annually. I moved the account to Vanguard five years later after realizing I was paying roughly $75 a year in administrative fees I didn't understand. The switch took about twenty minutes. You log into your old brokerage, initiate a direct trustee-to-trustee transfer, and provide the receiving institution's account details. No check touches your hand. No tax event occurs. The money just moves.
What Nobody Tells You About Investment Selection Inside an IRA
The account type matters less than what you actually buy inside it. Putting individual stocks in an IRA feels productive but it's usually a mistake for most people. The tax advantages of an IRA are wasted if you're trading frequently and generating short-term capital gains that would have been taxed the same way inside a taxable account anyway. The smart move is low-cost index funds or ETFs. VTI, VXUS, BND, those kinds of things. You set it up, you automate contributions, and you don't touch it for decades. Here's the counter-intuitive part that most beginners miss: putting bonds inside an IRA and equities in your taxable account can be more tax-efficient than the reverse. Bonds generate ordinary interest income that gets taxed at your highest marginal rate every year in a taxable account. Inside an IRA, that interest grows tax-deferred. Equities in a taxable account benefit from the lower long-term capital gains rates and the ability to harvest losses. This asset location strategy isn't obvious from any IRA comparison chart you'll find online, but it can save you meaningful money over time, especially in higher tax brackets. I learned this the hard way around 2014. I had everything in stocks across every account type because I was chasing growth and didn't understand the tax implications of bond interest in a taxable bucket. By 2016, I was paying about four thousand dollars a year in unnecessary taxes on bond coupons that could have been sheltered. I restructured gradually over a couple of years, moving bond funds into my IRA and keeping equities in my taxable accounts. The annual tax bill dropped to roughly eight hundred dollars, and I didn't have to change my overall asset allocation at all.
Get the Full Details
Unlock A Secure Future Your Comprehensive Guide To Ira Savings Accounts
If you're looking for a structured approach to IRA savings, the core principles are simple enough that you probably don't need a twenty-page guide. Contribute consistently. Keep costs low. Choose appropriate investments for your timeline. Rebalance when allocations drift more than five percentage points from your target. Review your account annually, not daily. The people who make the most money from IRA education are the ones selling you courses, books, or subscription services that tell you something you can find in three pages on the IRS website. The one situation where a comprehensive guide actually helps is when you're dealing with a rollover from an employer plan. Converting a 401(k) or 403(b) into an IRA involves paperwork, potential tax withholding complications, and deadlines you can miss if you're not careful. A direct rollover avoids the sixty-day rule and the mandatory twenty percent withholding that applies to indirect rollovers. If your former employer's plan administrator sends you a check made payable to you instead of directly to the IRA custodian, you have exactly sixty days to deposit the full amount including any withheld taxes into a new IRA or you trigger a distribution event. That means taxes, penalties if you're under fifty-nine and a half, and a significant dent in your retirement savings. I've seen people lose twelve thousand dollars to this exact mistake because they didn't understand the difference between direct and indirect rollovers. Another edge case that catches people off guard is the interaction between IRA contributions and the Saver's Credit. The credit is non-refundable and scales with income, ranging from ten to fifty percent of your first two thousand dollars in qualified contributions. If you're eligible, contributing the maximum to a Roth IRA can reduce your tax liability by up to one thousand dollars. But the income limits are tight. For 2025, single filers phase out completely at $81,000 of modified adjusted gross income. Married filing jointly phases out at $162,000. Most people who could benefit from this credit don't know it exists because financial institutions rarely advertise it.
The Downsides and When an IRA Is the Wrong Tool
IRAs have limitations that matter. You can't access traditional IRA funds before age fifty-nine and a half without paying a ten percent early withdrawal penalty on top of ordinary income tax. Roth IRAs are more flexible since contributions (not earnings) can be withdrawn anytime without penalty, but the five-year rule still applies to earnings if you want tax-free withdrawal. There's also the required minimum distribution rule starting at age seventy-three for most people under the SECURE 2.0 Act changes, which means you can't use a traditional IRA as a pure perpetuity strategy to pass wealth tax-free to heirs. For high earners whose income exceeds the Roth contribution limits, the backdoor Roth conversion is a viable workaround but it gets more complicated if you have existing pre-tax IRA balances due to the pro-rata rule. The pro-rata rule forces you to calculate the taxable portion of your conversion based on the total balance of all your traditional, SEP, and SIMPLE IRAs, not just the amount you're converting. I had a client in 2022 who tried to backdoor Roth without accounting for her old rollover IRA from a previous employer. She ended up owing taxes on roughly sixty percent of her conversion instead of nearly zero, and she didn't understand why until we ran the numbers together. The fix was a series partial rollover to a 401(k) plan that accepted rollovers before doing the conversion, which reduced her pre-tax IRA balance and minimized the pro-rata impact. If your primary goal is tax diversification rather than aggressive growth, a Health Savings Account paired with an IRA might serve you better. HSAs offer triple tax advantages that IRAs can't match: contributions are deductible, growth is tax-free, and withdrawals for qualified medical expenses are tax-free. After age sixty-five, you can withdraw for any purpose with just ordinary income tax, making it functionally similar to a traditional IRA for non-medical spending. The 2025 contribution limits are four thousand three hundred fifty dollars for individual coverage and eight thousand seven hundred fifty dollars for family coverage, plus a one thousand dollar catch-up if you're fifty or older.
The biggest practical mistake people make with IRAs is treating them like checking accounts. They're not. Every trade, every rebalance, every decision to move money out during a market downturn compounds against you in ways that are hard to quantify but easy to feel in your portfolio statements. The accounts that performed best over my twenty-plus years of managing retirement savings weren't the ones with the clever strategies or the frequent adjustments. They were the ones where I set up automatic contributions, picked broad index funds, and checked in once a year to rebalance. Everything else is noise. There's no application form or download link for IRA savings because the concept isn't a product. It's a regulatory framework you use by opening an account at any major brokerage or financial institution. What matters is the behavior around the account, not the account itself. Open one if you haven't. Fund it consistently. Keep costs down. Don't overthink the timing. The market will go through downturns and you'll feel compelled to do something about it. Don't. That's the actual guide.