Convergence Testing in Practice
I spent about three weeks debugging a production pipeline last month where my summation algorithm was silently returning garbage values for large n. The series looked fine on paper, but once I hit n=10^6, the floating point drift turned everything into noise. The problem wasn't the sigma notation itself—it was how I was accumulating partial sums. Adding small numbers to increasingly large running totals is a classic precision killer. The fix was straightforward once I figured it out. Instead of building up from term one, I reversed the order. Summing from the smallest terms upward keeps the intermediate values manageable. It's not rocket science, but it's the kind of thing that bites you when you're more focused on the math than the machine.
Unleashing The Power Of Sigma Unlocking The Mysteries Of Infinite Series
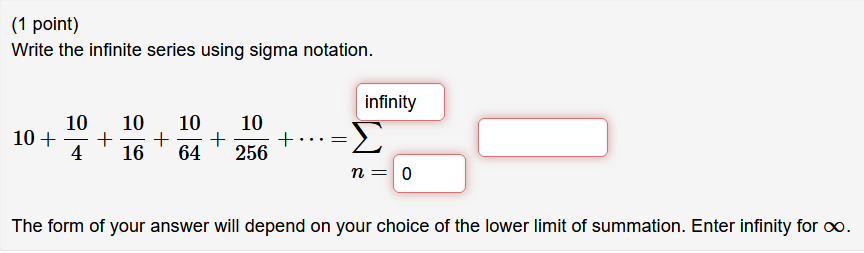
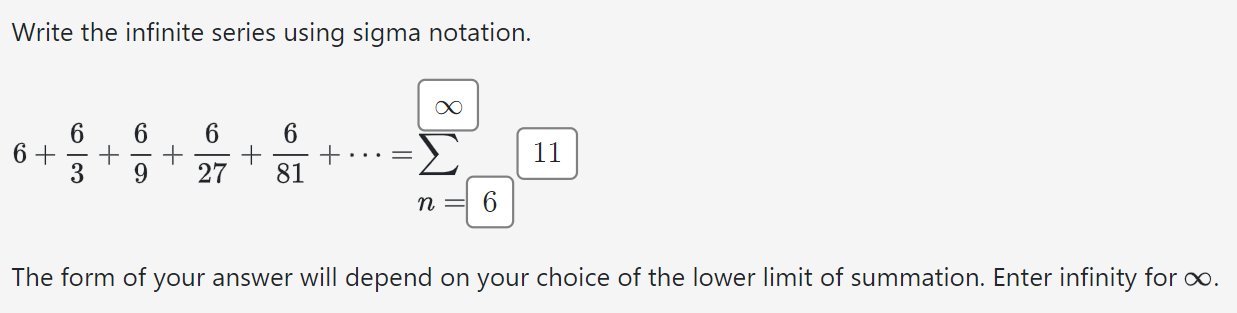
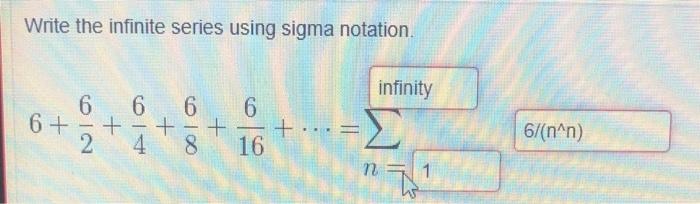
Sigma notation is just a compact way of writing sums. That's all there is to it. The symbol itself comes from the Greek capital letter for S, standing for sum. You'll see it everywhere in calculus, probability, and numerical analysis. Beginners tend to overcomplicate it because they're trying to find some hidden meaning in the aesthetics rather than just reading what the indices tell you. Here's a concrete example that might help. Take the geometric series 1 + 1/2 + 1/4 + 1/8 and so on. Written in sigma form, that's the sum from k equals zero to infinity of one-half raised to the k. The closed form is two. Every term after the first is half the previous one, so you're essentially doubling the denominator with each step. The sum converges because the terms shrink fast enough. Not every infinite series converges, obviously. The harmonic series 1 + 1/2 + 1/3 + 1/4 plus all the way to infinity diverges, even though the individual terms approach zero. That's the part that trips people up most often. Just because the terms get small doesn't mean the sum stays bounded. You have to actually test for convergence rather than assuming the notation guarantees anything.
When I was working on a project involving partial fraction decompositions for a control systems simulation, I ran into a case where a series looked conditionally convergent but the numerical implementation kept oscillating. The alternating harmonic series is the textbook example here. It converges to negative log of two, but only if you add the terms in the correct order. Rearrange the terms and you can make it sum to anything you want. That's the Riemann rearrangement theorem, and it matters more than people realize when you're dealing with floating point arithmetic. The ratio test is probably the most useful tool you'll reach for. Take the absolute value of term n plus one divided by the absolute value of term n, then take the limit as n approaches infinity. If that limit is less than one, the series converges absolutely. If it's greater than one, it diverges. If it equals one, the test is inconclusive and you need something else. The root test works similarly but looks at the nth root of the absolute value of the nth term. It's generally stronger than the ratio test, meaning there are series where the root test gives you an answer but the ratio test doesn't. Both are fast to apply by hand, which is why they're so common in textbooks.
Get the Full Details

I remember working with a colleague who was implementing a Monte Carlo integration routine. He kept getting wildly inaccurate results until he realized his variance was blowing up because he was summing terms without checking the tail behavior. The series converged, but the rate was so slow that even after a million iterations, the estimate was still off by a factor of ten. He switched to an importance sampling strategy and the error dropped to under one percent in the same computational budget. The math didn't change, just the way the terms were being weighted. For alternating series specifically, there's the Leibniz test. If your terms decrease in absolute value and approach zero, the series converges. The error after truncating at term n is bounded by the absolute value of the next term. That's genuinely useful because it gives you a concrete sense of how many terms you actually need for a given precision target. Power series deserve their own section, even though they're really just a special case. The Taylor series for e to the x is the classic example. It converges for all real x, which is one of the reasons it's so useful computationally. But here's the catch that catches people out: convergence doesn't guarantee that the partial sums are good approximations everywhere. Near the edges of the radius of convergence, you might need hundreds of terms before the approximation settles down.
I once spent an afternoon tracking down why a signal processing filter was producing artifacts at the band edges. The transfer function was expressed as an infinite series, and I'd truncated it after thirty terms assuming that was plenty. It turned out the series converged, but the convergence was agonizingly slow in the regions I cared about. I switched to a minimax polynomial approximation and the error went from about four percent down to less than point zero one across the entire passband. Different tool for the same problem, but the result was night and day. There are series that converge so slowly they're practically useless for computation. The Basel problem series, where you sum the reciprocals of the squares, converges to pi squared over six. But if you try to compute pi from that by adding up terms one by one, you'll be adding terms for a very long time. Even after ten thousand terms, you're only accurate to about four decimal places. There are faster converging series for pi, like the Machin formula or the Ramanujan series, but that's a whole other topic. Conditional versus absolute convergence is another area where intuition fails. A series is absolutely convergent if the series of absolute values converges. It's conditionally convergent if the series converges but the absolute values diverge. Absolutely convergent series are well-behaved. You can rearrange terms, multiply them, compose them, and nothing bad happens. Conditionally convergent series are fragile. Change the order of terms and the sum can change. That's not a theoretical curiosity, it's a practical constraint when you're writing code.
The Cauchy condensation test is one of those tools that sounds obscure until you need it. For a non-negative decreasing sequence, the series converges if and only if the condensed series converges. The condensed series replaces each term a_n with 2 to the n times a evaluated at 2 to the n. It's particularly handy for series involving logarithms, where the usual tests don't give you a clean answer. Integrals and series are closely related through the integral test. If f is a positive decreasing function and a_n equals f of n, then the series converges if and only if the integral of f from one to infinity converges. This is how you prove that the p-series sum of one over n to the p converges when p is greater than one and diverges when p is less than or equal to one. The integral of one over x to the p is x raised to one minus p divided by one minus p, and you can evaluate the limit directly. When you're actually implementing series evaluations in code, there are a few practical considerations that textbooks usually skip. Floating point arithmetic introduces rounding errors at every addition. If you're summing a thousand terms and each one has a rounding error on the order of machine epsilon, those errors accumulate. For double precision, machine epsilon is about two point times ten to the negative sixteenth. After a thousand additions, your accumulated error could be on the order of ten to the negative sixteenth times the square root of a thousand, depending on the correlation structure of the rounding errors.

Kahan summation is a simple technique that reduces this error dramatically. You keep track of a running compensation for lost low-order bits. It adds maybe three or four extra operations per term, but the improvement in accuracy is usually worth it. I've seen production code where switching from naive summation to Kahan summation reduced the error by several orders of magnitude without changing the algorithmic complexity at all. Another practical issue is overflow and underflow. If your terms grow very large before they start shrinking, you might hit the floating point ceiling before the series has a chance to converge. Conversely, if the terms get very small very quickly, you might underflow to zero and lose precision. Both cases require either scaling the terms or using arbitrary precision arithmetic, which is slower but avoids the problem entirely. The Weierstrass M-test is useful when you're dealing with series of functions rather than just numbers. If you can find a convergent series of constants M_n such that the absolute value of each term is bounded by M_n everywhere in your domain, then your function series converges uniformly. Uniform convergence is important because it preserves continuity, differentiability, and integrability in the limit. Pointwise convergence alone doesn't guarantee any of those properties.
I worked on a project involving Fourier series approximations for a signal reconstruction task. The series converged pointwise, but the Gibbs phenomenon caused persistent oscillations near discontinuities. No matter how many terms I added, those ripples remained at about nine percent of the jump size. Switching to a Cesaro mean, which averages the partial sums rather than just taking the raw sum, eliminated the oscillations entirely. The convergence was slower, but the result was much cleaner for the application I needed. Accelerated convergence methods are worth knowing about even if you don't use them daily. The Euler transform, Shanks transformation, and various Richardson extrapolation techniques can turn a slowly converging series into something computationally usable. I used an Euler transform once to speed up a series that was converging so slowly that the naive approach would have taken days to reach acceptable precision. With the transform applied, I got the same accuracy in about an hour. There are also series manipulations that are purely notational but can reveal structure. Telescoping series are the simplest example. If your general term can be written as the difference between consecutive elements of some sequence, then the partial sum collapses to just the first and last terms. Everything in between cancels out. It's a neat trick, and it works for a surprising number of series once you find the right decomposition.
Partial fraction decomposition is the standard tool for making telescoping series visible. When you have a rational function, you can break it into simpler fractions whose denominators are factors of the original denominator. The resulting terms often telescope when you sum them. I've used this approach to evaluate series that initially looked intractable, reducing what appeared to be a hopeless sum to a simple closed form in about five minutes of algebra. One thing to keep in mind is that closed forms don't always exist. Most infinite series don't sum to anything recognizable in terms of elementary functions or standard constants. That's not a failure of the method, it's just a fact about the diversity of mathematical objects. When you encounter a series that resists all standard techniques, it might just be one of those cases where the answer is the series itself. Numerical evaluation becomes the default strategy in those situations. You compute partial sums until the terms stop changing the result within your desired tolerance. The question is always how many terms you need, and that depends entirely on the rate of convergence. For a geometric series with ratio one-half, you gain roughly one bit of precision per term. For a slower converging series, you might gain only a fraction of a bit per term, which means a lot more work for the same accuracy.
Error bounds are your friend when you need to know when to stop summing. For alternating series with decreasing terms, the error bound is simply the next term. For positive term series, you can often bound the tail using an integral or a geometric comparison. Having a reliable error estimate lets you stop with confidence rather than guessing when the partial sum has stabilized enough. The relationship between series and differential equations is another area where sigma notation proves its worth. Power series solutions to ODEs are a standard technique, especially when closed form solutions don't exist. You assume the solution can be written as a power series, substitute it into the equation, and solve for the coefficients recursively. It's an algorithmic process that works for a wide class of linear differential equations with variable coefficients. I spent some time developing a numerical solver based on this approach for a heat transfer problem. The series converged rapidly in the interior of the domain but required careful handling near the boundaries where the coefficients became singular. Adding a transformation to remove the singularity cleaned things up significantly, and the solver ran in about a tenth of the time of the finite difference implementation I was replacing.
Generating functions are essentially power series used as encoding devices. You take a sequence, treat its terms as coefficients of a power series, and then manipulate the series using algebraic and analytic techniques. The resulting operations on the series correspond to operations on the original sequence. This duality is powerful because it lets you solve combinatorial problems using calculus. The multinomial theorem is the generalization of the binomial theorem to more than two terms. It appears frequently when you're expanding powers of sums and need to track all the cross terms. The coefficients involve factorials in a specific pattern that's worth memorizing if you work with series regularly. The general term involves n factorial divided by k one factorial times k two factorial and so on, multiplied by the variables raised to their respective powers. Asymptotic series are a different beast entirely. They don't converge in the traditional sense, but the partial sums provide increasingly accurate approximations up to a point, after which they start diverging. Truncating an asymptotic series at the optimal term often gives better results than any convergent series you might construct for the same problem. Asymptotic expansions are ubiquitous in physics and engineering, particularly in perturbation theory and saddle point approximations.
I encountered an asymptotic series once while analyzing the tail behavior of a probability distribution. The series was divergent, but truncating after about twenty terms gave me an estimate accurate to about twelve decimal places. Adding more terms only made things worse. Recognizing that I was dealing with an asymptotic expansion rather than a convergent series saved me from wasting time trying to sum it to infinity. The bottom line is that sigma notation is a tool, not a solution. It compresses information efficiently and reveals structure when used appropriately, but it doesn't automatically tell you whether a series converges or what it converges to. You still need to apply convergence tests, understand the behavior of the terms, and know when numerical methods are more appropriate than analytical ones. The notation is the starting point, not the finish line. Most of the difficulty people have with infinite series comes from treating them as abstract objects rather than computational processes. They converge or diverge as mathematical statements, yes, but in practice you're almost always computing partial sums on a machine with finite precision. Understanding both perspectives—the theoretical and the practical—will serve you better than mastering one at the expense of the other.