Numerical Integration With Simpson's Rule
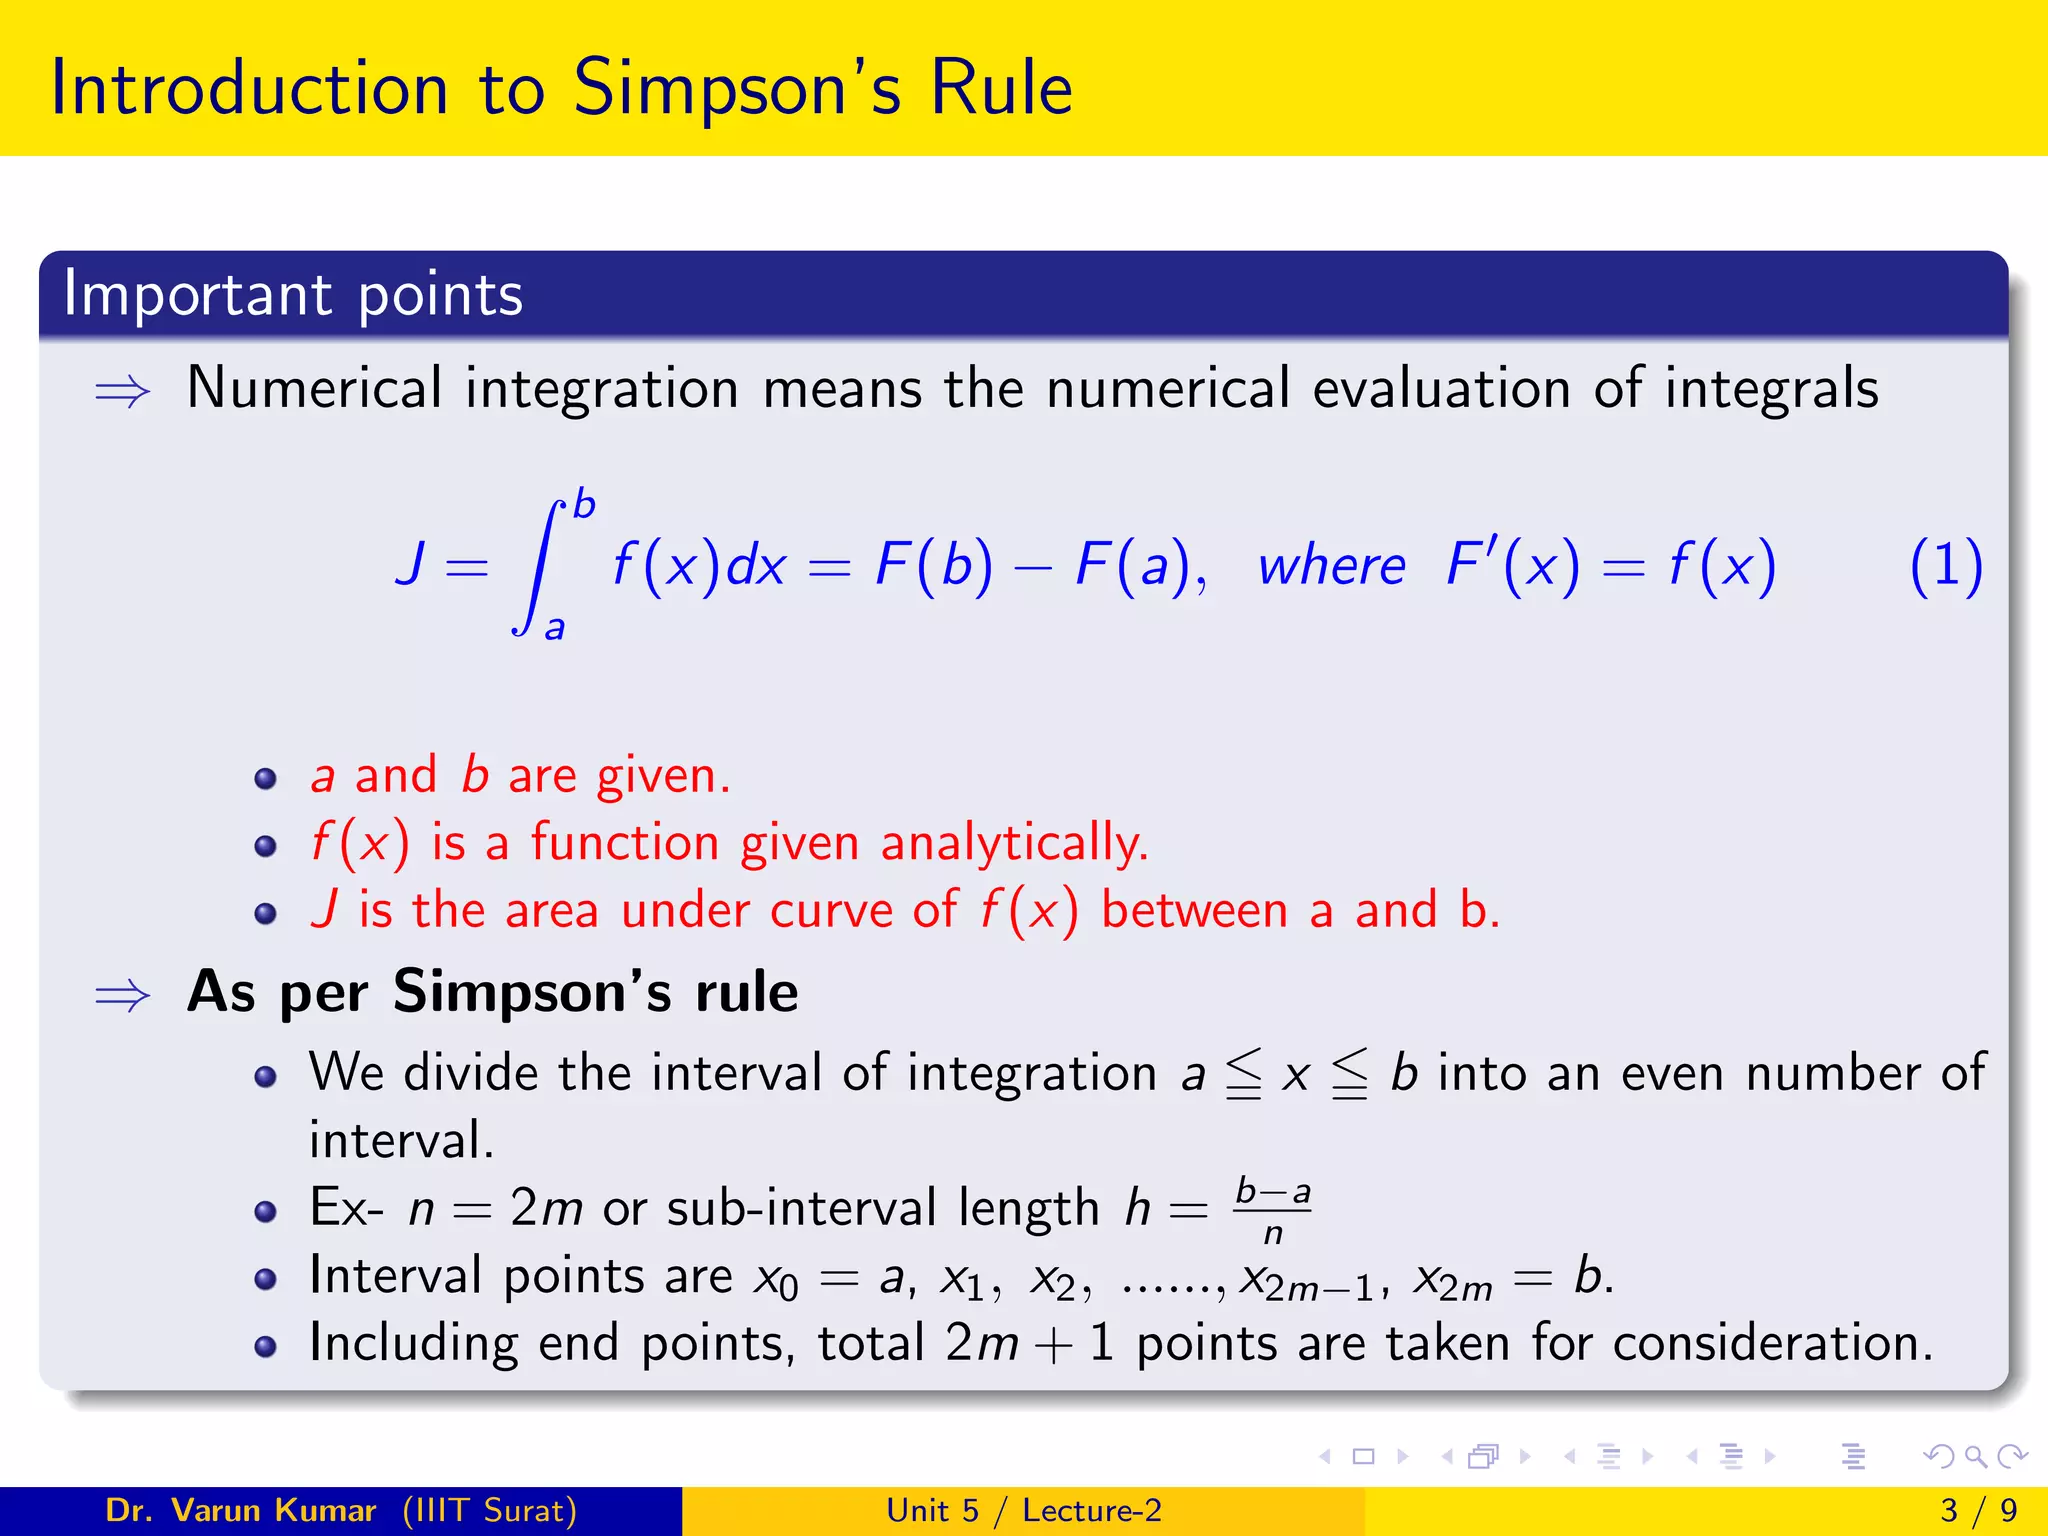
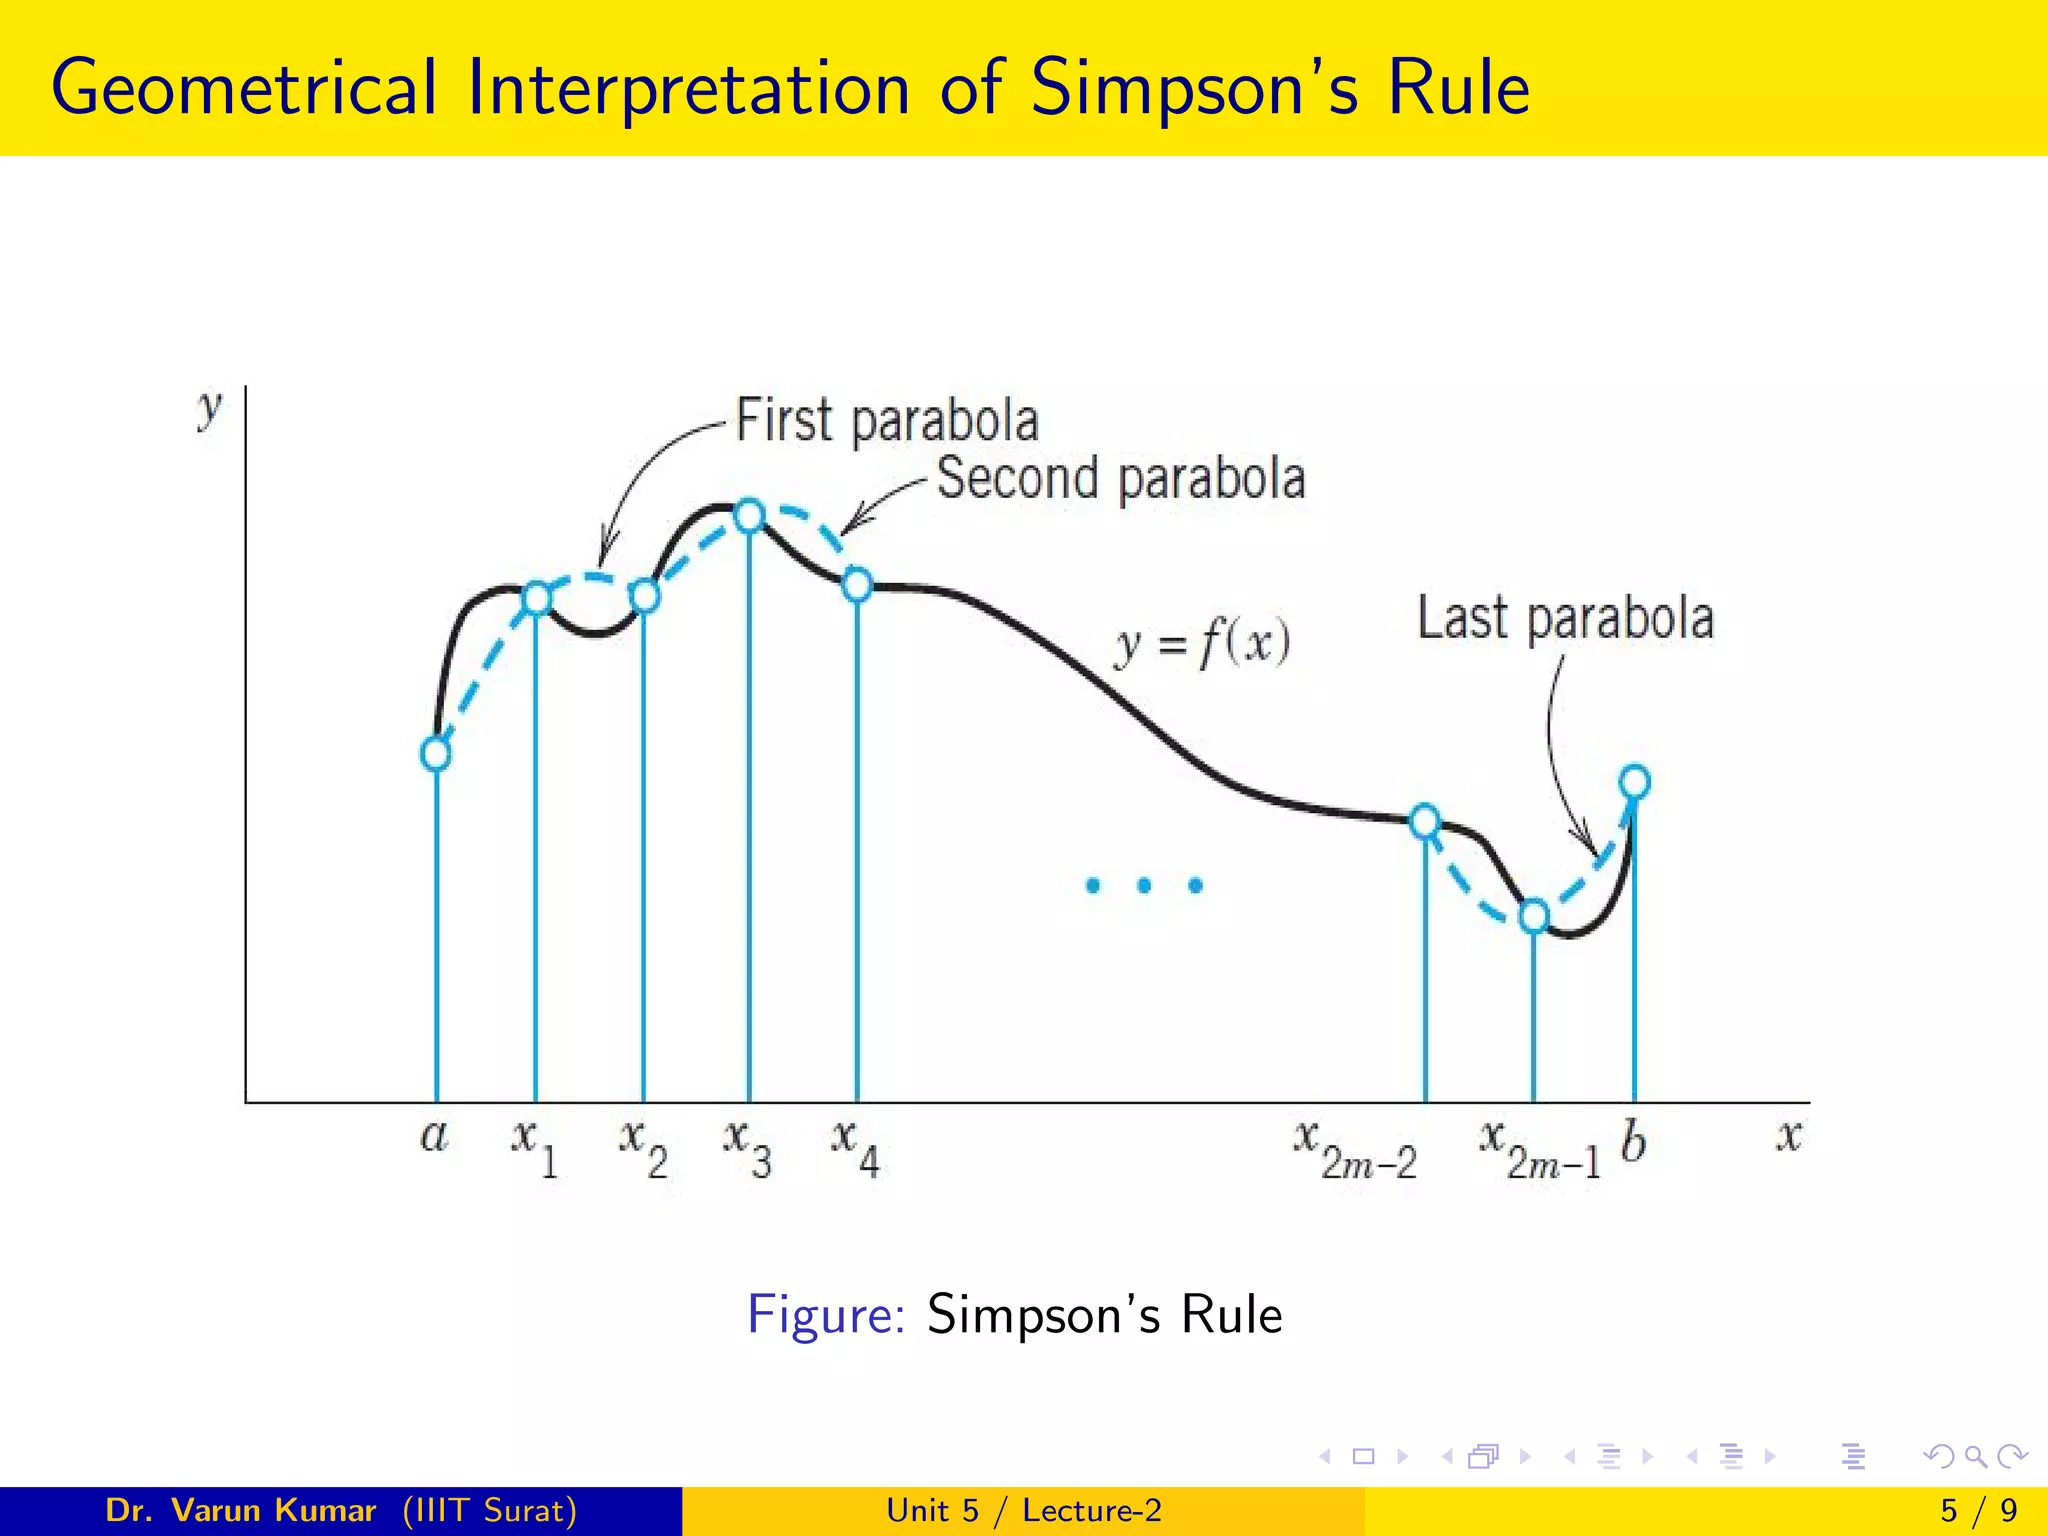
Simpson's Rule is a method for approximating definite integrals when you can't or don't want to find an analytical antiderivative. It works by fitting parabolas through successive groups of three points on the curve and summing the areas under those parabolas. The formula itself is straightforward: given a function f(x) evaluated at evenly spaced points x, x, ..., x over the interval [a, b] with step size h = (b-a)/n, the approximation is (h/3)[f(x) + 4f(x) + 2f(x) + 4f(x) + ... + 4f(x) + f(x)]. The pattern of coefficients alternates between 4 and 2 after the first term, and the final coefficient is always 1. I remember working on a heat transfer simulation a few years back where I needed to integrate a temperature profile across a irregularly shaped fin. The profile wasn't a clean function — it came from measured data points at irregular intervals along the fin's length. I initially tried trapezoidal integration because it was simpler to code quickly, but the results were off by about 12% compared to a high-precision reference solution. Switching to Simpson's 1/3 Rule brought the error down to under 0.3%. The difference was not subtle. It mattered for the design margins.
Unleashing The Power Of Numerical Integration With Simpsons Rule
The key advantage of Simpson's Rule over the trapezoidal rule is its order of accuracy. Trapezoidal integration has an error term proportional to h², meaning you need to halve your step size four times over to gain one extra digit of precision. Simpson's Rule has an error term proportional to h, so halving the step size improves accuracy by roughly a factor of sixteen. For smooth functions, this means you get far more accurate results with significantly fewer evaluation points. If you're integrating a well-behaved function over a moderate interval, Simpson's Rule with just 10 subintervals can match what the trapezoidal rule might need 80 or 100 subintervals to approach. There is a catch that most tutorials gloss over. Simpson's Rule requires an even number of subintervals, which means n must be even. If your data points are odd-numbered, you have to decide whether to drop the last point, pad with an extrapolated point, or switch to Simpson's 3/8 Rule for the final segment. I learned this the hard way when I was automating a batch processing script and kept getting index out of bounds errors at midnight because I wasn't checking parity before calling the routine. The fix was simple — add a conditional that checks if n is odd, applies the 3/8 Rule to the last three points, and uses the 1/3 Rule for the rest — but it took me longer than it should have to realize that was the problem in the first place. Another thing people miss is that Simpson's Rule assumes the function is smooth enough for a quadratic approximation to be meaningful over each pair of subintervals. If your integrand has discontinuities, sharp corners, or rapid oscillations, the method breaks down in predictable ways. I once integrated a function involving an absolute value near the boundary of the integration interval. The derivative was undefined at that point, and Simpson's Rule produced garbage results no matter how many subintervals I used. The workaround was to split the integral at the singularity and integrate each piece separately. It sounds obvious now, but at the time I spent an afternoon staring at convergence plots that made no sense before I realized the issue was the non-differentiable point sitting right in the middle of my interval.
For practical implementation, here is what you need to keep in mind. First, validate your step size against the smoothness of your function. If you know the fourth derivative of your integrand is bounded by some constant M, the error is at most M(b-a)h/180. This gives you a concrete way to estimate how many points you actually need rather than guessing. Second, consider using composite Simpson's Rule by breaking the interval into subregions if your function behaves differently in different parts of the domain. A single global step size is rarely optimal. Third, if you are working with noisy or experimental data, Simpson's Rule can actually amplify the noise because it relies on higher-order polynomial fitting. In those cases, a simple trapezoidal approximation or a spline-based method might give you more reliable results despite being theoretically less accurate for smooth functions. The method also doesn't handle infinite intervals well. If your integral goes from zero to infinity or has an asymptote, you need to transform the variables first. A common substitution is x = a/(1-t) or x = at/(1-t), which maps the infinite domain to a finite one. These substitutions introduce their own derivatives into the integrand, so you end up integrating a more complex expression, but the payoff is that Simpson's Rule can then operate on a bounded domain where it does its best work. For anyone looking to implement this, the algorithm is short enough to write from scratch in under twenty lines of code. You do not need a specialized library for basic usage. Python, MATLAB, or even a spreadsheet will handle it. The real value comes from knowing when to use it and when to reach for something else. Adaptive quadrature methods like Gauss-Kronrod are better choices when you need automatic error control and your function has unknown behavior across the interval. But for routine engineering calculations where the function is known and reasonably smooth, Simpson's Rule remains one of the most efficient tools available.
Get the Full Details