Using a Credit Card at Costco for Maximum Rewards
Unleashing The Power Of Costco Pay By Credit Card How To Maximize Rewards And Benefits
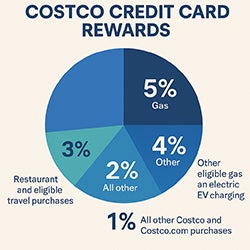
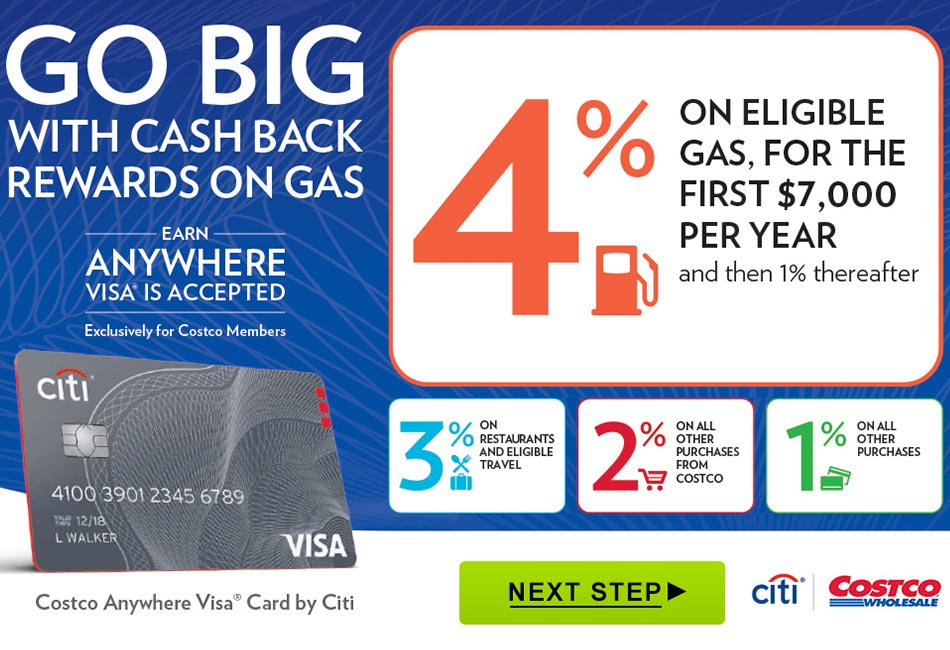
Costco's credit card program is straightforward if you understand how the two main cards differ and where the rewards actually show up. Most people walk out of the warehouse assuming they got zero value from their purchase because they don't immediately see anything credited to their account. The rewards aren't instant in the way most cashback cards work. They come later, usually as certificates in the mail, which is a major design flaw in user experience. The primary card people use is the Costco Anywhere Visa by Citi. It has no annual fee and offers three tiers of reward rates. Two percent back on Costco purchases, four percent back on eligible gas, and one percent on everything else. The two percent at Costco is not deposited into your account. It accumulates throughout the year and pays out as a Costco Cash Certificate once per year, around late February or early March. The gas rewards operate differently. You get four percent back, but only on the first $7,000 spent per calendar year at eligible gas stations. After that, it drops to one percent. I learned about the gas cap after burning through the $7,000 threshold on a single business route in six months. My gas rewards had already flattened to one percent by July. The workaround is simple enough but easy to miss. When you reach the cap, the remaining four percent eligibility doesn't reset until January first. I started staggering my vehicle refuels across two different payment methods after that threshold, which let me partially preserve the higher rate for the rest of the year.
The second card option is a Costco-branded card from Chase. It's less common now but still exists in some regions. That card offers different reward structures and occasionally runs promotions that can beat Citi during certain windows. If you have access to both and live in an area where both are available, there can be a case for rotating between them during promotional periods. The real edge most people miss is the combination of Costco membership benefits with the credit card rewards. The 2% back on Costco purchases applies to everything in the warehouse, including electronics, appliances, and bulk groceries. Those are high-ticket categories where even one percent makes a difference. A $2,000 television or a $3,000 refrigerator gets $60 back in the form of a certificate. Over several large purchases a year, those certificates add up to real money. I've personally collected between $200 and $400 in annual certificates just from regular warehouse shopping. There's an important nuance about gas station rewards that trips up most cardholders. Not all gas stations qualify. Costco requires the station to be independently operated and display the specific eligibility marker. Some major chains with convenience store components fail the eligibility test even though they look like regular gas stations. I found this out the hard way when a fleet of company vehicles ran through a branded station and received zero four-percent rewards on roughly $800 in fuel. I had to call Citi support and dispute each transaction individually to get the rewards adjusted. It took three weeks and five phone calls to resolve.
The checkout process itself is worth paying attention to. At Costco registers, you're prompted to choose a payment method. Using the Costco Anywhere Visa will apply the correct reward rate automatically. Debit cards and other credit cards don't trigger the two-percent or four-percent rates. Some people default to debit because they think it avoids debt, but they lose the rewards entirely. The reward structure is built into the card network agreement, not something the register calculates independently. One limitation that should be mentioned: the Costco Cash Certificates are only redeemable at Costco. They cannot be converted to cash or applied to other purchases. If you stop shopping at Costco, those certificates become useless. I've seen this happen when families relocate to areas without a warehouse location. The unused certificates expire and the money is gone. This isn't a problem for regular Costco shoppers, but it's a material downside that should factor into whether the card makes sense for your situation. Another practical consideration is the timing of the certificate delivery. The payout typically arrives in late winter, which means your effective cashback rate is delayed. If you're carrying a balance on the card, the interest charges will completely erase the rewards. The zero annual fee only matters if you pay the balance in full every month. Carrying a balance at an APR that can exceed twenty percent turns a two percent reward into a net loss almost immediately.
Get the Full Details

The application process is standard. Go to the Citi website, apply for the Costco Anywhere Visa, and link it to your Costco membership number during the application. The membership number is required. You cannot get the rewards without the linkage. Processing takes about ten days, and the card arrives in two weeks. Once you have it, register it in the Citi mobile app for easier tracking of your reward accumulation. The app shows your gas reward cap progress and your estimated annual certificate amount. Use this to monitor how close you are to the $7,000 gas threshold, especially if you drive frequently for work. Knowing this number prevents surprises when your gas rewards drop unexpectedly. For maximum benefit, use the card consistently at Costco, pay off the balance monthly, and track your gas spending throughout the year. The rewards are real, they just require a slightly longer wait than most cashback cards offer.