Using Your Direct Express Card Beyond Just Checking Accounts
Most people get their Direct Express card and treat it like a normal debit card. It works fine for groceries and gas, but there are a few corners of the program that nobody really explains well. I ran into this problem last winter when I tried to set up a recurring auto-pay for a medical provider. The payment got declined three times in a row, and I had no idea why. Turns out Direct Express doesn't automatically authorize recurring merchant charges the way a traditional bank account does. You have to call their customer service line and put in a request to enable that feature, or the merchant runs into authorization holds that the system rejects. I ended up switching that payment to a manual monthly transfer instead, but it took me about forty minutes on the phone just to get the recurring billing enabled. That's the kind of friction that slows you down if you don't know about it ahead of time.
Unleash The Power Of Your Direct Express Debit Mastercard Your Comprehensive Guide
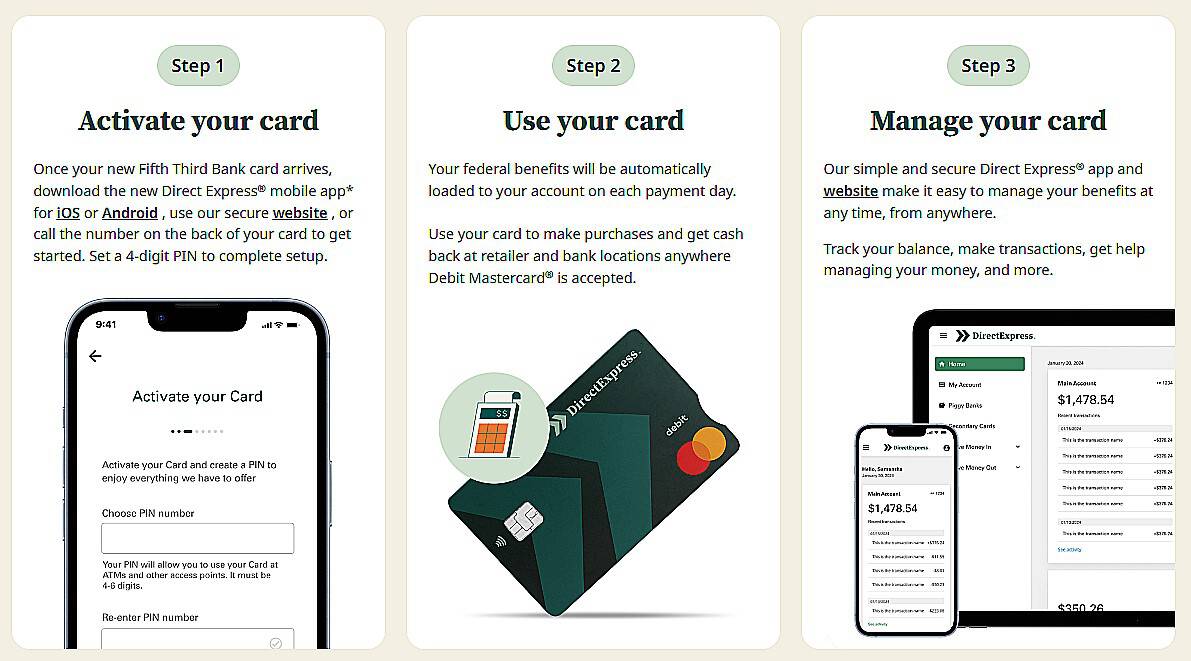
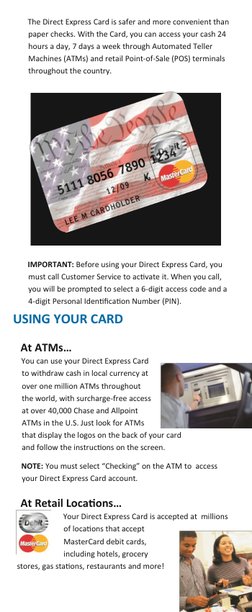
This card is issued by Comerica Bank and serves as the primary disbursement tool for federal benefit payments — things like Social Security, Railroad Retirement, SSI, and VA benefits. It loads on the scheduled deposit date, and that's basically it for most cardholders. But the card supports several features that sit unused by a lot of people who just swipe and forget. One thing most people don't know: you can set up zero-dollar or one-dollar verification transactions to confirm your card is active with online merchants before making a larger purchase. The system processes it instantly, and the verification amount gets reversed within one to two business days. I started doing this with any new online vendor — it saves you from having a $200 charge declined and waiting three days for a refund to clear. Another nuance involves ATM fees. Direct Express does offer free ATM access at certain locations, but only if you're using the MoneyPass network. If you go to a regular bank ATM outside that network, you get hit with both the ATM operator fee and a surcharge from Direct Express. I tracked this for a few months and found I was paying roughly $4.50 per out-of-network withdrawal. Once I switched to MoneyPass ATMs exclusively, that cost dropped to zero. Downloading the MoneyPass app was the fix.
There is also a small but real limitation you need to understand: the card has a daily purchase and ATM withdrawal limit, and it is not as high as most people expect. For most accounts the purchase limit sits around $4,000 per day and the ATM limit is lower, usually $500 to $1,000 depending on your verification level. If you need to make a larger one-time purchase — say a car repair or a medical procedure — you will need to contact Direct Express ahead of time to request a temporary limit increase. They can process that within a business day, but if you show up at the dealership without doing it first, you will lose time and possibly the deal. The mobile app is functional but not polished. It handles balance checks, transaction history, and card locking, which covers the basics. The direct deposit enrollment feature inside the app works, but the interface for linking a new bank account or setting up a new employer deposit is clunky. I once spent twenty minutes trying to add a new deposit source because the app kept timing out. Calling their support line directly completed the same task in under five minutes. Another practical detail: your Direct Express card is reloadable, which means you can receive transfers from other accounts in addition to your government deposits. If someone sends you money or you move funds from a personal checking account, those balances arrive on the same schedule as your benefit deposits. But here is the catch — the reloadable feature is not turned on by default for all account types. If you try to receive a transfer and it gets rejected, that is usually the reason. Calling customer service and requesting that feature be enabled is a quick fix.
Get the Full Details
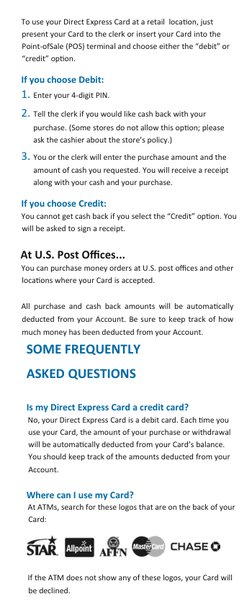
One more thing that catches people off guard: Direct Express does not offer overdraft protection or line of credit options. If your deposited amount is $1,200 and you spend $1,250, the transaction declines. There is no buffer. This is actually a feature if you think about it — it prevents debt accumulation. But if you live paycheck to paycheck on benefit income, you need to track your available balance closely, especially during months when your deposit date shifts. A deposit that lands on the 1st instead of the 3rd means you have fewer days to cover the month end. I would recommend keeping a simple running log of your deposit dates and expected spending. Most people overdraw simply because they miscounted days between deposits, not because they spent irresponsibly. The Direct Express website has a balance alert feature, and I would use it. Setting up a low-balance notification at $50 gives you a buffer to adjust your spending before the card actually declines. The card works without issue for everyday purchases at major retailers and online merchants. It is accepted anywhere Mastercard debit is taken. The main areas where you will feel limitations are recurring bill payments, large single purchases, and international transactions — the card generally does not support foreign currency purchases or online merchants that require AVS verification with a ZIP code that does not match your card registration.
If you need a more flexible banking relationship — overdraft protection, higher limits, better customer support response times — a traditional checking account at a local credit union or community bank is probably a better fit. Direct Express is designed for government benefit delivery, not for general banking. Knowing where it fits and where it does not is what actually makes the difference between frustration and control.