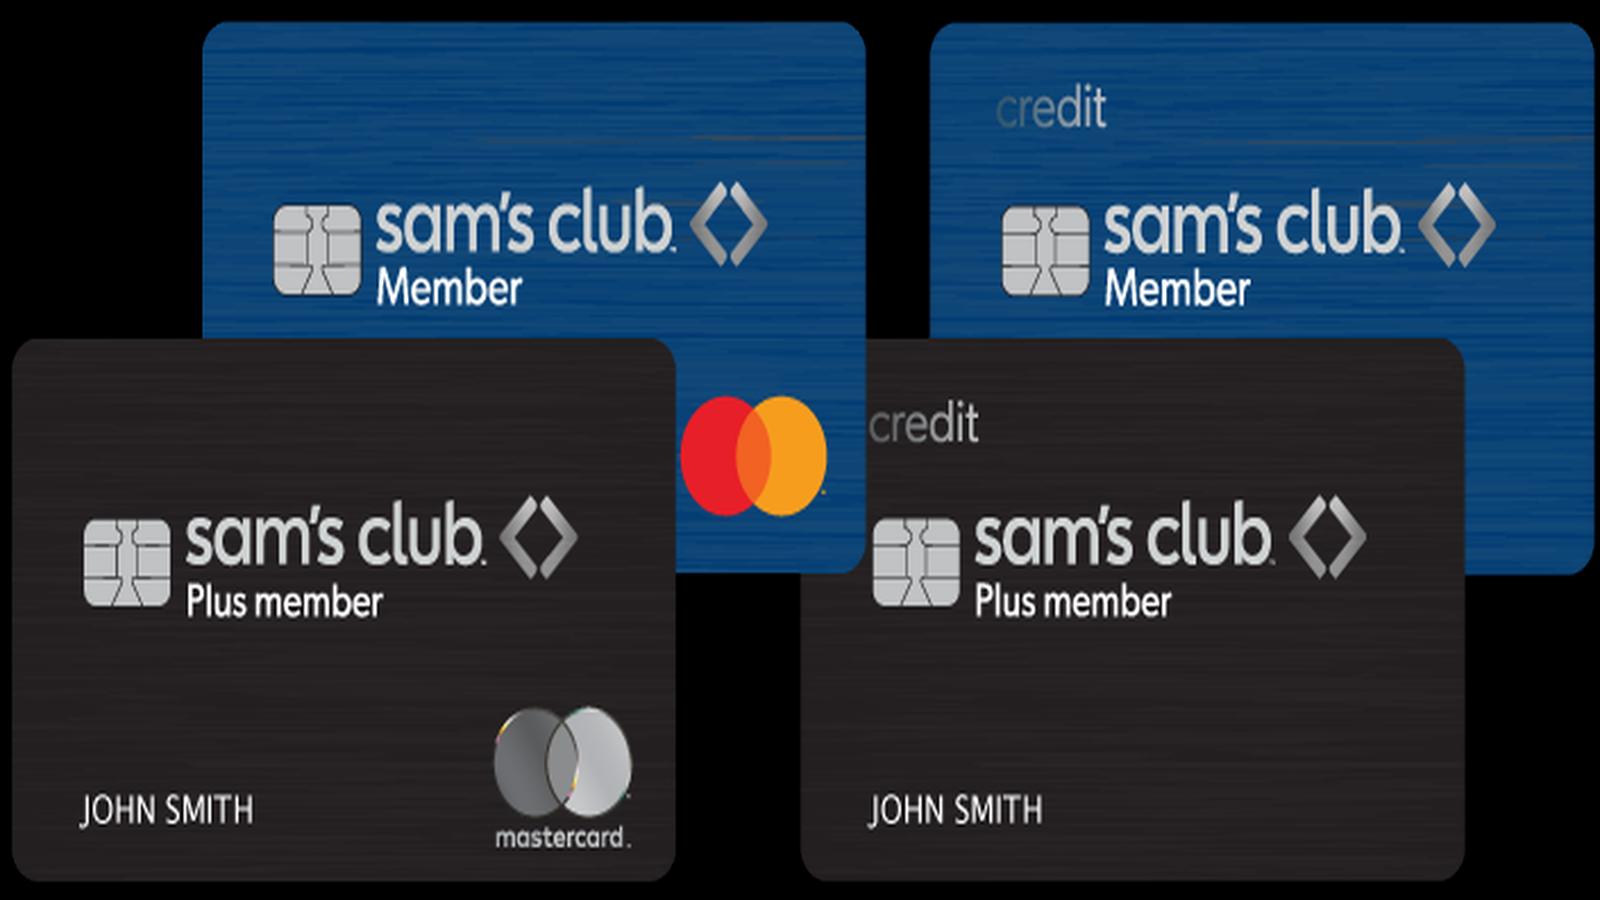
Understanding the Sam's Club Credit Account
Sam's Club offers a branded credit card through Visa, and it is actually tied to their membership program rather than being a standalone financial product. The card provides cashback on purchases at Sam's Club locations and gas stations, with reduced rates on other spending. It is issued by Synchrony Bank, which handles all the account management online. The way this card works is straightforward enough, but there are some details that matter more than the marketing materials suggest. You need an active Sam's Club membership—either an individual or business tier—to even apply. The card itself does not grant you warehouse access. I learned this the hard way when I tried applying through a friend's account during their annual check-in, and the system rejected it immediately because my profile wasn't linked to a valid membership number at application time. Once approved, the card earns 5 percent cashback on Sam's Club purchases, 3 percent on gas, and 2 percent on restaurants and travel. Everything else falls to 1 percent. There is no annual fee on the base version, which makes it decent for people who shop there regularly. The real value comes from stacking it with the membership savings. If you spend $2,000 a month at Sam's Club, you are looking at roughly $100 in annual cashback before the gas and restaurant categories even factor in.
The application process happens through Synchrony's website, and approval is usually instant if your credit profile is clean. They do a hard pull, which can drop your score by a few points temporarily. I noticed my utilization ratio spike after approval because Synchrony reports the full credit limit as available to the bureaus, even though I was only using a fraction of it. This inflated my utilization calculation for about two months until the next statement cycle adjusted. One thing most people miss is that the card only tracks spending at Sam's Club and participating vendors. Grocery stores that happen to be inside a Sam's Club warehouse don't count unless they have the specific Merchant Category Code associated with the club. I had a vendor charge me at what looked like a Sam's Club location, but the transaction posted as a regular retail purchase instead of the 5 percent tier because the terminal wasn't properly configured. The online portal lets you manage rewards, view statements, and set up autopay. Synchrony sends monthly statements on the 15th, and you have 25 days from that date to pay without interest. If you carry a balance, the APR jumps to around 20 percent, which wipes out any cashback advantage almost immediately. I recommend paying in full every month or treating this card as a pure loyalty tool rather than a credit vehicle.
There are also promotional offers occasionally, like 10 percent off your first purchase or bonus cashback during holiday seasons. These rotate monthly and require you to activate them in the account settings before shopping. I once missed a 5 percent promotion because I assumed it applied automatically, and the extra $30 in cashback just disappeared into the void. If you already have the Plus membership, you might not gain much from the card alone. The membership itself gives you 10 percent cashback on most purchases when paid with the Sam's Club credit. Stacking both is possible but the benefits overlap significantly. A better use case is for people who shop at Sam's Club infrequently—they can save on the membership cost by offsetting it with card rewards over time. Customer service through Synchrony is reachable at the number on the back of the card. Response times vary, but I found their chat support to be more reliable than phone. Wait times on the phone can stretch to 40 minutes during peak hours, while chat typically connects within five. I resolved a misplaced transaction dispute via chat in about 12 minutes total.
Get the Full Details
Common Pitfalls and Workarounds
The biggest issue people encounter is the reward tracking. Cashback does not appear until the statement closes, which means you might see a delay of up to 30 days between purchase and credit. Some users report that their rewards seem to vanish when they switch payment methods mid-cycle. This is not a bug—the system only calculates based on the final payment method used at checkout. Another quirk involves international transactions. Sam's Club accepts foreign currency, but the card converts at Visa's rate plus a small markup. If you shop while traveling, you might earn the 5 percent category reward, but the actual dollar value will be slightly lower due to exchange fees. I paid about $200 extra in conversion costs on a single trip because I did not check the terms carefully. The reward redemption options are limited compared to other cards. You can cash out to a bank account, get a statement credit, or request a gift card. The gift card route gives you a slight bonus if you choose Sam's Club-branded cards, but the cashback option is more flexible. I usually go for the bank deposit because it clears faster, though it takes 3-5 business days to post.
If your application gets denied, you can reapply after 30 days. Synchrony does not lock you out permanently for minor credit issues. I know someone who applied three times over six months, got denied twice, and finally approved on the third attempt after paying down their other credit card balances. The system seems to weigh recent inquiries heavily in the scoring model.
Is It Worth It
The answer depends entirely on your shopping habits. If you shop at Sam's Club once a month or less, the card provides marginal benefit. The 5 percent return is competitive, but you need volume to make it meaningful. Someone spending $500 monthly at the warehouse earns about $30 in cashback annually—a modest sum that may not justify the hard inquiry or additional account management. Regular shoppers who spend over $1,500 per month see the real value. That level of usage generates roughly $90 in annual rewards plus the gas and restaurant bonuses, which can push total earnings toward $120-150. Combined with the membership discount, the effective savings rate approaches 8-10 percent on many purchases, which is above average for retail credit cards. There are downsides. The card does not offer travel insurance, purchase protection, or extended warranty benefits that competitors provide. If you value those protections, you are better off with a different card. Synchrony also does not provide a credit monitoring service or fraud alerts beyond the standard Visa notification system. For security-conscious users, this is a gap worth noting.
The application process requires a Social Security Number and proof of address, which some users find invasive. You cannot apply as a guest or with just an email. The identity verification step sometimes fails for people with thin credit files, causing the system to request additional documentation like a utility bill or bank statement. This adds 2-3 days to an otherwise instant approval process. Finally, the card is not ideal for people who prefer to pay with digital wallets. While Apple Pay and Google Pay are supported, some older Sam's Club terminals do not recognize them. I have had transactions decline at self-checkout because the NFC reader was incompatible with the wallet integration. Bringing a physical card or using the mobile app barcode for payment avoids this entirely.