Car loan calculators aren't magic, but they stop you from walking into a dealer with your eyes closed
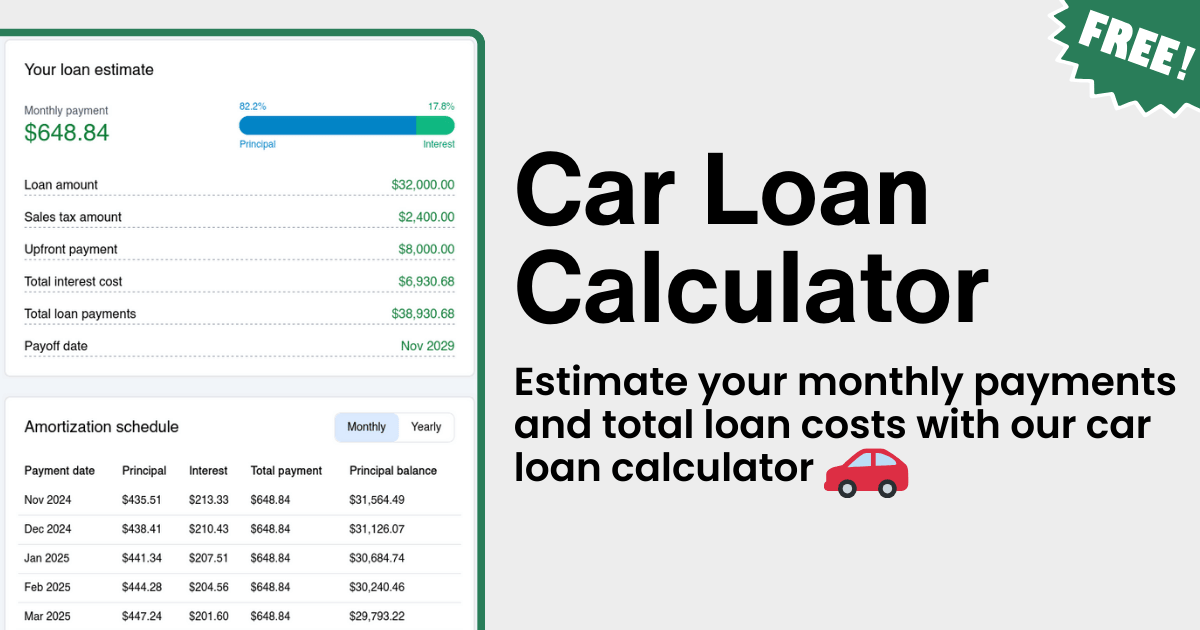
I've sat across from enough finance managers to know the exact moment their eyes light up. You walk in with no idea what your numbers should look like, and that's when the real work begins for them. Not in your interest. A car loan calculator from LendingTree changes that dynamic because you go in knowing your monthly payment range before anyone mentions anything about add-ons or extended warranties. The tool itself is straightforward. You enter the vehicle price, your down payment amount, the loan term you're considering, your estimated interest rate, and sometimes trade-in value if applicable. It spits out a monthly payment figure. The problem is most people stop there and think they're done. They're not. The calculator gives you a starting point, not a final answer.
Unleash The Power Of Lendingtree How Their Car Loan Calculator Can Save You Thousands
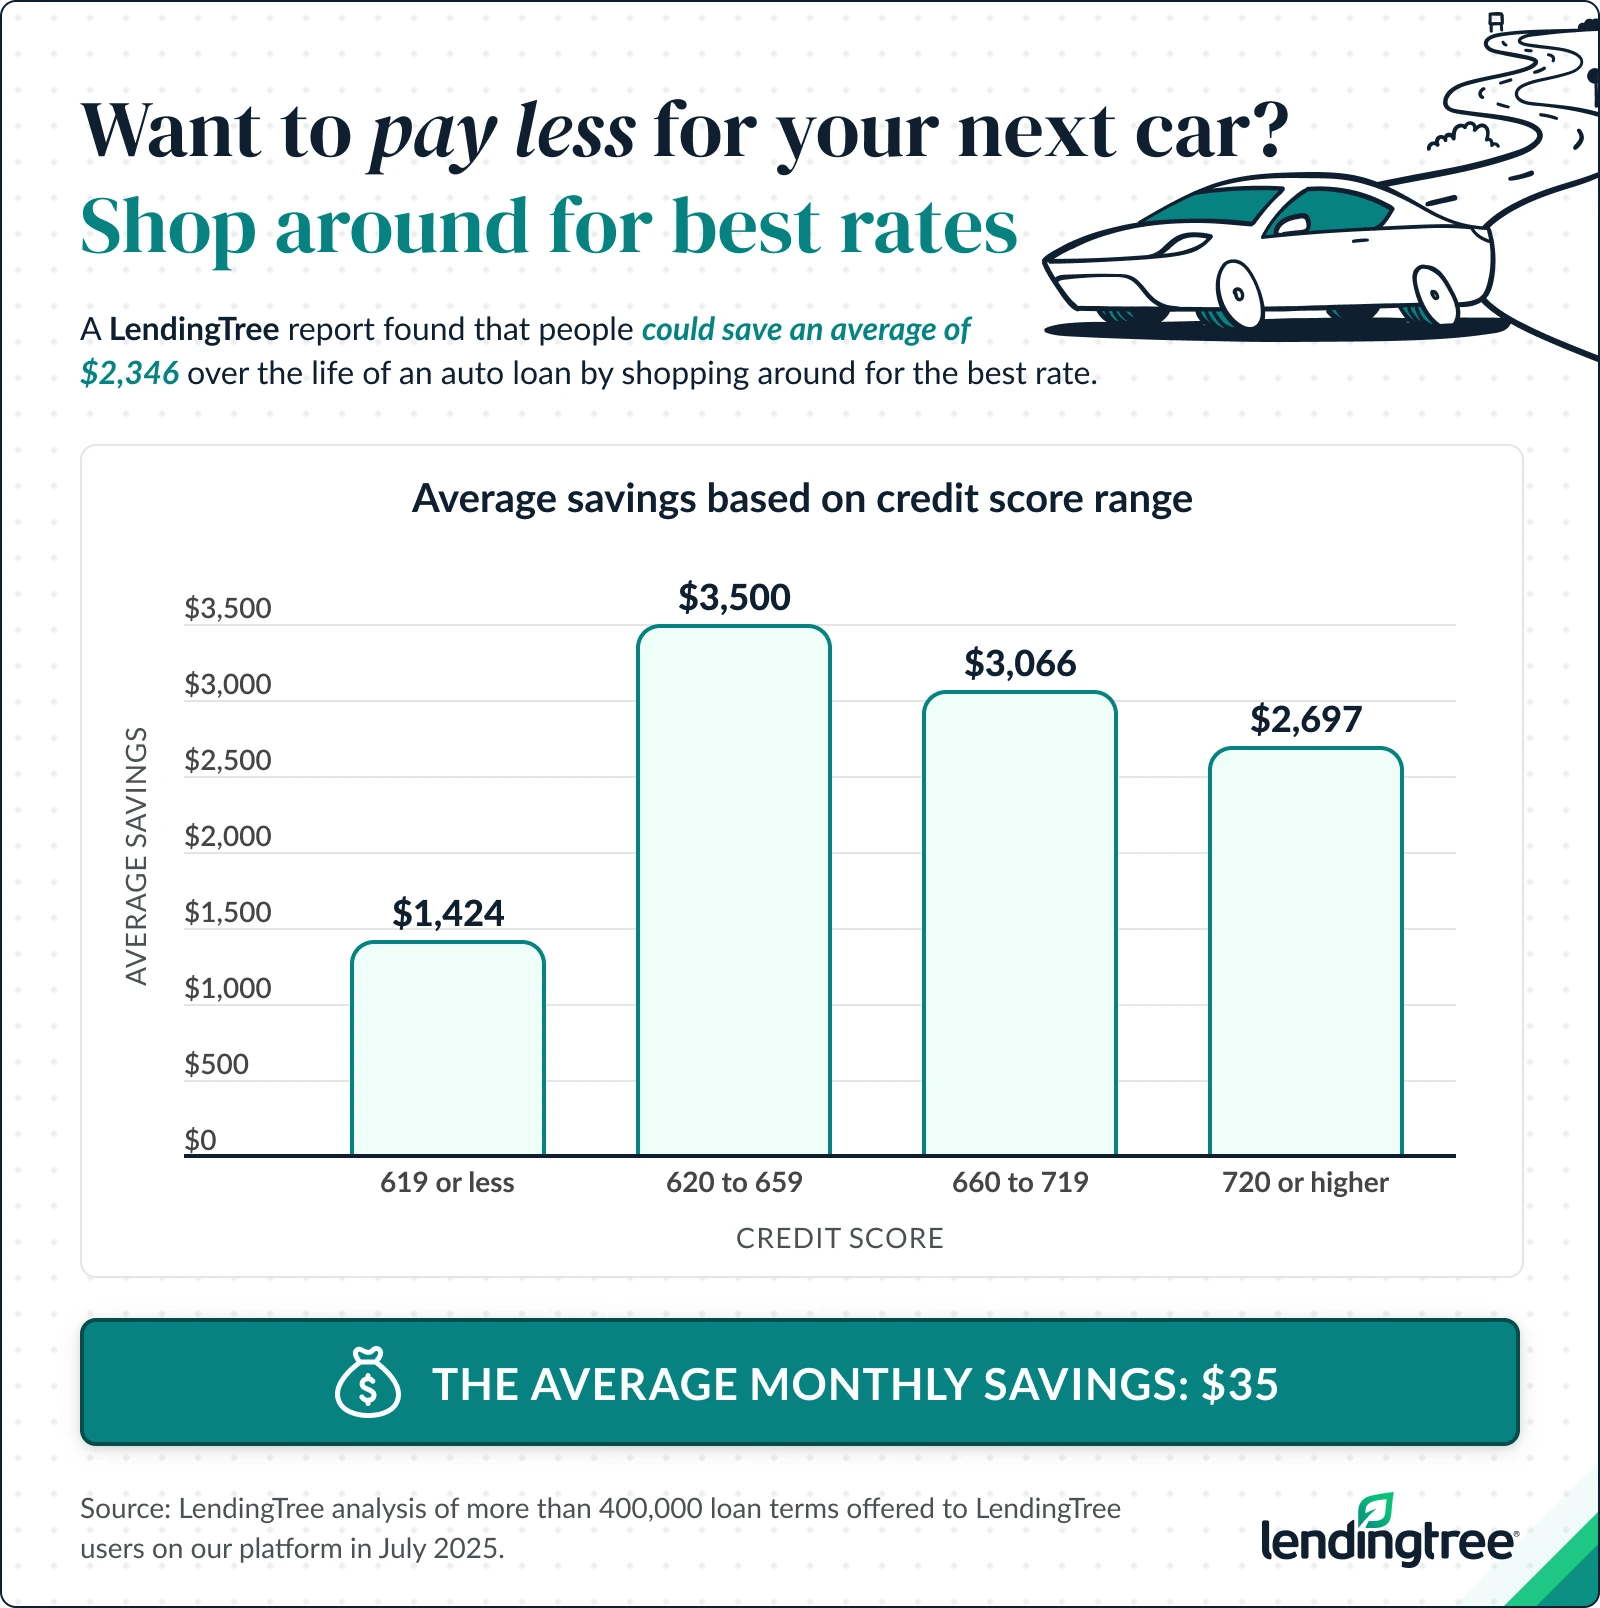
Here's what actually happens when you use it properly. You run the numbers for a $35,000 sedan at 6.5 percent interest over sixty months with a $5,000 down payment. The calculator shows roughly five hundred and twenty dollars a month. That number becomes your anchor. When the dealer quotes you six hundred and eighty, you immediately know something is off. Either the rate got inflated, or they padded the vehicle price, or both. Without that baseline calculation you'd probably just accept the higher number out of fatigue. I ran into a specific issue last year that every calculator user should know about. I was comparing two different quoted rates for the same loan profile. The LendingTree calculator showed a twelve hundred dollar difference over the life of the loan between a six percent and a seven point five percent rate on a twenty-eight thousand dollar vehicle over seventy-two months. That seemed significant, so I dug into why my local credit union was offering the lower rate while the dealer's in-house financing pushed the higher end. Turns out the credit union rate required autopay enrollment and automatic payments deduction, which shaved a quarter point off. The calculator doesn't show you those small adjustments. You have to factor them in yourself after getting your numbers from the tool. Another thing people miss completely is how negative equity from a trade-in affects the calculation. If you owe four thousand on your current car and it's only worth three thousand, that thousand in negative equity gets rolled into your new loan. Most calculators let you input trade-in value separately, but the math they use assumes you're paying it off at the same rate. In practice, dealers often roll it in at the new loan's interest rate, which could be higher than what you're currently paying. That's where the thousands disappear without you noticing because you're focused on the monthly payment instead of the total cost.
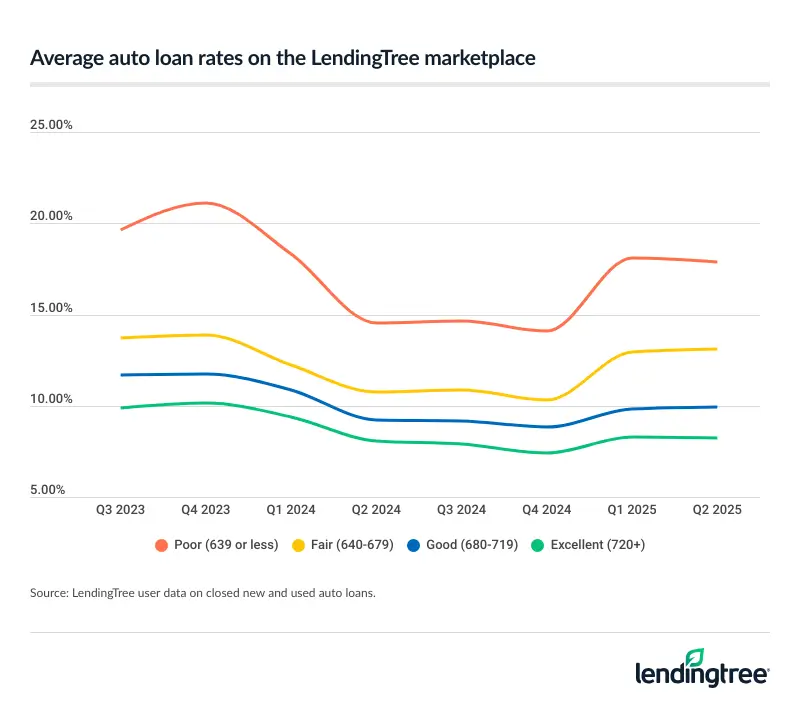
The calculator also doesn't account for sales tax variations by state. Some states tax the full purchase price before trade-in credits. Others only tax the difference. Running a clean calculation with and without tax differences between adjacent states can reveal genuine savings. I've seen people drive an extra hour to buy a car in a neighboring state purely because the tax structure made a meaningful difference on a larger purchase. There are limitations to what this tool can do for you. It won't negotiate your rate. It won't tell you whether a longer loan term actually saves you money in the long run even though the monthly payment looks better. A seventy-two month loan at seven percent will always cost more in total interest than a sixty month loan at six percent, no matter what the monthly comparison shows. The calculator makes this visible if you run both scenarios side by side, which takes about thirty seconds. You should also compare the output against actual lender offers before you commit to anything. LendingTree's calculator uses published average rates, but your personal rate depends on your credit profile, debt-to-income ratio, and the specific lender's risk models. I've seen people get quoted rates two points higher than the calculator estimate simply because they had recent hard inquiries on their credit report that the tool doesn't consider.
Get the Full Details

The most practical use of this calculator is as a range-finding instrument. Pick your target monthly payment, then work backward to see what loan amount that supports at current rates. If you want four hundred dollars a month at six percent over sixty months, the calculator tells you the maximum vehicle price you can realistically finance after your down payment. That number becomes your shopping constraint. You stop looking at cars that push you into a longer term or a higher rate just to fit the price. Running the tool takes approximately two minutes if you have your numbers ready. Checking three different term lengths and two different rate scenarios adds maybe another five minutes. That time investment prevents you from signing a contract you'll regret three years from now when you realize you paid eight thousand dollars in interest on a car that depreciated ten thousand in the same period. Use the calculator, get your numbers, then walk into the dealership with a written summary of what you expect to pay. When the finance manager tries to adjust anything, you can point to your calculation and ask exactly where the difference comes from. That question alone usually stops the padding before it starts.