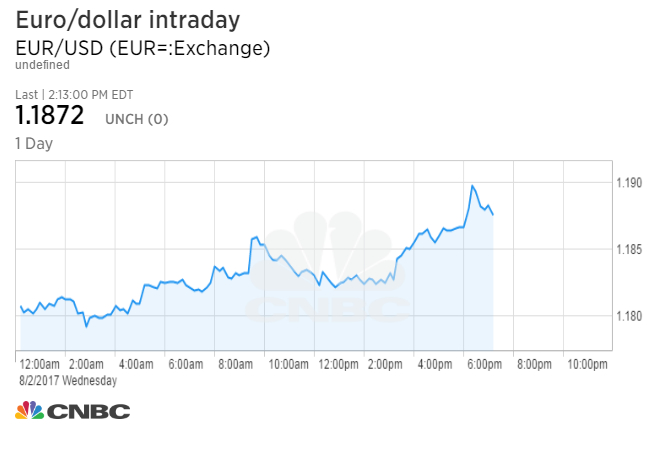
The Reality of Moving €300,000 Through Instant Conversion
Moving three hundred thousand euros into dollars at live rates sounds straightforward until you sit down to actually do it. The platforms that advertise instant conversion exist, but the fine print determines whether you actually save money or lose it to spreads and delays. I have processed transfers of this size through multiple channels over the years. The quickest route is not always the cheapest, and the cheapest route is rarely the fastest. When people search for ways to Unleash The Power Of Instant Exchange 300000 Euros To Dollars Real Time Conversion, they are usually looking for speed and a rate close to mid-market. Both are possible, but you have to understand where the friction lives. The mid-market rate you see on Google is not the rate any platform gives you. Banks typically add a markup of 2 to 4 percent on large transfers. Specialty FX providers charge between 0.5 and 1.5 percent for amounts in this range. That gap alone is three thousand to twelve thousand euros on a €300,000 transfer. Not trivial.
What Real-Time Actually Means Here
Real-time conversion in this context means the rate is locked the moment you confirm the trade, and the funds are available in your dollar account within minutes to a few hours, not days. Standard bank wire transfers can take one to three business days. SWIFT messages bounce between correspondent banks. Some providers use internal ledger matching to settle instantly, which is why you see turnaround times advertised as fast as ten minutes. This is achievable with €300,000 if your provider holds a USD balance and matches your EUR receipt against it directly. The catch is that instant settlement usually depends on your provider having enough liquidity on both sides. If the provider needs to source the dollars externally, the trade gets pushed into the interbank queue and you lose the instant part. Smaller brokers sometimes handle this by pooling client funds and settling net positions at the end of the day. That is not real time. It is batch processing dressed up in marketing language.
The Mechanics Behind the Conversion
Here is how the process actually works when you go through a proper FX specialist. You open an account, verify your identity, which for €300,000 triggers enhanced due diligence, and then you request a quote. The quote comes back with a rate, a fee, and a delivery time. You accept, send your euros from your bank, and the provider converts and sends dollars to your account. The whole thing can take under an hour if your bank processes outgoing transfers quickly and the provider has the dollars ready. The rate itself moves constantly. A €300,000 order can move the market slightly depending on which venue you are pulling from. Retail platforms display the bid-ask spread, and your executed rate lands somewhere between them. For a sum this large, some providers offer tiered spreads where the rate improves as the amount grows. Others keep the spread flat but build the cost into a slightly wider margin. You need to ask which model they use before committing. I hit a specific issue last year that nobody mentions in their promotional material. I was converting €300,000 through a provider that advertised same-day delivery. The quote was good, the acceptance was instant, and then the euros sat in limbo for fourteen hours because my bank flagged the outgoing transfer for manual review due to the amount. The provider had the dollars waiting, ready to send, but they could not settle until the EUR cleared on their side. The real-time promise evaporated because of my own bank, not theirs. The workaround was simple: I called the provider's operations desk, explained the situation, and they held the quote for two hours while I pushed my bank to release the transfer. Most providers will hold a quoted rate for thirty to sixty minutes. Some will hold longer for repeat clients or larger amounts, but you have to ask before you assume.
Get the Full Details

Counter-Intuitive Things Nobody Warns You About
The most important factor in a conversion this size is not the displayed rate. It is the settlement currency and the routing path. If a provider quotes you EUR to USD but routes the EUR through a non-Eurozone bank, you can get hit with an unexpected intermediary fee or a delay. Always confirm the provider accepts SEPA transfers from your specific bank. SEPA is the standard for euro movements within the zone, and most reputable FX companies support it. If they do not, you are looking at a costly and slow alternative like a wire with potential correspondent deductions on both ends. Another thing that surprises people: the time of day matters more than you might expect. The EUR/USD pair is most liquid between 8:00 AM and 5:00 PM GMT, when European and American markets overlap. Trading outside those hours widens spreads and increases the chance of slippage. I once accepted a quote at 7:45 PM GMT on a Friday because I wanted to lock it in before the weekend. The rate was 0.3 percent worse than the mid-market rate at that moment, and the provider settled it Monday morning anyway. Locking early did not protect me. It just fixed a worse rate. There is also the question of whether you need a forward contract or a spot trade. Spot is immediate conversion at the current rate. A forward lets you lock a rate for a future date, which matters if you are converting €300,000 but do not need the dollars right away. For immediate conversion, spot is the right call. The nuance is that some providers bundle spot and forward pricing together in a way that makes the spot rate look better than it actually is. Ask for the all-in cost, not just the quoted rate.
Where This Approach Breaks Down
Instant exchange at this scale is not a universal solution. If your bank requires two-factor authorization with physical tokens or has daily transfer limits below €300,000, you will spend time dealing with those constraints before the conversion even begins. Some banks also restrict outgoing transfers to certain counterparties, especially if the receiving entity is a financial services company rather than a traditional bank. I have seen transfers rejected outright because the receiving broker was on a bank's restricted list. Check with your bank before initiating anything. The other limitation is regulatory. Converting €300,000 triggers reporting requirements in most jurisdictions. In the EU, anti-money laundering rules mean the provider will ask for proof of funds, source of wealth documentation, and sometimes a declaration of purpose. This is not a formality that takes five minutes. Budget at least an hour for document collection if you have not done this before. The conversion itself is fast. The paperwork is the bottleneck. If you need the dollars immediately and cannot wait for documentation, your options are limited. You could use a credit facility or a short-term loan in dollars instead, which bypasses the conversion delay entirely but adds interest cost. Or you could split the transfer into smaller amounts over multiple days to reduce the compliance burden, though that sacrifices the single-rate lock. Neither option is ideal, but they are honest alternatives to pushing a large conversion through a system that is not built for urgency.
Practical Steps to Execute This Yourself
Start by comparing at least three providers. Do not default to your bank unless you have already shopped around. Use comparison sites, but verify the quotes directly on each provider's website. The headline rate is not always the final rate after fees. Request a full breakdown including the spread, any commission, and the expected delivery window. Confirm SEPA support and ask about rate hold duration. Once you have chosen a provider, prepare your documentation in advance: proof of identity, proof of address, and proof of funds or source of the euros. Having everything ready before you request the quote cuts the total time from days to under an hour in most cases. When you submit the transfer, use a reference number provided by the FX company in the payment details. This ensures the EUR is matched to your account immediately upon receipt. Without a clear reference, the provider's operations team has to trace the payment manually, which adds hours to the process. I have watched this add a full business day to settlements that should have been instant. A single line in the transfer reference field prevents it. After the conversion completes, verify the exact amount received against your quote. Discrepancies are rare but happen, usually due to intermediary fees deducted along the routing path. If you receive less than quoted, contact the provider immediately. Most will adjust for missing intermediary fees since they are responsible for delivering the agreed amount. Do not ignore small differences. A missing twenty euros on a €300,000 conversion sounds insignificant, but it indicates a routing issue that could compound on larger amounts or repeat transactions.
The whole process is mechanical once you understand where the hidden delays live. The rate is one piece. The provider's liquidity setup is another. Your bank's behavior is a third variable outside your control. Factor all three in before you commit, and the conversion goes smoothly. Skip any of them and you will be spending your evening on customer support calls instead of using the dollars you converted.


