The Practical Side Of Business Cards For Companies
Managing corporate spend used to mean digging through shoeboxes of receipts and reconciling expense reports at the end of every month. I spent three years doing exactly that before a controller finally told me to look into business credit cards instead of letting every department charge to their own accounts. The learning curve was real. It wasn't automatic, and it definitely wasn't free. The Bank of America Corporate Choice Card program is one of the bigger options out there, and honestly, it's the one I see small to mid-sized companies gravitate toward most often. The basics are straightforward. You apply through a dedicated business portal, you get a primary card linked to a corporate line of credit or a charged account structure, and then you issue sub-cards to employees with customizable spending limits and category controls. Most people figure that part out in about a week if their paperwork is clean. The tricky part starts after the cards arrive.
Unleash Corporate Power A Comprehensive Review Of Bank Of America Corporate Credit Cards
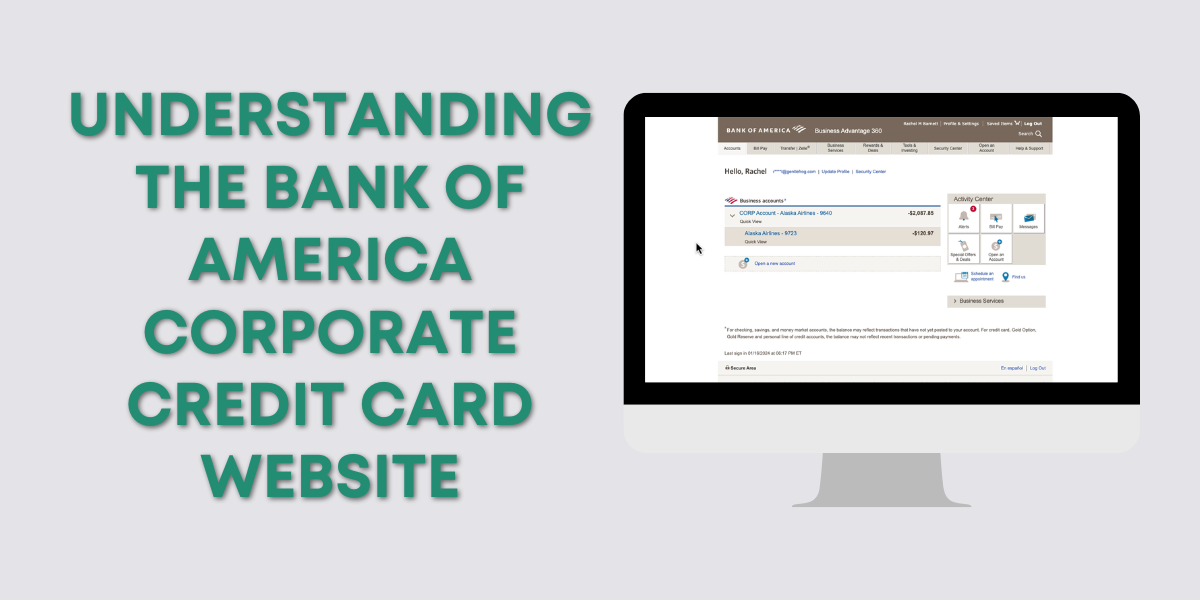
Here's what actually happens when you implement this. Your finance team sets up the account with a master credit limit, say fifty thousand dollars spread across the company. Then you log into the BofA business portal and start adding cards. Each card gets its own limit, maybe five hundred for an intern, five thousand for a sales rep, ten thousand for a project manager. You can lock certain categories — meals, travel, office supplies — so a cardholder can only spend where you expect them to spend. That alone saves you from the kind of embarrassment where someone charges a personal vacation to the company card and you find out three weeks later during reconciliation. The rewards structure on these cards typically runs at one to two percent cash back on most purchases, which sounds modest until you're talking about monthly spend in the tens of thousands. Our team averaged roughly one point five percent back on about sixty thousand dollars a month in operational costs. That's around nine hundred dollars a month, ten thousand eight hundred a year, just sitting there from spending we were already doing. We used it to offset software subscriptions and insurance premiums. Not life-changing money, but it's free money you'd otherwise leave on the table by paying everything by check or wire transfer. I ran into a specific problem about eight months into our program that I wish someone had warned me about. One of our regional managers needed to book a large vendor payment — a single transaction around eight thousand dollars — and the card got declined. Not a technical error, just a per-transaction limit set too low. The card had a ten thousand total monthly limit, but the per-transaction cap was only five thousand. Getting it resolved required calling corporate card support, verifying the manager's identity through three separate authentication steps, and waiting forty-five minutes for a limit increase to process. That's not terrible, but it's enough to make you wish the portal had a self-service limit adjustment feature. It doesn't, at least not at the tier level we were on. If you're managing a larger team, I'd recommend building a buffer into your per-transaction limits from day one. Set them at least double what you think any single purchase would realistically be.
The expense reporting integration is probably the strongest practical feature. BofA exports data in CSV format that maps cleanly to most accounting software — QuickBooks, NetSuite, even basic spreadsheet reconciliation. I used to pull together monthly expense summaries that took me roughly two hours of manual work. After switching to the automated export workflow, it dropped to about twenty minutes. The catch is that the export only goes back ninety days unless you upgrade to their higher-tier reporting package, which runs an additional monthly fee per card. For a company under fifty employees, the base tier is usually fine. Beyond that, it gets expensive fast. There are some things the promotional materials don't highlight. First, the application process requires verifiable business revenue. If your company is less than a year old or pulling in under two hundred and fifty thousand annually, your approval odds drop significantly. BofA looks at both the business credit profile and the personal credit of the primary applicant, so a thin business file means they'll weight the personal score much heavier. Second, annual fees exist. The Corporate Choice Card carries a first card free and twenty-five dollars per additional card, which is reasonable compared to some competitors charging sixty or seventy per add-on. But over time with a growing team, those add-on fees accumulate. At thirty additional cards, that's seven hundred and fifty dollars a year before you even consider rewards or savings. Another nuance that trips people up is the foreign transaction fee structure. Most of the standard corporate cards from BofA charge a point five percent foreign transaction fee. That's lower than many consumer cards, but if your team travels internationally for client meetings or vendor visits, that adds up. A consultant flying to London and spending two thousand on expenses would hit a ten dollar foreign transaction fee on every charge. Over a year of regular international travel, that's easily two hundred to four hundred dollars your team is losing to fees that have no business cost justification. Some enterprise-level BofA products waive this, but you need to be on a negotiated commercial account, not the standard self-serve product, to get that benefit. It's worth asking about during the application if your team travels, because the upgrade path isn't clearly advertised on the marketing page.
Get the Full Details

The customer service side is mixed. The general business banking line has decent hours, but the dedicated corporate card support queue can take twenty to thirty minutes on a weekday afternoon. I've waited up to forty-five minutes during end-of-month close periods when everyone is scrambling to reconcile. If you need urgent limit increases or disputed transactions resolved, calling during mid-morning Tuesday through Thursday gives you the best shot at getting through without waiting. It's a small thing, but it affects how smoothly your finance team can operate when something breaks. For companies already banked with BofA on their operating accounts, the integration is seamless. You can set up automatic payments from your business checking to the corporate card account, which eliminates missed payment penalties and helps maintain a healthy credit utilization ratio. The minimum payment is usually a small percentage of your balance, but paying the full statement balance every month is the only move that makes financial sense. Carrying a balance on a corporate card at commercial APR rates — which currently run in the nine to sixteen percent range depending on your credit profile — is a fast way to eat into whatever rewards you're earning. I've seen companies do this accidentally when a large quarterly tax payment hits the card and the balance exceeds what they have liquid in checking at statement closing. The biggest mistake I see companies make is treating corporate cards like personal cards with higher limits. The controls BofA offers — category locks, merchant category code restrictions, spending alerts, and real-time transaction notifications — are genuinely useful if you configure them properly. Left default, they're practically useless, and you end up with the same spend visibility problem you started with. I'd recommend scheduling a fifteen-minute configuration review with your finance lead within the first week of receiving the cards, before anyone starts using them casually. The time investment pays for itself the first time a limit violation catches an unauthorized purchase before it posts.
If your company is small and doesn't need employee sub-cards at all, a standard BofA business credit card like the Bank of America® Business Advantage Cash Rewards card might be simpler and cheaper. The corporate program is designed for organizations with five or more cardholders, spend exceeding twenty thousand monthly, and a finance function that benefits from granular controls. Going corporate on that scale when you could use a regular business card just adds complexity without proportional reward. Know your actual needs before committing to the multi-card enterprise setup.