Tracking Your USPS Money Orders Actually Works If You Do It Right
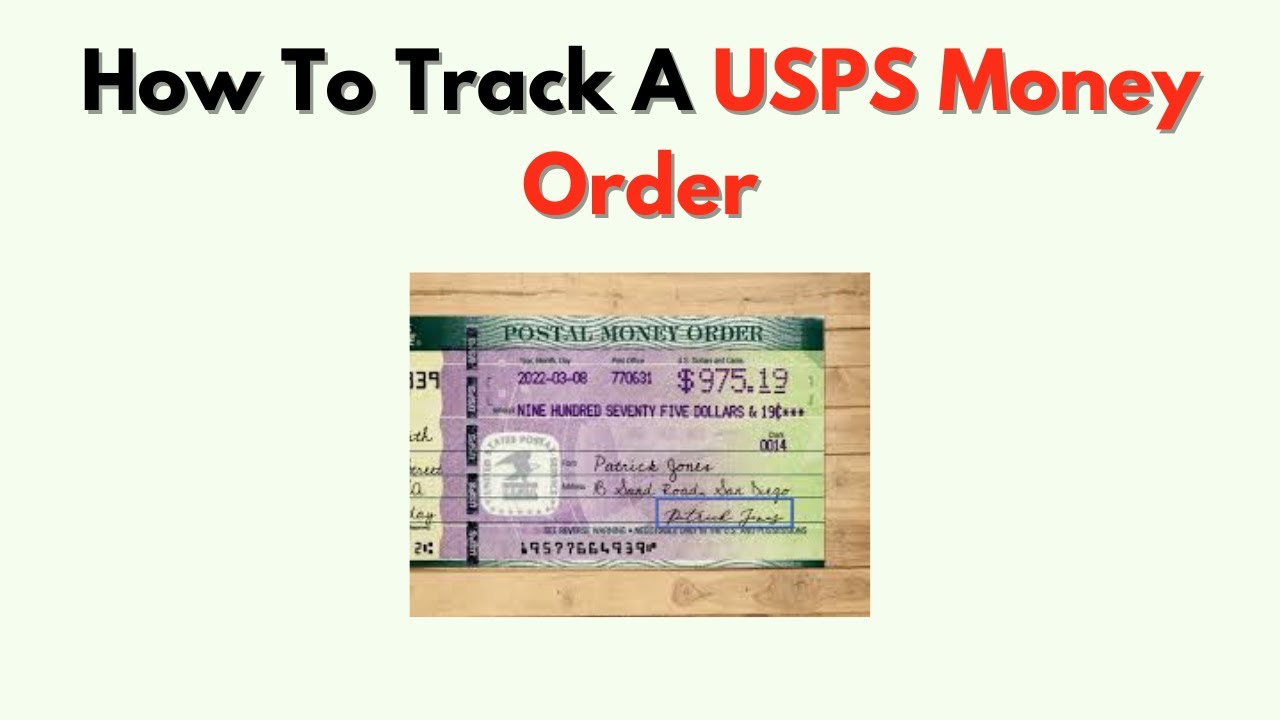
Most people waste time because they don't understand how the tracking system actually functions underneath the surface. It's not a fully real-time tracking network like you get with a package. A money order number just sits in a database until someone cashes it or returns it. That means the tracking portal often shows the same status for days. The trick is knowing what each status really means and not panicking when nothing changes.Go to the USPS website and find the money order tracking page. You'll need the 19-digit control number from your receipt. Enter it exactly as printed. No spaces, no dashes unless you're typing them yourself. Hit track. The system will show you the current status: issued, delivered to financial institution, cashed, or voided. That's it. Simple interface, simple process. Here's what happens after you submit that control number. The system checks against several databases. It can see whether the money order has been presented for payment at any location nationwide. Sometimes it takes up to 48 hours for a cashed money order to show up in the system. I learned this the hard way during tax season a few years back. I sent someone a $750 money order on a Thursday afternoon. They told me they cashed it Friday morning. I checked the tracking Saturday and it still showed "issued." I almost panicked and started filing a claim. Monday morning it flipped to "cashed" like nothing happened. That's normal. Don't chase statuses that won't move. There are two things people consistently mess up. First, they track the wrong number. The control number on your receipt is not the same as the money order serial number. The control number is what you enter into the tracking system. The serial number is printed on the actual money order itself. Use the control number, and it will start with a long string of digits. If you type the serial number by mistake, the system either returns nothing or gives you garbage data.
The second mistake is assuming the tracking status tells you the whole story. When a money order shows "delivered to financial institution," that doesn't mean it was cashed. It means it was physically deposited or presented somewhere. The funds might still be pending. The recipient could have turned around and deposited it into their own account, where it now sits in processing. I've had clients call me upset because their tracking showed delivery but the person on the other end swore they never received the money. Usually the money order was deposited on a Friday and cleared over the weekend. The recipient didn't realize there was a processing gap. By the time they checked their own bank statement, it was already resolved.
When Tracking Isn't Enough
Sometimes the system goes dark entirely. This happens more often than you'd think. A money order can show "issued" for weeks and then suddenly update to "cashed" with no intermediate steps. There's no granular timeline the way you'd get with a package shipment. You won't see a scan at a specific post office or a specific branch. All you get is the end result. I dealt with a case last year where a client needed to prove exactly when a money order was cashed for a legal matter. The tracking portal only showed the cashed date. It didn't give us the time, the location, or the teller's name. We ended up having to request a copy of the actual money order image from USPS through a formal records request. That process took about three weeks and required filling out a specific form. The form is available on the USPS website under the money order section. It asks for your contact info, the control number, and a statement of purpose. They'll send you a scanned copy of the front and back of the money order with the casher's signature on the back. That's the most detailed record you can get. Another edge case involves money orders issued before 2014. The older ones aren't always in the same digital system. If you're tracking a control number from roughly a decade ago and the system won't recognize it, don't assume it's invalid. Some older money orders exist in legacy databases that don't interface cleanly with the current tracking tool. In those situations, you need to call the USPS money order customer service line directly. Have your receipt and the control number ready. The representative can look it up manually and will sometimes provide more detail than the automated system will.
Get the Full Details

Voiding a Money Order
If you make a mistake and need to cancel a money order, you can't just destroy it and move on. The paper itself is still valid until it's formally voided in the system. I've seen this play out badly multiple times. Someone tears up a money order they filled out wrong, assumes it's useless, and then a few weeks later they discover someone found the pieces or the original was never properly destroyed. The tracking system would have shown "voided" if they'd followed the proper procedure. To void a USPS money order, you have to take it back to the counter where it was purchased or to any post office with a money order desk. Bring your receipt. They'll process the void and refund you, minus a small fee. If you lost the receipt, it gets messier. You can still attempt a void through customer service, but they'll require additional verification and it may take longer. The refund amount can also be reduced if the money order has already been partially processed or flagged in some way. There's a faster workaround if you know the money order hasn't been cashed yet and you need the funds moved urgently. Instead of voiding and reissuing, which involves waiting for the refund to post and then buying a new one, you can instruct the original recipient to deposit the incorrect money order and then you send them a new one separately. This is riskier because you're trusting someone with two pieces of paper, but it's faster. Just make sure the first one gets cancelled on your end through the proper channels so you're not leaving two valid money orders floating around.
Common Pitfalls That Waste Time
People lose money order receipts constantly. Without that receipt, you have very limited options. The control number is still your best asset. Enter it into the tracking system. If it shows "issued" and hasn't been cashed, you can call customer service and ask about a replacement. They'll need to verify your identity and may require you to wait a certain period before issuing a duplicate. If the money order shows as cashed and you don't have the receipt, your options shrink significantly. You can request proof of payment from USPS, but that goes through the same records request process I mentioned earlier, and it takes time. Another issue is tracking money orders sent internationally. USPS money orders are domestic instruments. They can only be cashed at participating locations within the United States. If you're sending one overseas, the tracking system still works, but the redemption process is entirely different. The recipient needs to find a location that accepts USPS money orders internationally, which is a much smaller list than domestic locations. I had someone try to send a money order to a relative in another country who didn't realize the receiving end wasn't straightforward. The tracking showed delivered to a postal facility, but the relative couldn't cash it because the local post office didn't participate in the USPS money order redemption program. We ended up having to redirect the funds through a different channel entirely.
What the Statuses Actually Mean
Issued means the money order was purchased and entered into the system. Nothing has happened since. The clock is ticking but there's no expiration date on a USPS money order. They don't expire. However, if you hold onto one too long without tracking it, you might forget about it entirely and the paper becomes harder to place. Delivered to financial institution means the money order has been physically taken to or deposited at a bank, credit union, or post office that participates in the redemption program. It doesn't confirm the money was withdrawn. The recipient could have deposited it and not touched it. Or they could have cashed it immediately. Both scenarios produce the same tracking status. Cashed means the funds were paid out. The money left the USPS system and went to the recipient. At this point, the money order is done. No further action is needed from your end unless you're tracking it for record-keeping purposes.

Voided means the money order was cancelled before it was ever cashed. The funds should return to the original purchaser, though processing times vary. A voided money order is dead. It cannot be redeemed by anyone.
Practical Tips That Actually Help
Take a photo of every money order receipt before you hand over the cash. I know that sounds obvious, but people skip it constantly. When you're standing at the counter and the clerk prints the receipt, grab your phone and snap a picture. That saves you from scrambling to find the number later. Paper receipts fade, get lost in mail, or end up in recycling bins. Track money orders within 24 hours of sending them. Not because there's an emergency, but because it establishes a baseline. You'll know exactly when it was issued. Then when you check back a week later and it still shows "issued," you'll know that's normal. Without that baseline, every unchanged status looks like a problem. If you're sending a large amount, consider splitting it across multiple money orders. A single $5,000 money order is fine, but if something goes wrong with it, you've lost five grand. Two $2,500 money orders means you can track and verify each one independently. If one shows as cashed and the other doesn't, you know exactly which one has an issue and can act on it immediately.
Don't rely on tracking alone for high-value transactions. If you're sending a money order for more than a thousand dollars, get confirmation from the recipient that they received and cashed it. Tracking is a backup system, not a primary communication tool. I've had clients insist that a tracking status of "cashed" meant everything was fine, only to discover later that the money went to someone else's account because the payee line was filled out incorrectly. The tracking system doesn't verify who cashed the money. It only verifies that someone cashed it. Keep your records for at least two years. Money order disputes can surface well after the fact. Tax audits, legal proceedings, or simple accounting errors can all bring up questions about payments made months or even years ago. Having the control number, the tracking history, and any correspondence stored somewhere accessible will save you significant headaches down the line. Print out the tracking results and file them with the original receipt. A digital folder on your computer works too, as long as you can access it from multiple devices.