Getting a Handle on White Household Demographics Without Losing Your Mind
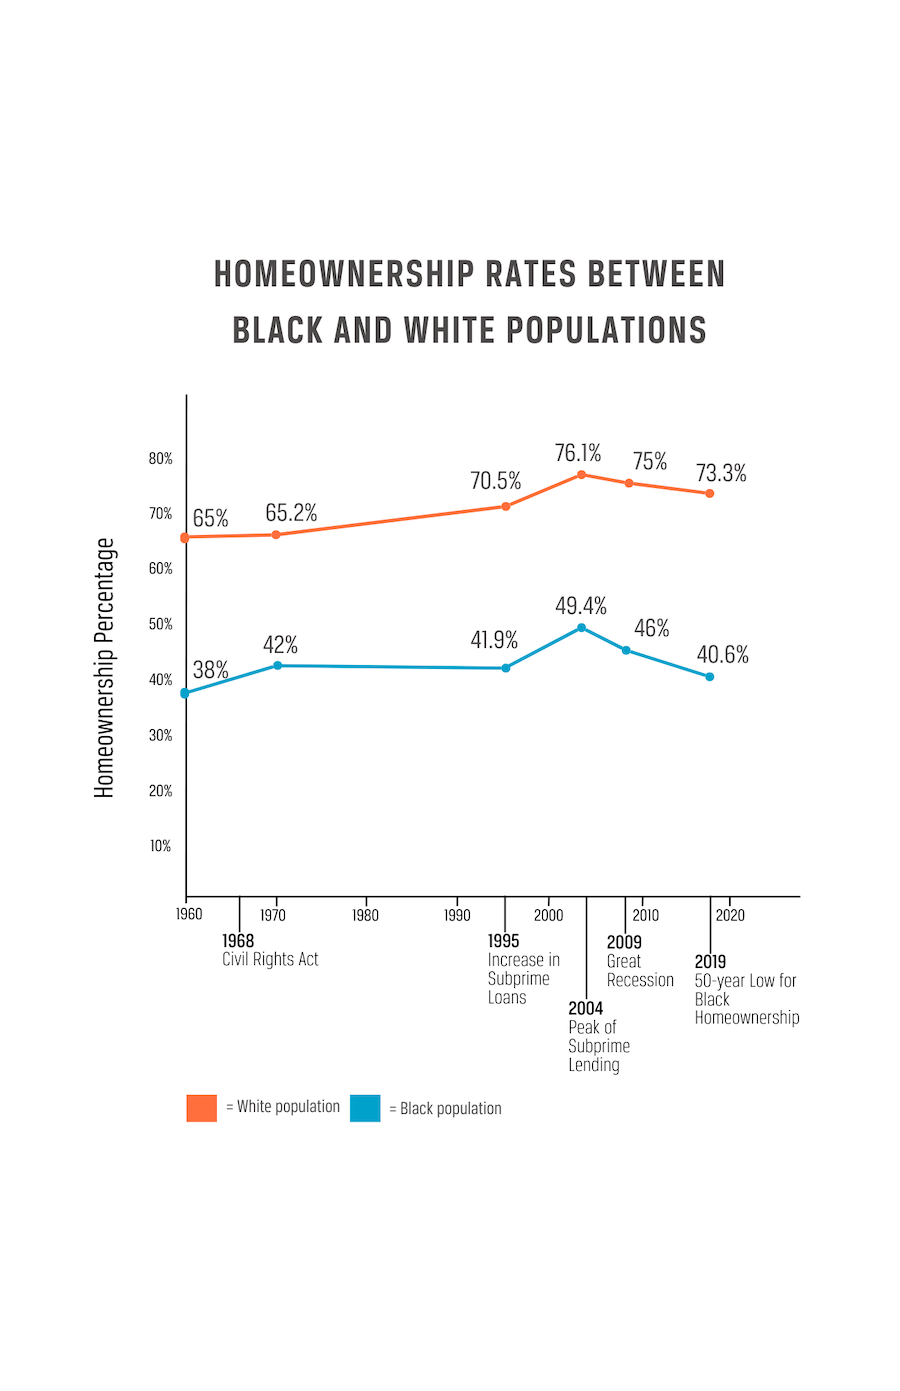
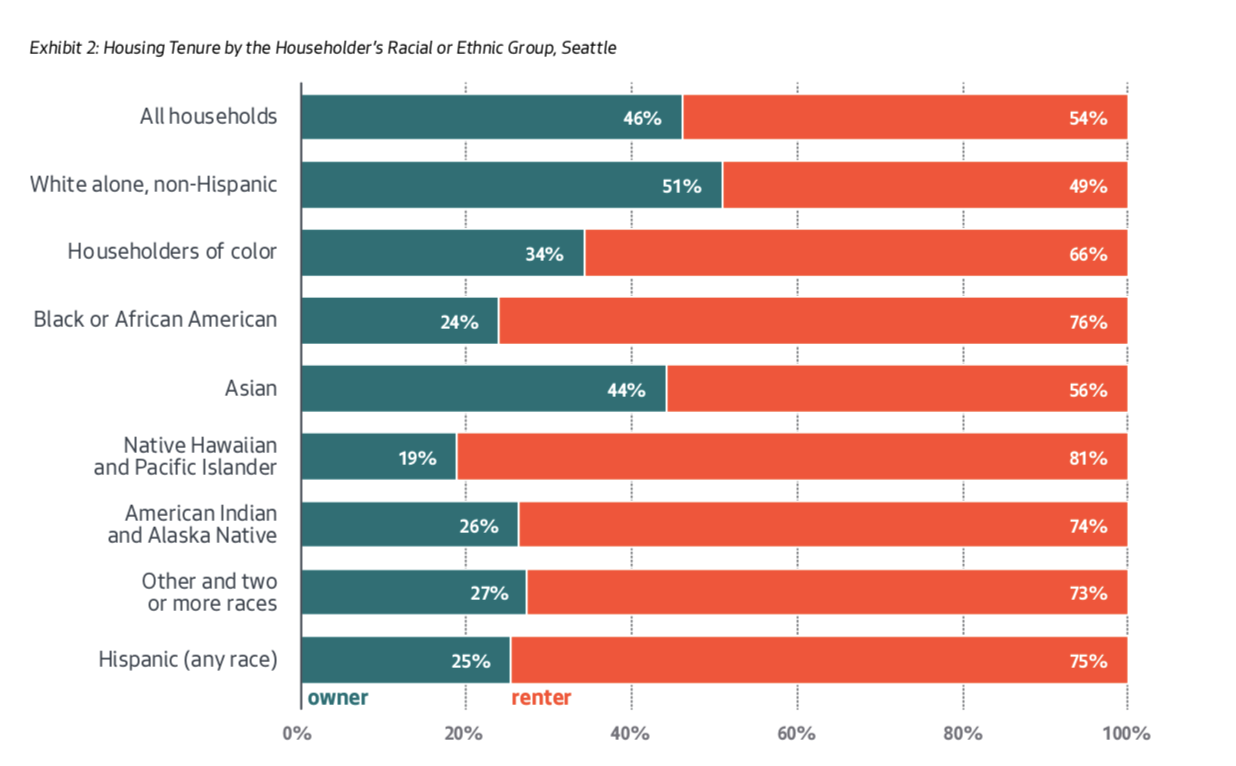
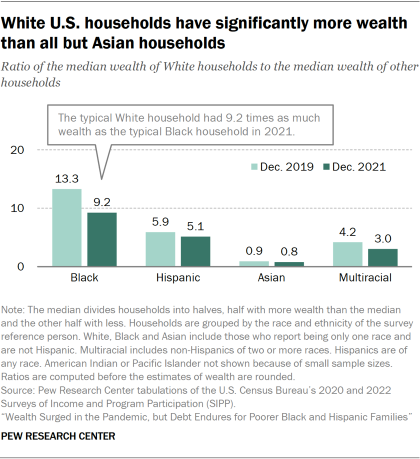
Data on white households is everywhere and almost nowhere at the same time. You'll find slices of it in Census Bureau releases, Federal Reserve surveys, and a dozen policy institutes that publish reports with titles nobody reads past the executive summary. The problem is that "white households" is not a single, clean category. It shifts depending on whether you are looking at race alone, race combined with Hispanic origin, or household type. Before you pull any numbers, you need to decide which definition your question actually requires, because mixing them up will quietly destroy your analysis. The Census Bureau's American Community Survey is where most people start. It gives annual estimates on income, wealth, housing tenure, household composition, and educational attainment broken out by race and Hispanic origin. The Federal Reserve's Survey of Consumer Finances is the other anchor, and it is the only source that gives you reliable wealth data — net worth, assets, debt — at the household level. IRS Publication 17 or state-level tax guides sometimes get dragged into this conversation too, but they are not really about demographics. They are about filing status and deduction rules, which is a completely different thing. When people say they want to understand white households, they usually mean one of three things. They want median household income trends over time. They want home ownership rates and housing cost burdens. Or they want intergenerational wealth measures. Each of these requires a different data path, and none of them are trivial to assemble cleanly.
I spent months compiling a regional breakdown once for a nonprofit that wanted to justify a new outreach program. I pulled ACS microdata, cross-tabulated by race and metropolitan statistical area, then merged it with HUD fair market rent figures. The problem was that the ACS table headers change from year to year. Table B19013 is income, yes, but the exact race categories got recoded in the 2021 release after the OMB changed how they classify Some Other Race alone. If you are pulling data across multiple years and you do not account for that recode, your series will have a phantom jump that looks like a real trend. I caught it when the 2021 figure was roughly eight percent higher than 2020 for no economic reason. The fix was straightforward: map every year's race variable back to a consistent two-category framework — White alone and White alone plus one or more other races — and reweight the microdata accordingly. It took about three days of tedious merging and validation, but it saved me from presenting garbage to a steering committee. Here is a practical workflow that actually works if you follow it consistently. Start by defining your racial category with enough precision that you can reproduce it. The default Census definition of "White" includes people who check only the White box and those who check White in combination with another race. Decide which one you need. If you are studying economic outcomes broadly, the combined definition is usually more useful because it captures a growing share of the population. If you are comparing historical series that predate 2000, stick to White alone because the combined category did not exist in the same form.
Next, pull the right table from the ACS. For income, use B19013. For poverty, use B17024. For housing, use B25070 and B25003. Download the one-year or five-year estimates depending on your geography. If you are working at the county level, use five-year estimates. One-year estimates for small counties will have margins of error so large they are essentially useless. The Federal Reserve SCF is where you go for wealth. It is triennial, which is annoying if you need annual data, but it is still the best source for net worth breakdowns. The SCF weights are complex. Do not try to calculate household-level medians without using the provided weight variables. I learned that the hard way when my first draft showed white household net worth at roughly $250,000 instead of the actual $3.5 million range. A misplaced weight variable does that to you. There are a few pitfalls that trip up everyone at least once.
Get the Full Details

The first is confusing household income with per capita income. A two-income household and a single-income household with the same total income will look very different if you normalize incorrectly. Always state clearly whether your figures are household-level or individual-level. The second is ignoring marital status. Married couple households dominate white household income statistics. If you strip them out, the median drops significantly and the picture changes entirely. It is not a trick, it is just something people forget to mention in their write-ups. A counter-intuitive point that most people miss is that white household income growth has been remarkably flat at the median over the past fifteen years when you adjust for inflation. The mean tells a different story because it gets pulled upward by high-income households. If someone cites mean income to make a point about prosperity, ask them to also show the median. The gap between the two is usually revealing. Another thing that surprises people is how much white household diversity varies by region. A white household in rural Appalachia has a completely different economic profile than a white household in the Boston suburbs. Aggregating to the national level hides that. If your work has any regional dimension, break it out early. The difference is often larger than the difference between racial groups at the state level.
If you need raw data downloads, the main entry points are data.census.gov for ACS products and frbscience.org for Federal Reserve data. The Census Data Profile tool at factfinder.census.gov used to be the go-to, but it has been retired. The new interface is slower but more flexible. State-level quick facts are available directly from the Census website and are fine for rough comparisons, though they lack the detail you need for serious work. For people who want a full reference document that walks through definitions, data sources, and common analysis mistakes, there is no single government publication that covers everything. The closest thing is the Census Bureau's own documentation on race and Hispanic origin methodology, which explains exactly how the categories are constructed and why they change. The Federal Reserve publishes a Survey of Consumer Finances Technical Documentation package that covers weighting and estimation. Between those two documents, you get the full picture of where the numbers come from. The honest limitation here is that demographic data on any racial group, including white households, cannot tell you about individual behavior or values. It describes aggregate economic outcomes. Anything that tries to infer culture, politics, or lifestyle from income and wealth tables is crossing from data into speculation. The numbers are useful for identifying disparities, tracking trends, and informing policy. They are not useful for making claims about people.
If you are building a report or presentation, the safest approach is to cite your sources explicitly, note which definition of white you used, and show both income and wealth where possible. That combination gives a complete enough picture without overstating what the data can actually support.