Getting Your Head Around French VAT
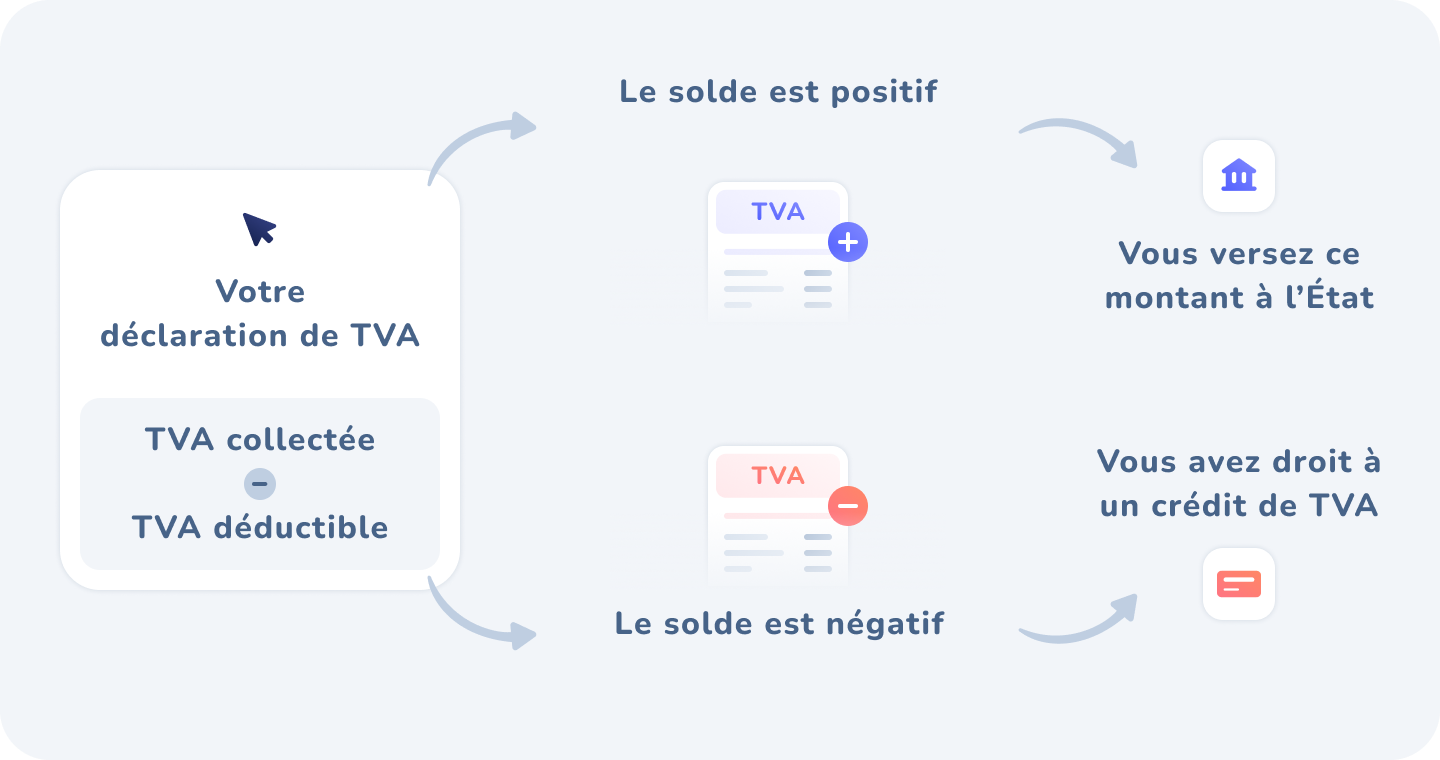
French VAT, or TVA as it's called locally, operates differently than many other European systems. The rates are layered, the compliance rules shift depending on your business structure, and the digital filing requirements catch a lot of people off guard. I've spent years dealing with this system, both for my own operations and advising others who move business between countries. The core challenge isn't really understanding what TVA is. It's navigating the practical realities of registration, collection, and filing while avoiding the penalties that come from small mistakes. The French tax authority, Direction Générale des Finances Publiques, takes compliance seriously. Missing a deadline or getting a rate wrong can cost you more in fines than you'd ever save by cutting corners.
Understanding Tva In France The Ultimate Guide To Frances Vat System For Businesses And Consumers
Let me start with how registration actually works because this is where most people hit their first wall. If you're running a business in France or selling into France from outside the EU, you need a SIRET number before anything else. The SIRET ties your company to the national registry. From there, TVA registration happens through your local centre des finances publiques. The process takes roughly 4 to 8 weeks if your paperwork is clean. I've seen it drag to 12 weeks when there are discrepancies in the initial application. The key detail most guides miss: your TVA number isn't just a standalone code. It follows a specific format. The French VAT number is your SIREN number, which is the 9-digit identifier for your business, prefixed with the country code FR. So it looks like FR plus your 9-digit SIREN. That's it. Simple, but if you get this wrong on invoices, your customers can't claim the VAT back, and you create a compliance headache for everyone involved. Here's a practical problem I ran into recently. A client of mine was importing goods from outside the EU and selling them through a French warehouse under the IOSS scheme. The goods were classified under a certain customs code, but the TVA treatment for intra-EU movement required a different declaration path. She had been filing quarterly when she should have been filing monthly. The discrepancy meant she was under-reporting her TVA liability by about 18 percent for that quarter. The fix wasn't dramatic, but it required digging into the actual customs documentation and cross-referencing it with the French nomenclature, which took me about three hours to untangle. The workaround was switching her filing to monthly and filing a corrected return for the previous period with a note explaining the reclassification. It saved her from a much larger penalty later.
The Three Standard Rates and When They Apply
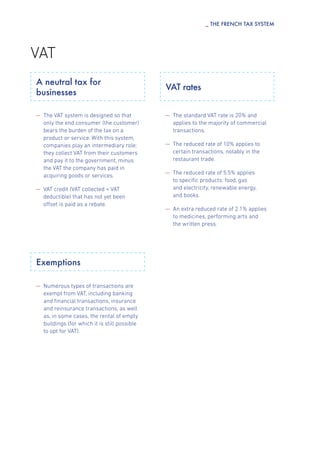
France uses a tiered VAT rate system. There are three main rates: the standard rate at 20 percent, the intermediate rate at 10 percent, and the reduced rate at 5.5 percent. There's also a super-reduced rate at 2.1 percent for specific categories like pharmaceuticals and newspapers. The standard 20 percent rate applies to most goods and services. This is what you default to unless something specifically falls under a lower bracket. The 10 percent rate covers things like restaurant services, certain cultural events, and some renovation work on residential buildings older than two years. The 5.5 percent rate is for food products, books, and energy supplies like electricity and gas. The 2.1 percent rate is narrow and mostly relevant if you're dealing with healthcare products or printed media. Here's what trips people up: the categorization isn't always obvious. A product might seem like it should qualify for a reduced rate, but the French tax code has very specific definitions. I had a situation where a client was selling specialty coffee blends and wanted to apply the reduced rate. Coffee is generally subject to the standard rate unless it meets very particular criteria around preparation and presentation. After checking the official nomenclature and consulting with a local expert, we determined the products fell under the 20 percent rate. Had we gone with the reduced rate, the back taxes and penalties would have been substantial.
Get the Full Details
How Filing Actually Works in Practice
Filing frequency depends on your annual turnover. Companies with less than 250,000 euros in annual taxable sales typically file quarterly. Above that threshold, you move to monthly filings. There's also a special regime called le forfait for very small businesses, but it's limited and comes with restrictions that make it unattractive for most serious operations. The filing platform is the site of the Direction Générale des Finances Publiques. You log in, navigate to the TVA section, and submit your declaration. It sounds straightforward. In practice, the interface isn't particularly user-friendly, and the deadlines are strict. Quarterly filings are due by the 15th of April, July, October, and January. Monthly filings follow the same pattern, with the 15th of each month being the deadline. Penalties for late payment are steep. There's a 0.4 percent penalty per month of delay on unpaid VAT, capped at 4 percent for delays up to a year. Beyond that, it jumps to 8 percent. Late filing without payment incurs a separate 10 percent penalty. These aren't theoretical risks. I've seen business owners lose significant money because they missed a single deadline by a few days. The system doesn't send gentle reminders. You get formal notices, and ignoring them escalates quickly.
Intra-EU Transactions and the Reverse Charge Mechanism
If you're buying from or selling to other EU countries, the reverse charge mechanism applies. This means the buyer accounts for the VAT instead of the seller. It's designed to simplify cross-border transactions within the EU, but it creates its own set of compliance requirements. You need to include specific references on your invoices, and you must report these transactions in the recapitulative statement, or déclaration récapitulative, which is filed monthly or quarterly depending on your volume. The recapitulative statement is one of those things that seems minor until you forget it. I once advised a company that had been handling EU sales manually without tracking the recapitulative obligation. They realized the gap after six months and had to file six months of back reports. It wasn't catastrophic, but it consumed about a week of accounting work and required reconciling invoices that had already been closed out. The lesson here is to track intra-EU transactions from day one. Set up your accounting system to flag them immediately.
Common Pitfalls and What to Watch For
One common mistake is misapplying the reduced rate. Another is missing the deadline for registering when your turnover crosses a threshold. If you're under the micro-BIC regime and then grow beyond it, you're required to switch to the standard TVA regime. The transition isn't automatic. You have to notify the tax authority and adjust your invoicing. I've seen people miss this entirely because the threshold change happened gradually over several months. Another issue is the treatment of digital services. If you're providing digital services to French consumers, you may need to register for the OSS scheme if you're outside France, or handle it domestically if you're based there. The rules changed a few years ago, and the transition period created confusion. Some businesses continued using the old rules thinking the change was temporary. It wasn't. If you're in this position, check your current status against the latest requirements and correct any lapses proactively. The system also has limitations. The French VAT framework is detailed and occasionally contradictory, especially when it comes to edge cases. The online portals can be slow and unreliable during peak filing periods. I've experienced times when the government site was down entirely during a deadline window, forcing a rushed manual submission through alternative channels. It worked, but it added stress and risk. If you're managing TVA yourself, consider having a backup plan for technical failures, like keeping your data ready in a format that can be submitted quickly through alternative methods.
Working with a Professional
For most businesses, especially those just starting or dealing with cross-border transactions, working with a comptable or VAT specialist makes sense. The cost of professional help is usually far less than the cost of errors. A good specialist will catch issues before they become problems and keep you informed about changes in the rules. I've found that the best relationships with accountants are those where you maintain transparency about your operations. Hiding details or being vague about transactions only makes their job harder and increases the risk of mistakes on your end. The French VAT system isn't impossible to navigate, but it requires attention to detail and a willingness to stay current with changes. The rules shift, the platforms update, and the enforcement practices evolve. Keeping track of these changes and maintaining accurate records is the foundation. Everything else builds on that.