Getting MPC Right When The Numbers Lie To You
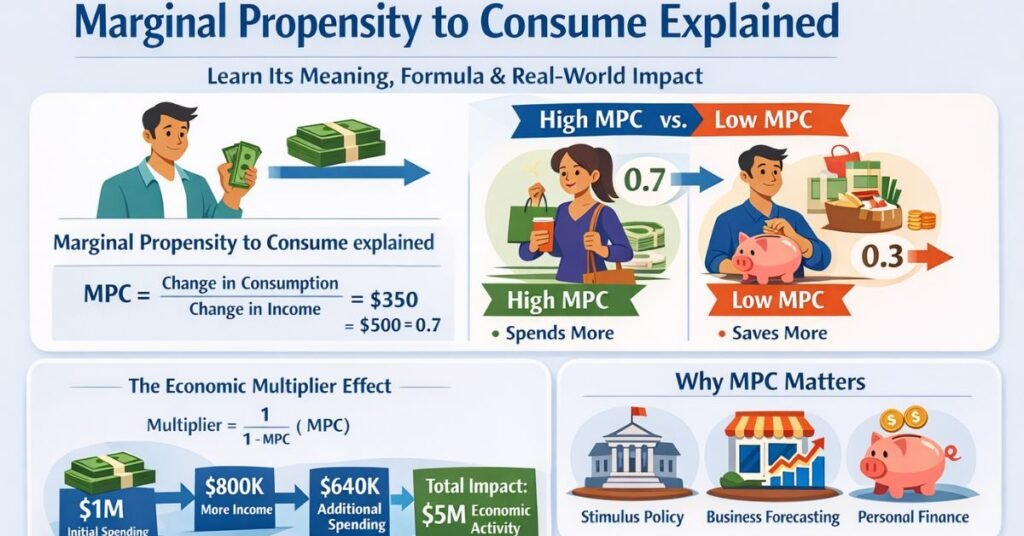
The marginal propensity to consume is supposed to be straightforward. It's the fraction of additional income that gets spent rather than saved. But anyone who has actually tried to use this in a real economic model knows that the textbook version breaks down pretty quickly once you step outside a controlled classroom problem. I spent about three years working on fiscal impact assessments for state-level tax policy, and MPC was one of those concepts that looked clean on paper and was genuinely messy in practice. The basic formula is MPC equals change in consumption divided by change in disposable income. That part is elementary. Where people get tripped up is in deciding what counts as a change in income and what actually constitutes consumption in the data you have available. If you're using survey data, which most of us do at some level, the numbers come with noise. People misreport spending. They forget the small purchases. They conflate one-time windfalls with regular income changes. I ran into a specific problem a few years back when I was modeling the effect of a temporary property tax rebate on local consumer spending. The rebate was structured as a one-time payment, roughly twelve hundred dollars per household on average. The textbook MPC for temporary income is lower than for permanent income, but the difference matters more than most policy briefs admit. I had initial estimates suggesting an MPC of about zero point six, which would imply most of that rebate went straight into spending. When I disaggregated the data by income quartile, the picture changed dramatically. Lower-income households showed an MPC near zero point nine, while upper-quartile households barely spent anything beyond their normal patterns. The aggregate number I'd been using was masking the distribution entirely.
The workaround wasn't particularly elegant. I had to reweight the consumption responses by income distribution and then run a simulated multiplier effect that accounted for the fact that lower-income spending tends to circulate through the local economy more intensively because those dollars go toward necessities and locally services rather than savings or out-of-state purchases. The final estimate ended up about fourteen percent lower than the naive aggregate calculation. That fourteen percent gap mattered because it determined whether a program passed or failed its cost-benefit threshold. Another thing that trips people up is the distinction between short-run and long-run MPC. Most empirical estimates you find in journals are pulled from short-term experiments or natural disasters where income changes happen abruptly. Those estimates tend to be higher because people haven't adjusted their expectations yet. When the income change is perceived as permanent, MPC drops. The permanent income hypothesis isn't just some academic footnote, it's the reason why stimulus checks during the pandemic produced spending spikes that faded faster than models predicted. There's also the timing problem. MPC isn't a single number you apply and move on from. Consumption responds over quarters, and the response curve isn't linear. People tend to front-load spending on durable goods when they get unexpected income, then settle back to baseline patterns. If you're building a model that assumes a uniform spending rate across time periods, your multiplier effects will be mis-timed and likely overstated in the first year.
The most useful practical approach I found was to build a range rather than a point estimate. Pick a low scenario, a medium scenario, and a high scenario based on the population characteristics you're working with. Low-end MPC around zero point four to zero point five for mixed-income urban populations receiving permanent income changes. Medium around zero point five five to zero point sixty-five for temporary measures in moderate-income brackets. High end around zero point seven to zero point eight when you're looking at low-income populations with credit constraints. Those aren't arbitrary ranges. They're backed by a decent amount of micro-level research, though the exact numbers vary by country and by the type of income change. The biggest limitation of MPC analysis is that it doesn't capture substitution effects. If you give people more income and they spend it on imported goods, the local multiplier collapses. If they pay down debt instead, the short-run boost disappears entirely. I've seen models produce optimistic projections that fell apart because they assumed consumption would stay within a certain geographic boundary. It doesn't. Modern consumers don't respect those boundaries. If you're doing this for actual policy work rather than academic exercises, I'd recommend pairing MPC analysis with household balance sheet data when available. The debt-to-income ratio of the population you're targeting tells you a lot about whether an income increase will translate into spending or debt service. A household drowning in high-interest credit card debt will have a very different consumption response to the same rebate than a household with healthy savings and manageable debt. That difference doesn't show up in aggregate MPC numbers.
Get the Full Details

There's also the issue of expectation formation. People adjust their spending based on what they think will happen next, not just what happened today. If someone receives a one-time bonus and believes future taxes will be raised to pay for it, they'll save more of it than the MPC suggests. This forward-looking behavior is hard to model with any precision but it consistently shows up in the data. I learned to build in a discount factor of roughly ten to fifteen percent when the policy environment was uncertain, which brought my models closer to actual outcomes over time. Data sources worth knowing include the Survey of Consumer Finances for wealth and debt distribution, the Panel Study of Income Dynamics for longitudinal consumption responses, and the Federal Reserve's payment behavior studies which have shown interesting patterns about how different income groups handle windfalls. None of these sources alone gives you the full picture, but together they let you triangulate something closer to reality. The multiplier effect derived from MPC is where most policy discussions live or die. An MPC of zero point six implies a simple spending multiplier of two point five. That sounds compelling until you account for leakages through savings, taxes, and imports, which typically cut the effective multiplier to somewhere between one point two and one point eight in real-world conditions. The gap between the theoretical multiplier and the empirically observed one is where policy mistakes get made.
I wish I could say there's a clean rule of thumb for adjusting the simple multiplier downward, but it depends heavily on the economic context. Open economies with high import penetration see larger reductions. Economies with progressive tax systems see automatic dampening as income rises. The recession or expansion phase the economy is in matters too. During downturns, MPC tends to be higher because marginal utility of consumption is greater when people are financially stressed. The bottom line is that MPC is a real concept with real predictive power, but treating it like a constant is a reliable way to make bad decisions. It's a range, it's contextual, it shifts over time, and it varies across population segments. The people who get it right are the ones who treat their initial estimate as a starting point rather than an answer.