Quebec Runs Two Sales Taxes, and They Overlap in Ways That Confuse Almost Everyone
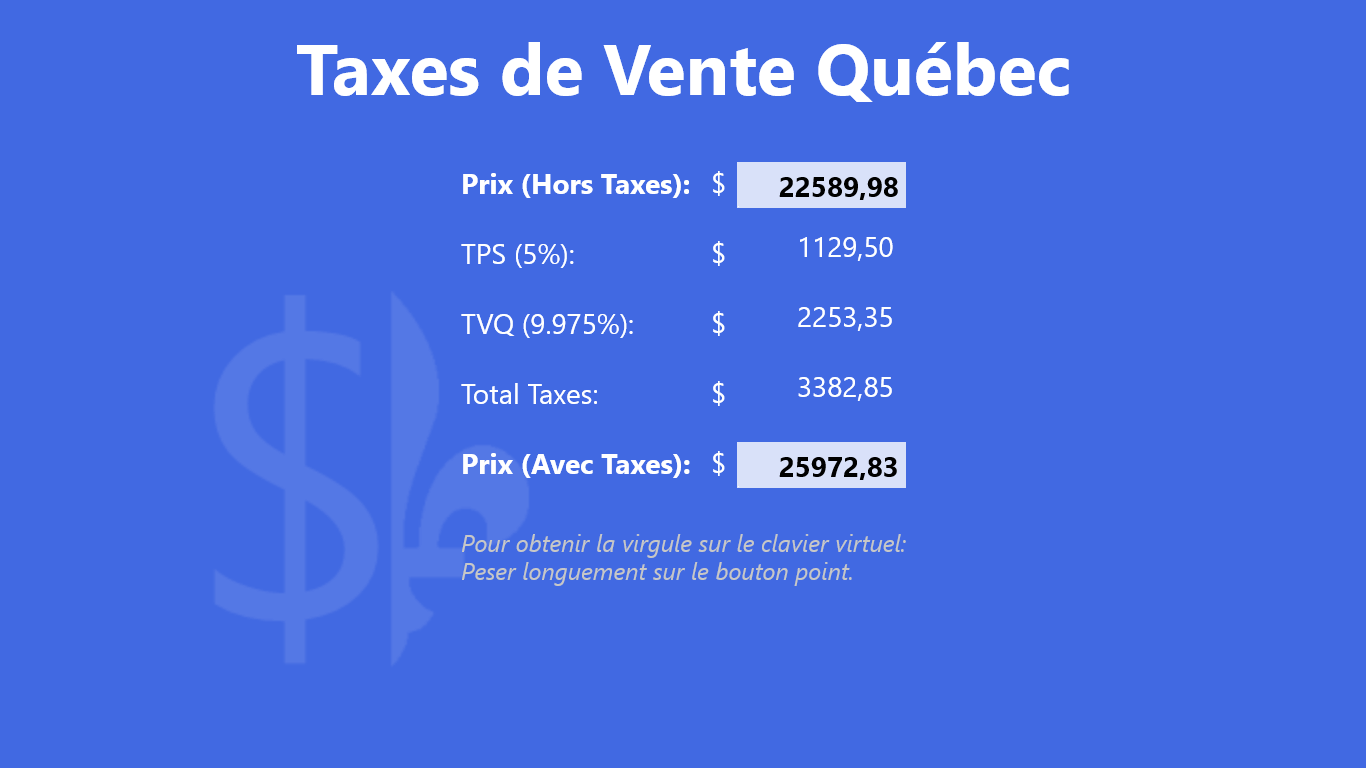
The first thing most people get wrong about Quebec's tax system is assuming the QST and GST are independent. They are not. You calculate them separately, you report them separately, but they hit the same sale price and they interact in ways that cost people money if you don't understand the mechanism. I have seen contractors under-collect QST on digital services by treating the GST as part of the tax base instead of before it. It happens constantly in small business filings. TVA is just the French abbreviation for the same thing. It stands for Taxe sur la valeur ajoutée, which is Quebec's terminology for sales tax. When you see TVA on an invoice in Montreal, it means you are looking at either the GST, the QST, or both combined depending on the context. The Canada Revenue Agency handles the federal portion. Revenu Québec handles the provincial portion. They do not share a single filing system. That is the first structural detail you need to carry with you. Here is how the actual calculation works in practice. When you sell a product or service in Quebec that is subject to both taxes, the GST is applied first to the selling price. Then the QST is applied to the selling price plus the GST amount. So a $100 item does not become $112. It becomes $100 plus $5 GST equals $105, plus $7.4975 QST, which rounds to $7.50. Your total tax collected is $12.50 on a $100 sale. The effective combined rate is 12.5%, but the math behind that number is not a flat 12.5% multiplied against the base. It is two sequential calculations. Most people miss this distinction when they build automated invoicing tools.
I built an internal calculator for a client last year that was applying both taxes directly to the base price. It was off by roughly $0.03 per $100 transaction. On a business doing $2 million in annual sales, that was a $600 discrepancy per quarter. Revenu Québec did not care about the rounding nuance. They cared that the QST remittance was wrong. The fix was straightforward but tedious. I rewrote the formula to layer the GST onto the base, then applied the QST to the layered total. Then I added a quarterly reconciliation script that flagged any variance above $0.50. That saved us from an audit note that would have been entirely unnecessary.
Who Actually Has to Register
Registration is mandatory if your taxable supplies exceed $30,000 in four consecutive calendar quarters. That is the threshold for both GST and QST, though you register with two different agencies. If you are a non-resident selling digital services to Quebec residents, the rules changed recently and you may need to register for QST even below the $30,000 mark depending on the service category. The CRA gateway for non-resident GST registration does not cover this. You have to go directly to Revenu Québec's portal and create a separate account. Goods and services tax currently sits at 5% federally. Quebec's quebec sales tax sits at 9.975% for most retail transactions, but the rate drops to 3.75% for certain categories like restaurant meals and catering. Pharmaceutical products are QST-exempt at the standard rate but still carry GST. Food essentials are exempt from both taxes in most cases, though prepared foods are not. The line between exempt and taxable is where most mistakes happen. A bakery selling bread is exempt. A bakery selling a slice of cake at a counter is not. The product is the same category but the tax treatment changes based on how it is served.
Get the Full Details

The Input Tax Credit System
When you are registered, you can recover the GST and QST you paid on business expenses through input tax credits. This is the mechanism that prevents double taxation on business-to-business transactions. You claim credits on your GST return with the CRA and on your QST return with Revenu Québec. They are separate forms, separate portals, separate deadlines. Here is a detail that does not get enough attention. If you make both taxable and exempt sales, your ability to claim input tax credits is prorated. You cannot claim the full credit on expenses related to exempt activities. The formula is your total taxable supplies divided by your total supplies, all sales inclusive of tax. So if 60% of your revenue comes from taxable sales and 40% comes from exempt sales, you can only claim 60% of your input tax credits on most expenses. Some expenses are fully attributable to one category or the other and do not get prorated. Understanding which is which requires keeping detailed purchase records. Receipts alone will not cut it. You need to note whether each purchase was for taxable activity, exempt activity, or both. I learned this the hard way in 2023. A consulting firm client had been claiming full QST credits on office expenses even though roughly a third of their projects were for government entities that made their services exempt. The proration rate was around 67%. They had overclaimed by approximately $4,200 over two years. Revenu Québec caught it on a random review. The penalty was modest because it was not intentional, but it was entirely avoidable. After that, I set up a quarterly expense tagging system that forced categorization before any credit claim was submitted. It added about 20 minutes per week to their bookkeeping cycle but eliminated the risk permanently.
Filing Deadlines and Penalties
Most small businesses file monthly. If your annual taxable sales are under a certain level, you can file quarterly, but the default expectation from both agencies is monthly compliance. The CRA deadline for GST returns is the last day of the month following the reporting period. Revenu Québec has the same schedule for QST returns. Missing a deadline triggers a $25 penalty plus 1% of the balance owing for the first offense, then 1% for each additional month it remains unpaid up to six months. Interest accrues daily on any outstanding balance from the due date. There is no single combined return for GST and QST in Quebec unlike some other provinces. You file form GST-34 with the CRA and form TP-1050.V with Revenu Québec. They are completely independent. Some accounting software attempts to sync them but the data formats and reporting requirements differ enough that blind automation produces errors. I have reviewed enough mismatched exports to know that manual verification of at least one complete filing cycle is worth the time before you trust any automated pipeline.
Common Pitfalls That Cost People Money
The first mistake is forgetting to charge QST on interprovincial sales where the customer is in Quebec. If you are registered in Ontario and sell to a Quebec resident, you may still owe QST depending on the product type. The place of supply rules determine this, not your registration province. The second mistake is mixing up the reverse charge mechanism. For certain services received from outside Canada, you owe the tax yourself rather than collecting it from a customer. This applies to software subscriptions, cloud services, and professional fees from foreign providers. You calculate and remit both the GST and QST portions directly. The third and most expensive mistake is ignoring the reciprocal credit agreement between Quebec and Ontario. Quebec and Ontario have an agreement where QST paid on goods imported from Ontario can be credited against GST payable, and vice versa. This matters if you move inventory between provinces regularly. Without claiming these credits, you are essentially paying tax on tax. I found a distributor in Laval who had overlooked this for three years. The recovered amount was approximately $18,000 when they finally ran the numbers correctly. It was not a loophole. It was a standard provision that nobody on their team understood.

What the System Fails At
The biggest structural weakness in Quebec's current tax framework is the inconsistency in how digital services are taxed across borders. The rules changed multiple times between 2021 and 2024, and the guidance from Revenu Québec on edge cases remains contradictory in places. If you sell subscription software from Quebec to customers in both Ontario and Alberta, the QST rules, the GST rules, and the provincial tax nexus rules do not align cleanly. You end up doing manual calculations instead of relying on automation. No major accounting platform handles this perfectly yet. They approximate. Approximations are fine until an auditor asks for the underlying logic. Another limitation is the lack of a unified portal. Having separate accounts for CRA and Revenu Québec means duplicate data entry, separate password resets, two sets of notices, and two different audit trails. It is not technically difficult but it is genuinely inefficient. The Quebec government has discussed consolidation for years. Nothing has materialized. If you run a business across multiple provinces, the administrative overhead compounds quickly. You are better off using a dedicated tax compliance service if your multi-province revenue exceeds $500,000 annually. The cost of the service pays for itself in reduced error rates within the first year.