Why Your Fiscal Calendar Is Confusing Everyone (Including You)
Quarter ends are supposed to be straightforward. They aren't. I spent three years reconciling mismatched fiscal quarters across different departments before I actually understood what was going wrong. The problem isn't the calendar itself. It's the assumptions people bring to it. When someone says "Q1 revenue," they usually mean January through March. But in retail, Q1 often ends in late February or even early January. In tech, some companies use a fiscal year that doesn't start in January at all. If you've ever looked at a report and thought the numbers didn't add up, this is probably why.
Understanding Q1 Q2 Q3 Q4 In Business A Simple Guide
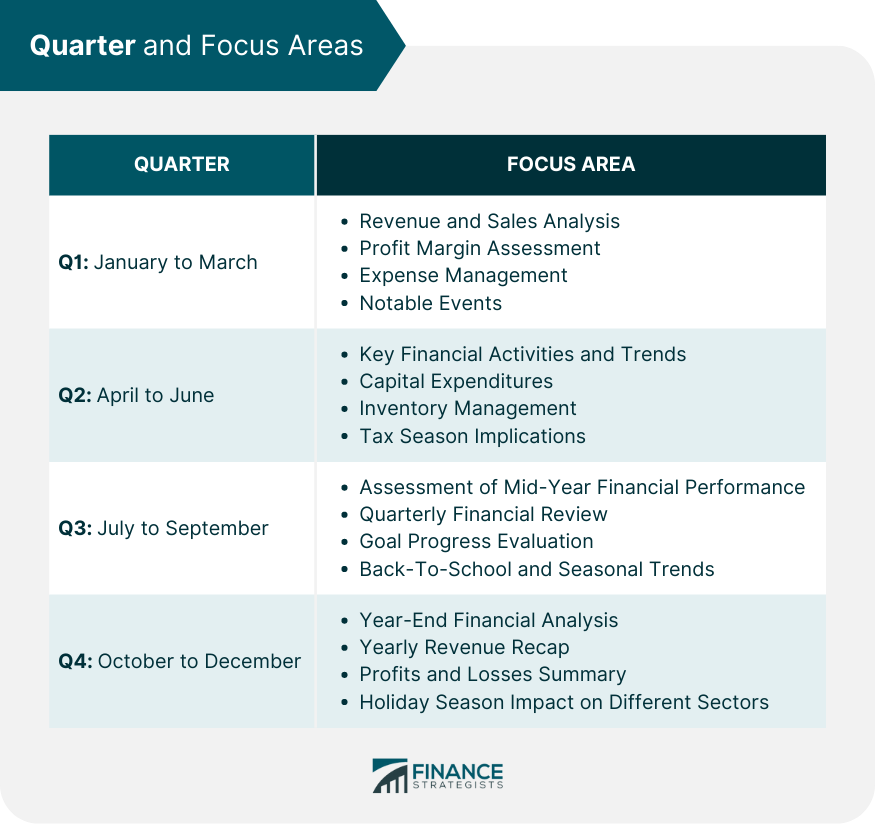
Business quarters divide a fiscal year into four approximately equal periods. Each quarter is roughly 90 days, though the exact split varies by company. The standard breakdown most people learn is Q1 (months 1-3), Q2 (months 4-6), Q3 (months 7-9), and Q4 (months 10-12). That's the baseline. It's not the full picture. The first thing you need to know before doing anything else: always check which fiscal calendar a company uses before comparing quarter data between two organizations. I learned this the hard way when I was pulling competitor analysis for a board deck. Two companies reported identical Q3 revenue figures, but one's Q3 ended September 30th while the other's ended October 31st. The comparison was garbage from the start. Took me six hours to fix after the meeting.
How Quarters Actually Work in Practice
Let me walk through the mechanics without the corporate brochure version. A business quarter is a reporting period. Companies track revenue, expenses, headcount changes, and operational metrics within each quarter. The purpose is to create manageable chunks of time for evaluation rather than trying to assess a full year at once or getting lost in daily fluctuations. Here's what most guides don't tell you: quarterly data is almost always backfilled or revised. The first "Q1 report" you see in April is rarely the final version. Actuals get adjusted as invoices clear, accruals get recorded, and estimates get corrected. I've seen Q2 numbers shift by 8-12% between the initial report and the audited final version. If you're making decisions based on unaudited quarterly figures, build in a margin of error or wait for the revised data. The workflow most companies follow goes like this. Month-end close happens first, usually within 5-10 business days after the month ends. That produces monthly actuals. Quarterly close aggregates those monthly numbers and adds quarterly-specific adjustments like depreciation, audit accruals, and intercompany eliminations. The quarterly report is what stakeholders actually see. It's the sum of three monthly closes plus the quarterly clean-up work.
Get the Full Details

Common Pitfalls That Break Quarterly Analysis
I've seen this repeatedly across different industries. People compare quarter-over-quarter growth without adjusting for seasonality. A retail company might show 40% growth from Q3 to Q4 and claim it's a success. But Q4 always includes holiday sales. Comparing Q3 to Q4 is comparing apples to something completely different. The meaningful comparison is Q4 this year versus Q4 last year, not Q3 versus Q4 within the same year. Another trap is ignoring the cutoff date difference between fiscal and calendar quarters. Some companies, especially in Europe and Asia, use a fiscal year starting in April or October. When you're looking at multinational data, Q1 for Company A might be January-March while Q1 for Company B is April-June. Mixing these in a spreadsheet without flags creates false conclusions. I built a simple color-coding system into our reports: blue tags for fiscal Qs, green for calendar Qs. Takes two minutes to set up and saves hours of confusion later. The third pitfall is treating quarterly metrics as more precise than they are. Gross revenue for a quarter is a snapshot that depends entirely on when contracts were signed, when shipments occurred, and when revenue recognition rules apply. A software company might recognize annual subscription revenue upfront or ratably over twelve months. Two companies with the same Q1 revenue number could have completely different cash flows and contractual obligations behind them. Always look at the revenue recognition policy footnote before drawing conclusions from quarterly tops lines.
Working Around Quarter-End Close Delays
Quarter-end close is where things get messy in practice. Here's a realistic scenario I deal with constantly: the sales team closes a large deal on the last business day of the quarter. The paperwork isn't complete. The finance team needs it to book revenue in that quarter, but legal hasn't countersigned. This happens more often than you'd think, especially in B2B environments where contract cycles drag. The workaround I use is a simple pre-close checklist. Thirty days before quarter end, flag any deals above a certain threshold that haven't hit a committed close date. Twenty days out, require status updates from sales. Ten days out, escalate anything still unresolved to the controller. This doesn't eliminate the problem but it surfaces it early enough that you can plan around it instead of scrambling at the last minute. Another practical issue is the "window dressing" problem. Sales teams sometimes push deals through at quarter end that wouldn't have closed otherwise, just to make the numbers look better. I've seen this create real downstream problems when those deals got returned or renegotiated the following month. The fix is straightforward: track win rates and return rates by quarter, and flag quarters where Q4 returns significantly exceed the average. It's a small metric that reveals a lot about whether the numbers are honest.
When Quarterly Analysis Fails Completely
Let me be direct about the limitations. Quarterly analysis breaks down in three specific scenarios. First, for early-stage companies with less than eighteen months of history. You don't have enough data points to identify patterns. Monthly or even weekly tracking is more useful at that stage. Second, for businesses with highly irregular revenue streams where quarter boundaries are arbitrary. Consulting firms, project-based construction companies, and entertainment production businesses often have revenue that clusters around project milestones rather than calendar periods. Forcing their data into quarterly buckets obscures the actual business rhythm. Third, during structural transitions. Mergers, acquisitions, product launches, or major pivots make quarter-over-quarter comparisons nearly meaningless because the underlying business has changed. In those cases, the alternative is to switch to trailing twelve-month rolling periods or to define custom reporting windows that align with your actual business cycle. I stopped using traditional quarterly breakdowns for our consulting division entirely. We switched to a "project completion cycle" metric that tracks from kickoff to close regardless of calendar quarters. The numbers became immediately more useful for decision-making.
Practical Steps to Use Quarterly Data Correctly
Start with the basics and build from there. Document your fiscal quarter definitions explicitly in any report you produce. Don't assume anyone reading it knows whether Q2 ends June 30th or July 15th. Include a footnote or a small table mapping each quarter to its exact date range. This single step eliminates roughly half the miscommunication I encounter. Always present both absolute numbers and percentage changes. A company reporting "Q2 revenue of 12.4 million" tells you nothing without context. Is that up or down from Q1? Up or down from last year's Q2? What's the trend across four quarters? Layer in year-over-year comparisons alongside quarter-over-quarter to separate seasonal effects from actual growth. Watch for the compounding effect of small quarterly errors. A 2% miss every quarter compounds to roughly an 8% annual gap if uncorrected. I caught a discrepancy this large once by running a simple cumulative variance check: sum of quarterly variances versus the annual variance. When they diverged by more than a few percentage points, something was double-counted or missed. It took us a week to find the root cause, but the check itself takes about five minutes per quarter once you have the data structured correctly.
Use the right tools for aggregation. Spreadsheets work fine for a handful of quarters. Beyond that, you're inviting errors and wasting time. Even a basic database or a proper BI tool cuts aggregation time from hours to minutes and makes cross-quarter comparisons reliable. I've migrated several teams from Excel to lightweight dashboarding solutions, and the improvement in data integrity was immediate. The learning curve is real but short, and the payoff shows up in the first month of use. The bottom line is that quarterly reporting is a tool, not a truth. It gives you structure to evaluate performance, but the structure itself requires careful handling. Know your fiscal calendar, account for revisions, compare apples to apples, and recognize when the quarterly framework doesn't fit your business. Those four habits will put you ahead of most people who treat Q1 through Q4 as just another spreadsheet exercise.