The Practical Side of Low Gearing
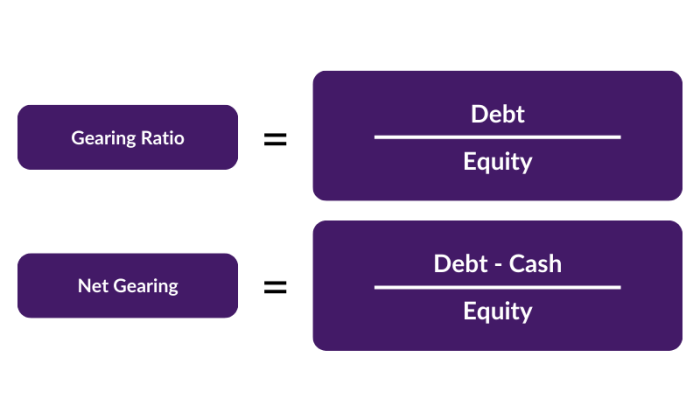
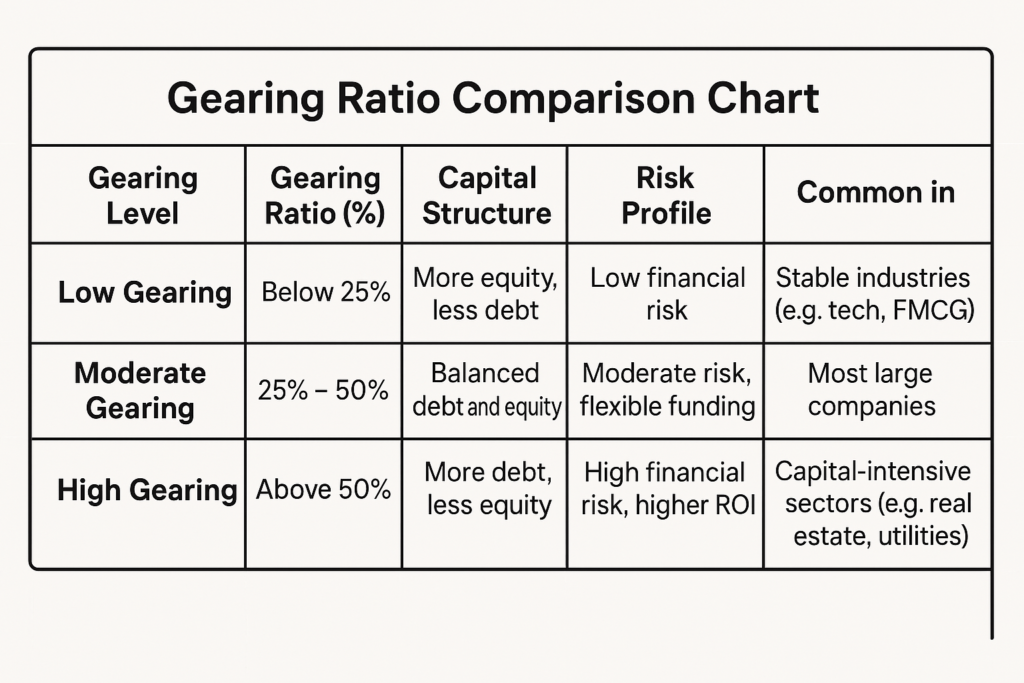
When a company carries very little debt relative to its equity, it is considered to have low gearing. The concept sounds straightforward, but the implications ripple through credit ratings, cost of capital, and strategic flexibility in ways most beginners gloss over. I spent years reviewing corporate balance sheets across manufacturing, real estate, and tech sectors, and the companies that consistently outperform aren't necessarily the ones with the highest returns on equity. Often, they are the ones that chose to keep their leverage restrained and let compound growth do the heavy lifting instead. Low gearing simply means a firm finances most of its operations through shareholder equity rather than borrowed capital. The standard metric people use is the debt-to-equity ratio. A ratio below 0.5 is generally classified as low gearing, though the exact threshold shifts depending on the industry. A utility company with a ratio of 0.8 might be considered conservatively geared, while a software firm at the same level could be viewed as heavily leveraged. Context matters more than the raw number. The calculation itself is uncomplicated. Total liabilities divided by total shareholders' equity gives you the ratio. Some analysts prefer the debt-to-capital formulation, which plugs total debt into the denominator alongside equity. Both approaches yield the same directional signal. What changes is the precision of the comparison when you are evaluating firms with different capital structures.
How It Works in Practice
A low-gear company faces minimal interest obligations each quarter. That absence of mandatory debt service creates operational breathing room during downturns. When revenue contracts, an highly geared firm gets squeezed by fixed payments regardless of performance. A low-gear firm can weather the same shock with fewer immediate consequences. This is not a theoretical advantage. I saw it firsthand during the 2022 interest rate environment when borrowing costs spiked across commercial real estate. Companies that had maintained debt-to-equity ratios under 0.4 refinanced their term loans without covenant breaches or distress discounts. Their higher-leveraged peers did not have that option. The trade-off is that low gearing typically produces lower returns on equity. Equity amplifies gains when borrowing is cheap, and it amplifies losses when conditions deteriorate. With minimal debt, the amplification effect weakens in both directions. A company growing organically at twelve percent per year with no leverage will often lag behind a competitor using borrowed money to accelerate expansion. The question is whether the acceleration survives cyclicality.
A Specific Problem I Encountered
During a due diligence process for a mid-market acquisition, I came across a company that reported a debt-to-equity ratio of 0.32. On the surface, this looked like textbook low gearing. The problem was hidden in the off-balance-sheet operating leases and a substantial pension deficit. When I adjusted the leverage calculation to include those items, the true ratio jumped to 0.89. The original financial statements made the company appear far more conservatively financed than it actually was. I resolved this by requesting the full lease schedule and the actuarial valuation of the pension obligation, then recalculating the ratio using the adjusted figure. The adjusted gearing changed our valuation model significantly and affected the purchase price by roughly eight percent. The first mistake is treating the debt-to-equity ratio as a standalone signal. It tells you nothing about the cost of that debt, the maturity profile, or whether the borrowing is denominated in a stable currency. A company with a low ratio but short-term floating-rate debt in an emerging market currency faces different risks than one with long-term fixed-rate debt in a strong currency. Always examine the composition of liabilities, not just the aggregate number. The second mistake is assuming low gearing is universally optimal. There are industries where capital intensity demands higher leverage for efficient operations. Banks, insurers, and infrastructure operators naturally carry elevated debt levels because their business models are built around managing financial intermediation. Applying a universal low-gearing benchmark across these sectors produces misleading conclusions about financial health.
Get the Full Details
When Low Gearing Fails You
Low gearing becomes a liability when a company lacks profitable investment opportunities but continues hoarding equity capital. Excess unproductive cash drags down returns on invested capital. I worked with a consumer goods manufacturer that maintained a debt-to-equity ratio of 0.2 for nearly a decade because the leadership feared any form of borrowing. The company generated strong free cash flow but could not find acquisitions or organic projects that exceeded its cost of capital. Shareholders who demanded a return premium ended up earning less than they would have if the firm had taken on moderate debt to finance targeted expansion. The firm eventually raised leverage to 0.6 after a change in management, which improved return on equity from seven percent to eleven percent over two years. Another scenario where low gearing breaks down is during periods of genuinely cheap capital. When bond yields sit at historically low levels and lenders compete aggressively for quality borrowers, keeping leverage minimal means leaving money on the table. A moderately geared company that borrows at five percent to acquire assets yielding twelve percent creates substantial shareholder value. A low-gear company that refuses to borrow misses that spread entirely.
A Practical Framework for Evaluation
Start with the debt-to-equity ratio and compare it against industry medians, not absolute thresholds. Then examine interest coverage ratios to assess whether existing debt is manageable even if the total amount appears low. Next, review the maturity ladder for debt obligations. A low-gear firm facing concentrated repayments within twelve months presents a different risk profile than one with evenly spaced maturities extending over a decade. Check for off-balance-sheet obligations. Operating leases under IFRS 16 and ASC 842 must now be capitalized on the balance sheet, which has reduced the ability to disguise leverage. However, certain pension liabilities, contingent obligations, and joint venture commitments may still fall outside the standard ratio calculations. Request the footnotes and audit adjustments. The information is there if you know where to look. Finally, assess the company's capacity to increase leverage if conditions improve. Low gearing is valuable partly because it preserves borrowing capacity for future opportunities. A firm with ample headroom can act decisively during market dislocations. A firm that starts at moderate leverage levels has less flexibility when the next cycle turns.