What actually happens when a financial crisis spreads
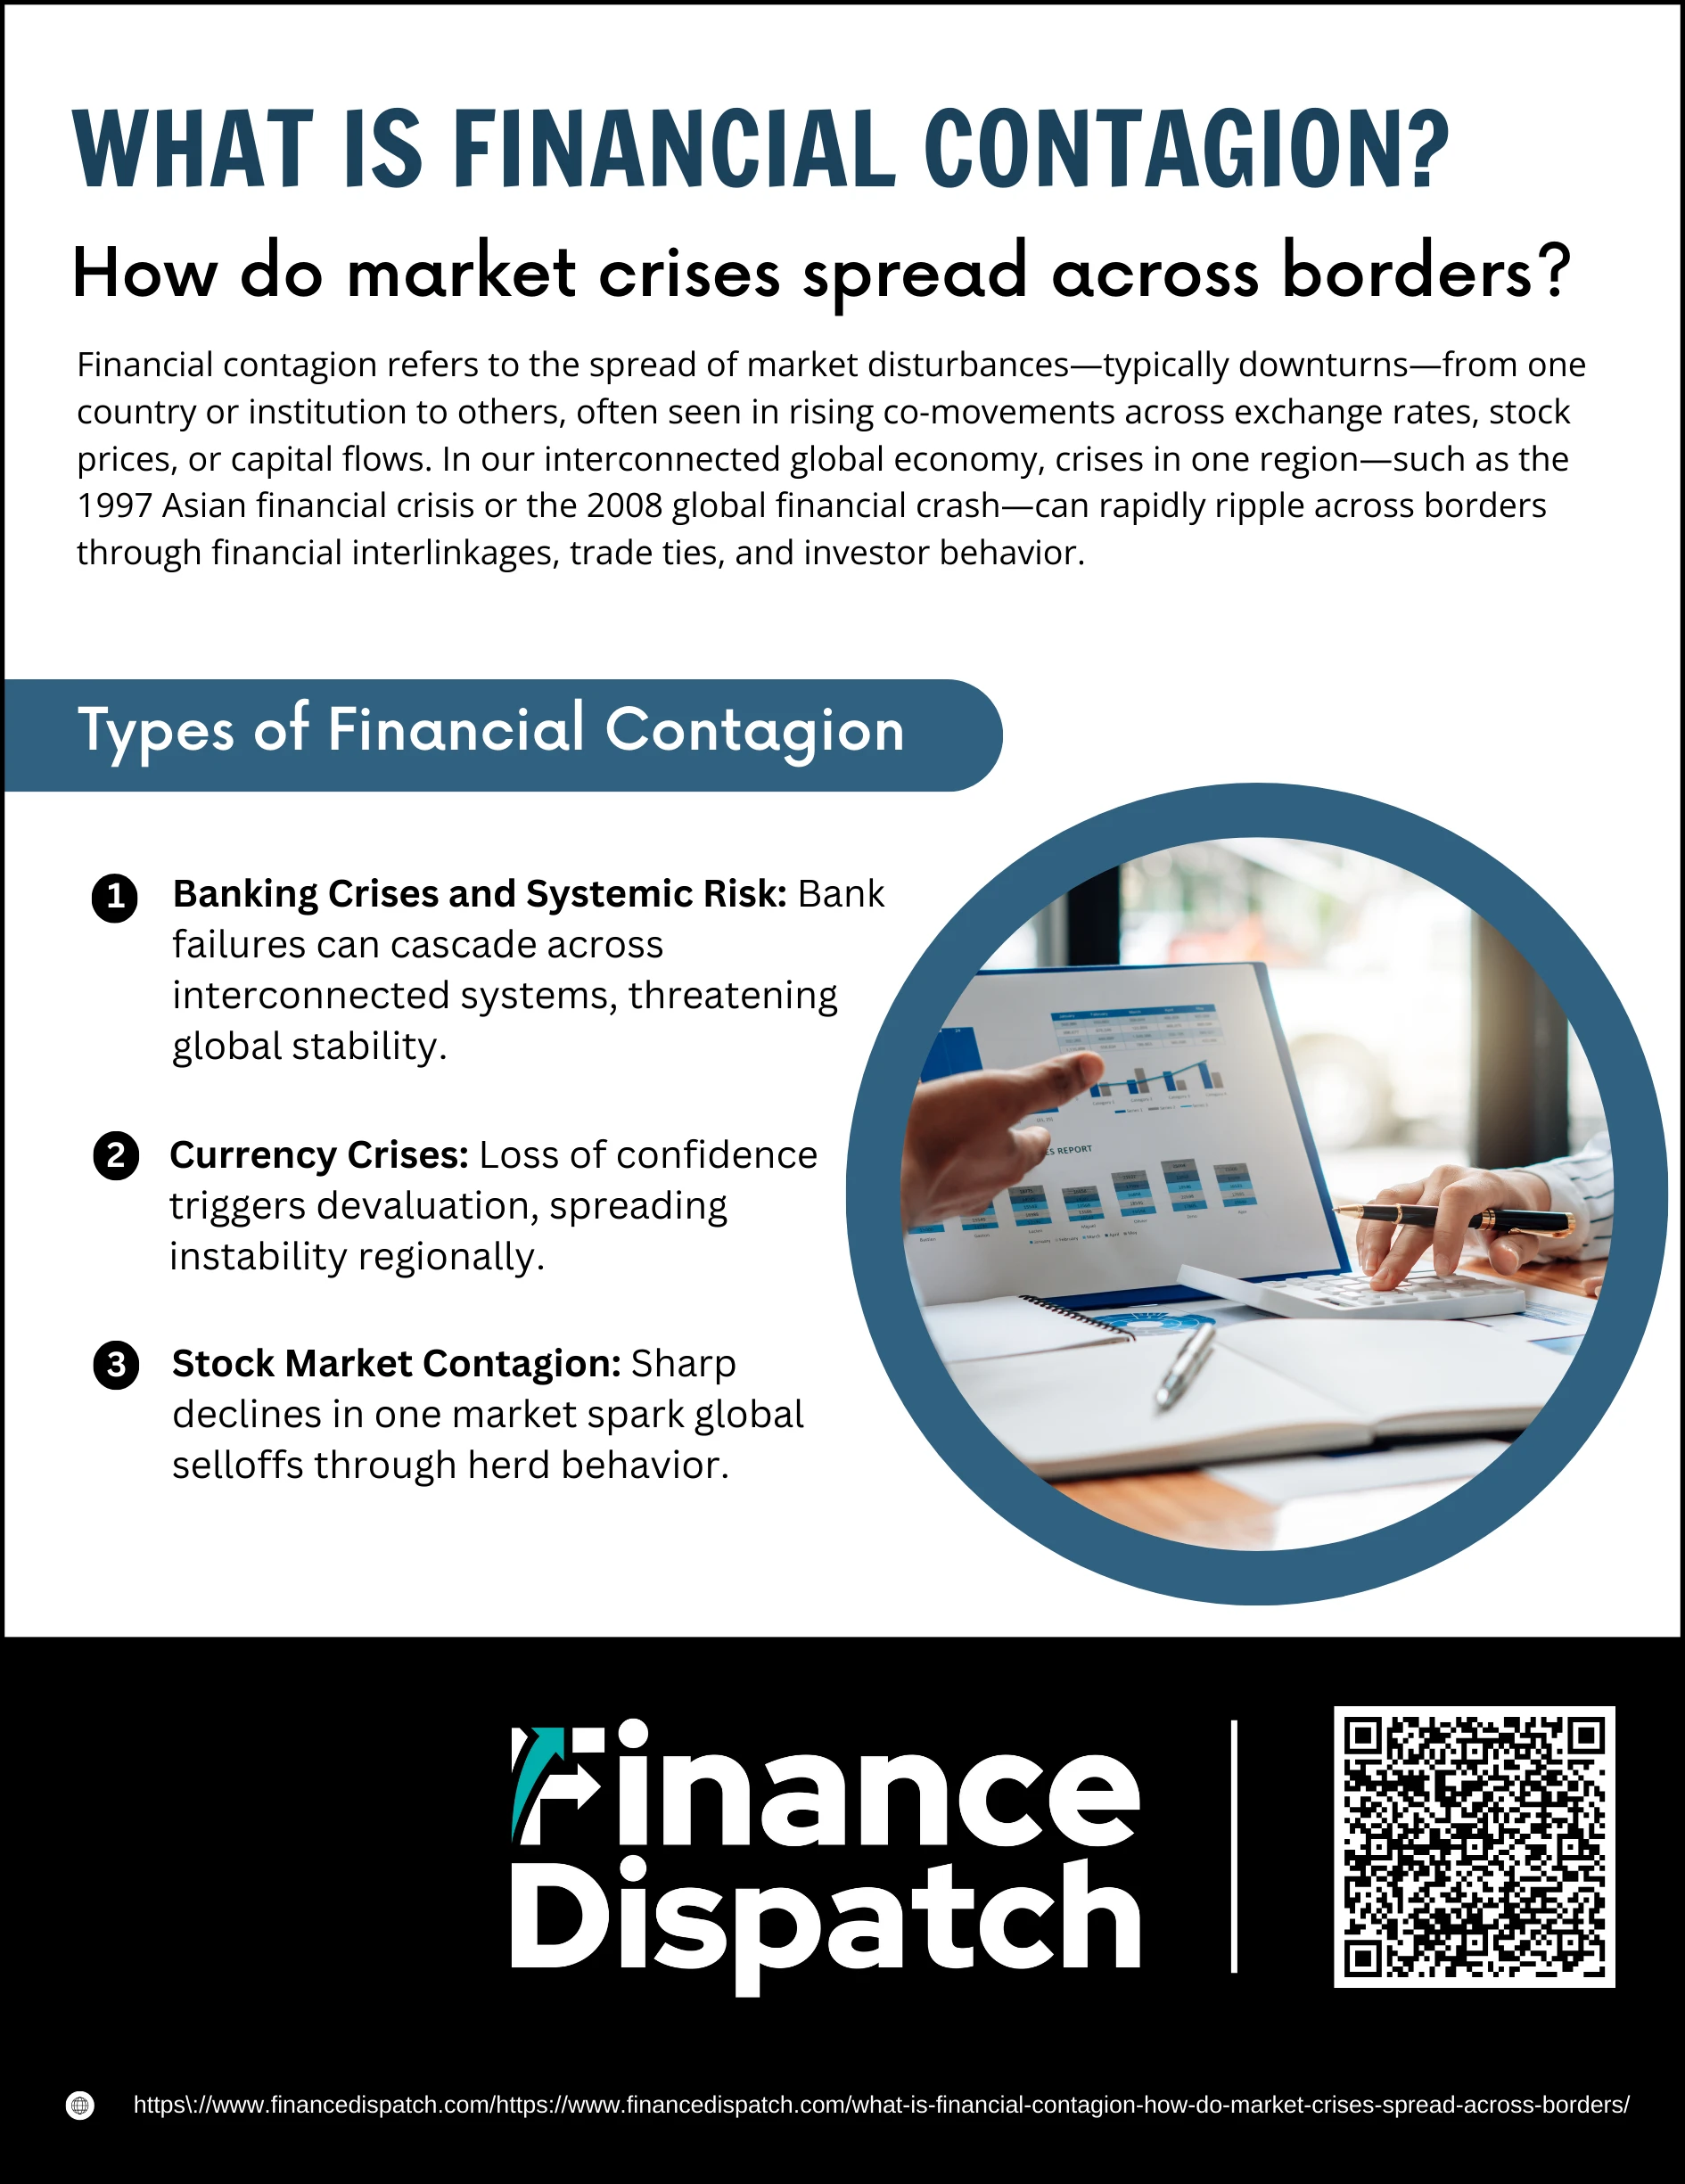
Financial contagion is the mechanism by which distress in one part of the system moves to other parts that may have nothing directly to do with the original problem. It is not magic. It is a combination of interconnected balance sheets, shared funding sources, behavioral feedback loops, and institutional design choices that create channels for shock transmission. I spent years watching markets handle these events, first on the sell side during the 2008 crisis and later in risk management roles where I had to actually contain damage. The textbooks make it sound linear. It rarely is.
Understanding Financial Contagion A Comprehensive Guide How Crises Spread And How To Contain Them
Here is what matters most: contagion does not require a causal link between the affected and unaffected entities. It only requires shared perception and shared exposure. Once market participants decide something is contagious, the decision itself becomes a transmission channel. Contagion operates through four primary channels. Direct exposure channels involve actual contractual obligations, like interbank loans or derivatives contracts. If Bank A fails, Bank B suffers a direct loss on its balance sheet. This is the simplest case and the easiest to model. Funding liquidity channels matter more in practice. When one institution faces stress, lenders become reluctant to roll over short-term funding across the board. A well-functioning hedge fund might find itself unable to borrow from the same prime brokers that continue lending to less risky counterparties. The difference is not always rational. It is often just risk managers adjusting limits based on headline risk.
Information asymmetry creates a third channel. When you cannot tell whether a troubled institution is fundamentally broken or temporarily illiquid, you treat all similar institutions as potentially broken. This is why runs happen. They happen because verification is expensive and slow. By the time you figure out which bank has bad loans and which one just has a timing problem, the depositors have already moved. Behavioral and panic channels are the messiest. Margin calls force fire sales. Fire sales depress asset prices. Depressed prices trigger additional margin calls. This loop can transform a localized problem into a systemic one within days, sometimes hours. The logic is flawed but self-reinforcing.
Get the Full Details
How containment actually works in practice
The theoretical toolkit includes capital buffers, liquidity requirements, stress testing, and central bank backstops. The practical toolkit is considerably narrower and depends entirely on timing. Once contagion has velocity, standard tools often move too slowly. The most effective containment strategy involves three sequential steps. First, you isolate the transmission channels. Second, you restore confidence in those channels specifically. Third, you provide enough liquidity to break the feedback loop without creating moral hazard that outweighs the benefit. Let me give you a concrete example. During the 2011 European sovereign debt escalation, I watched a mid-tier peripheral bank face a funding squeeze that had zero to do with its actual credit quality. The problem was counterparty risk perception. Its derivatives collateral calls were being treated as distressed despite the underlying exposures being investment grade. The workaround was not a broad liquidity injection. It was a targeted guarantee on a specific repo window that the central bank had available but was not actively promoting. Once the guarantee became visible, the spreads tightened within forty-eight hours. The institution itself changed nothing about its operations.
The lesson here is that containment often requires specificity, not scale. Broad responses are politically easier but operationally less efficient. They also create larger moral hazard problems.
Common mistakes people make when analyzing contagion risk
Most analysis focuses on direct exposure networks. This misses the funding and information channels entirely. A network map showing interbank loans will make you think the system is resilient. It will also make you wrong during a crisis because the transmission happens through collateral haircuts and funding withdrawals, not through bilateral defaults. Another mistake is assuming that correlation data from calm periods predicts contagion pathways. Correlations spike during stress and then collapse. Historical correlation matrices become nearly useless precisely when you need them most. This is not a modeling limitation. It is a fundamental property of crisis dynamics. The worst mistake I see repeatedly is treating contagion as purely external. Institutions often build contagion risk into their own operations through concentration decisions, funding maturity mismatches, and collateral dependency. You cannot contain what you helped create.
What the containment framework actually fails at
I need to be blunt about the limitations. Containment strategies work best when applied early and with surgical precision. They fail badly when deployed late or as blunt instruments. Central bank backstops during the 2008 period did prevent total collapse. They also delayed necessary deleveraging and created uncertainty about which institutions were truly solvent, which prolonged the crisis slightly compared to a cleaner resolution approach. The second failure mode is behavioral unpredictability. No model captured the speed of the money market fund breakdown in September 2008. The Reserve Primary Fund's bread crumbing below par triggered withdrawals that no stress test had seriously modeled. Containment frameworks assume rational actors responding to incentives. They do not account for panic-driven threshold effects where behavior shifts discontinuously. A third limitation is cross-border contagion. Domestic containment tools have limited reach when the transmission crosses jurisdictions. The 2011-2012 European crisis demonstrated this clearly. National guarantees could only go so far before sovereign credit quality itself became the contagion vector. There is no clean containment mechanism for sovereign-bank doom loops beyond political coordination, which is unreliable by definition.
Practical steps for building resilience
If you are evaluating contagion exposure in a portfolio or institution, start with funding concentration metrics rather than asset correlation metrics. Know who your lenders are, what their risk limits look like under stress, and what triggers would cause them to withdraw. This information is harder to get than portfolio data. It is also more predictive of actual crisis behavior. Stress test your collateral dependency. Many institutions assume they can roll over collateralized borrowing at standard haircuts during stress. This assumption breaks down frequently. Haircuts on even high-quality collateral can double or triple within days. Build scenarios where your acceptable collateral suddenly becomes unacceptable to your funding sources. Maintain excess liquidity buffers sized for funding channel disruption, not just direct default scenarios. The 2008 experience showed that having good assets means nothing if you cannot use them as collateral when everyone else is desperate for cash. Cash and central bank reserves do not suffer haircut risk. That property makes them valuable in exactly the scenarios where other liquidity sources disappear.
Monitor counterparty risk limit systems at your funding providers. When a major lender adjusts its risk parameters, you will see it in margin calls and collateral requirements before you see it in pricing. These adjustments are leading indicators of funding channel stress. They arrive before the panic becomes visible in spreads or volumes.

A note on what data actually helps
Standard network analysis based on reported exposures provides limited insight. The useful data points are much harder to obtain. Things like intraday payment flows, collateral velocity, and real-time margin call triggers reveal contagion dynamics that balance sheet snapshots completely obscure. If you have access to transaction-level data from clearinghouses or central banks, use it. If you do not, proxy measures like funding cost changes across apparently similar institutions can signal emerging contagion channels before direct exposure data would show anything unusual. I once identified an emerging contagion vector in a regional banking group by tracking the widening spreads between their commercial paper and similarly rated peers in a different region. The direct exposure between the two groups was negligible. The transmission channel was entirely behavioral. Risk managers at the commercial paper buyers were using a shared risk model that flagged both groups once one showed distress. The fix was not capital. It was visibility. Getting counterparties to understand the actual exposure relationship changed the funding dynamics immediately. Contagion is a structural problem with behavioral amplifiers. Understanding the structure gets you partway there. Recognizing when behavior is about to amplify the shock is what separates effective containment from reactive damage control.


