What Bond Yield Actually Means
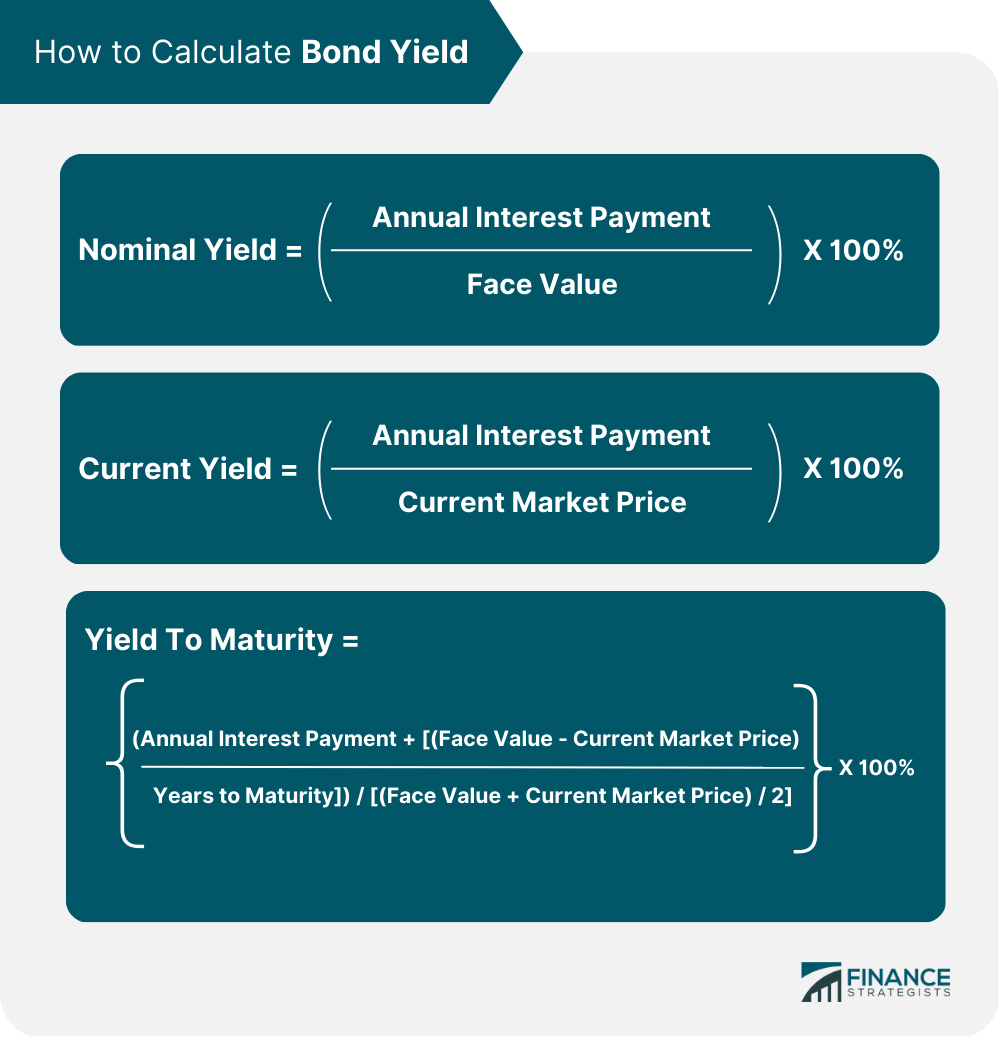
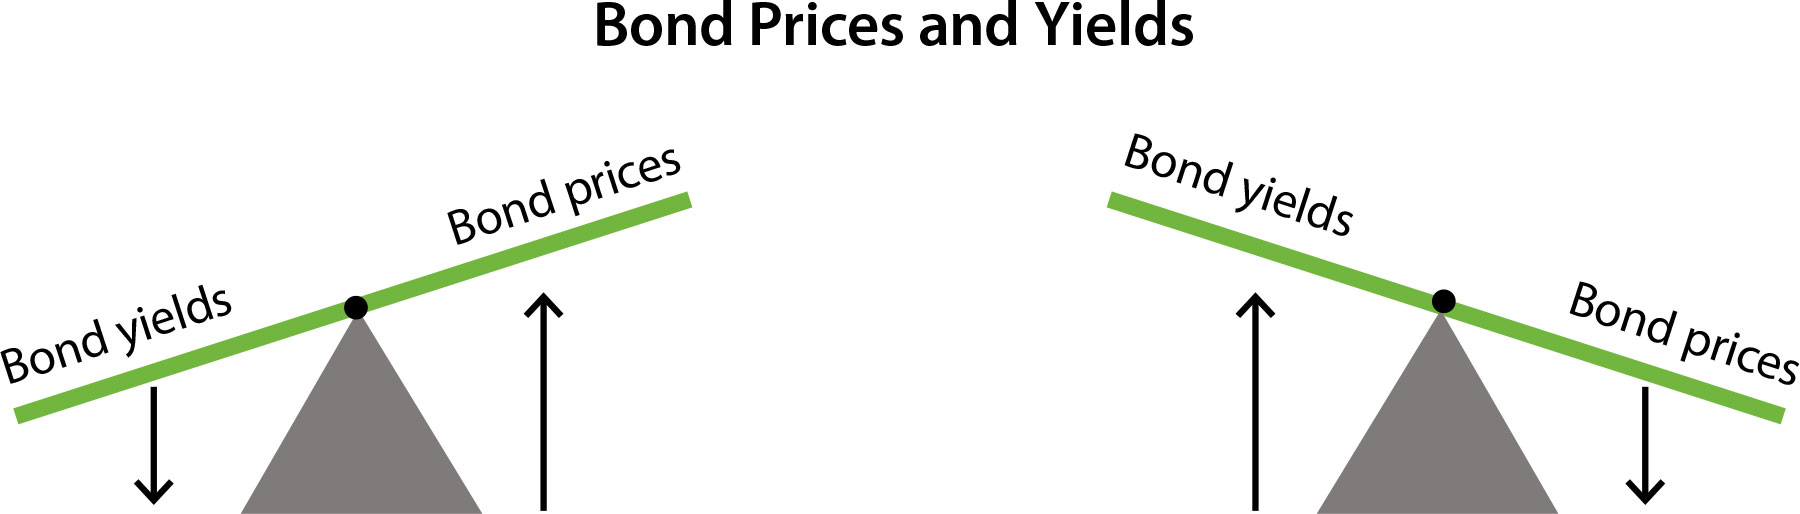
Bond yield is the return you earn on a bond, expressed as a percentage. That's it. Not complicated. But the way it's calculated changes depending on which version you're looking at, and that's where most people get tripped up. There are three main types you'll encounter: current yield, yield to maturity, and yield to call. Current yield is just the annual coupon payment divided by the bond's current price. Yield to maturity factors in the coupon payments plus any capital gain or loss if you hold the bond until it matures. Yield to call does the same thing but assumes the bond gets called away early. The inverse relationship between price and yield is the first thing that trips people up. When bond prices go up, yields go down, and vice versa. It's not intuitive until you work through the math a couple of times. I remember a junior analyst on my team once told me he couldn't sleep for two nights because he kept mixing up which direction the relationship went. He was fine after that.
How to Calculate It Yourself
Current yield is straightforward arithmetic. Say you own a bond with a $1,000 face value that pays a 5% annual coupon, meaning $50 per year. If the bond is trading at $950, the current yield is 50 divided by 950, which comes to about 5.26%. Simple. Yield to maturity requires a financial calculator or a spreadsheet. The formula solves for the discount rate that makes the present value of all future cash flows equal to the bond's current price. In Excel, you'd use the YIELD function. In a financial calculator, you'd input the settlement date, maturity date, coupon rate, price, redemption value, and frequency, then compute YTM. Here's where it gets messy. If the bond pays coupons semiannually, the calculator needs to know that. Input annual periods instead and your YTM will be wrong. I've seen this mistake cost people real money on actual trades. Always double-check the payment frequency before hitting calculate.
The Things Nobody Tells You About Yields
One counter-intuitive point: two bonds can have the same coupon rate but very different yields because their prices differ. A bond trading at a discount will have a higher YTM than an identical bond trading at par, even though both pay the same coupon. The discount is essentially extra return layered on top of the coupon. Another thing beginners miss is that yield doesn't account for reinvestment risk. The YTM calculation assumes every coupon payment gets reinvested at the same rate. In reality, rates fluctuate. If you're holding a 10-year bond and rates drop by half over that period, your actual return will fall short of the stated YTM because you're reinvesting coupons at lower rates. This gap between expected and realized return is called reinvestment risk, and it matters more the longer the bond's maturity. I ran into a specific problem a while back with a municipal bond that was priced using its yield to call instead of yield to maturity. The bond had a call date five years out, but it was trading well below the call price, which made the YTC look attractive. The market was pricing in the assumption that the issuer would call the bond early. But when I dug into the issuer's finances, I saw they had no realistic ability to refinance at lower rates. The bond wasn't going to be called. The yield to call was misleading. I switched to yield to worst, which gives you the lowest of YTM or YTC, and that was the number that actually mattered for my decision.
Get the Full Details
When Yield Numbers Lie to You
Yield to worst is the practical approach. It gives you the lowest possible yield across all scenarios. If a bond can be called, put, or mature, YTW shows you the worst case. That's the number you should be using for comparison, not the headline YTM. There are also edge cases with zero-coupon bonds, callable bonds, and bonds with sinking funds where standard yield calculations break down or become meaningless. Zero-coupon bonds have no cash flow until maturity, so their yield is purely a function of the discount from price to par. Callable bonds introduce optionality that changes everything. A callable bond will always trade at a lower yield than an otherwise identical non-callable bond because the call option benefits the issuer, not you. The extra yield you'd expect for taking on price risk is partially cancelled out by the call feature. I once worked with a portfolio that held a bunch of convertible corporate bonds. The yields looked decent on paper, around 6 to 7 percent. But the conversion features were deeply out of the money, and the companies were under pressure. The bonds weren't going to convert. They were just regular corporate bonds with fancy packaging. The yields made sense only if you treated them as straight debt, which meant stripping out the conversion option and valuing them on credit risk alone. That changed the entire risk profile of the position.
Practical Shortcuts That Actually Work
If you want a quick estimate of YTM without a calculator, there's an approximation formula. Take the annual coupon payment plus the annualized capital gain or loss, then divide by the average of the bond's price and its face value. For a bond priced at $950 with a $50 coupon and five years to maturity, the capital gain is $50 spread over five years, or $10 per year. Add that to the $50 coupon for $60 total. Divide by the average price of $975. Your approximate YTM is about 6.15 percent. The actual YTM from a calculator would be slightly higher, maybe 6.3 or 6.4 percent, but the approximation is close enough for most screening purposes. For bonds trading at or near par, the current yield and the YTM will be nearly identical. That's because there's almost no capital gain or loss to factor in. This is useful as a quick sanity check. If you see a bond trading at par with a stated YTM that's wildly different from its coupon rate, something is wrong with the data or the pricing. One more practical note: when comparing bonds across issuers or sectors, don't just look at the yield. Look at the yield spread over the risk-free rate, usually measured against Treasuries of similar maturity. A corporate bond yielding 7 percent sounds fine until you realize the Treasury benchmark is at 6.5 percent. That spread of only 50 basis points might not compensate you for the credit risk. The spread is what matters, not the absolute yield number.
Bond yields are one of those things that seem simple until you try to use them for actual decisions. The math isn't hard. The assumptions behind the math are where the problems live. Know which yield you're looking at, know what it assumes, and know what it's hiding. That's really all there is to it.