What Iamerica Actually Does
Iamerica is a debt settlement company. That means they negotiate with your creditors to accept less than what you owe. They typically tell you to stop paying your credit card bills and instead funnel that money into a dedicated savings account they set up for you. Once enough money accumulates, they approach your creditor to settle the debt for a lower amount. The math is supposed to work in your favor because creditors would rather get some money back than chase you into bankruptcy and get nothing. This model has been around since the late 1990s and it absolutely works for the right person at the right time. But the right person is narrower than most marketing makes it seem. I have seen enough people walk through this process to tell you where it actually breaks down.
Uncovering The Truth Is Iamerica Credit Card Debt Relief A Legitimate Option
Legitimate is the wrong word to be searching for. The real question is whether it fits your situation. Iamerica is a registered company with Better Business Bureau profiles, customer reviews across multiple platforms, and standard debt settlement contracts. They are not a scam. That does not mean they are the right move for you. Here is what I have seen go wrong in practice. I had a case where someone came to me after their third month with Iamerica. They had stopped paying on a $28,000 credit card balance. The account was now in collections. Their credit score had dropped from 680 to about 540. Iamerica's representative told them to expect settlement offers within 12 to 18 months. The problem is that by month three, the creditor had already charged off the account and sold it to a collection agency. At that point, Iamerica was negotiating with a third party that had bought the debt for pennies on the dollar and had zero incentive to give those savings back to the consumer. The workaround for situations like this is simple but nobody tells you upfront. Before you enroll, get the current status of every account you plan to include. If an account is already past 180 days delinquent, it may already be charged off. A debt settlement company cannot resurrect a charged off account the same way. You are negotiating with whoever currently owns the debt, and that entity may not have the same relationship with the original creditor.
How the Process Actually Works Step by Step
You start with a free consultation. They pull your credit report and ask about your total unsecured debt, your income, your monthly expenses, and which creditors you owe. Then they run a feasibility analysis. This is the part where they decide whether any of your debts are actually eligible for settlement. Not all debts get enrolled. Medical debt and federal student loans typically do not qualify. Some creditors simply will not negotiate settlement, and Iamerica will flag those during this phase. Once you sign the contract, you open a dedicated savings account. This is usually through a third-party escrow or savings partner, not an Iamerica bank account. You make monthly deposits into that account. The idea is that you are accumulating the settlement funds while also building a buffer. Iamerica then begins negotiating with your creditors. Most settlements take between 24 and 48 months to complete. During that time you are responsible for making your monthly deposits and covering any new expenses that come up. When a settlement is reached, the creditor agrees to accept a specific amount, usually between 40 and 60 percent of the original balance. The funds from your savings account are sent to the creditor. You then owe nothing more on that account, assuming the agreement is fully documented in writing before any payment is made.
Get the Full Details
What Nobody Tells You About the Costs
Iamerica charges a fee structure that is standard across the industry. They typically charge a setup fee plus a percentage of the debt that gets settled. Some contracts charge a monthly maintenance fee regardless of whether a settlement is reached. The exact numbers vary by state and by the total amount of debt enrolled. The hidden cost is the one most people ignore. While you are not paying your credit card bills, interest and fees continue to accrue on the original balances. A $20,000 balance at an 18 percent APR can grow to roughly $23,600 in one year without any new charges. The settlement company is negotiating against the new higher balance, not the original amount. Your savings account needs to cover not just the settled amount but also whatever growth has accumulated. Then there is the tax consequence. Forgiven debt over $600 is reported to the IRS as income on a 1099-C form. This is not unique to Iamerica. It is a federal requirement for any creditor that forgives more than $600 of debt. Most people discover this six months after their program ends when tax season arrives. I have seen clients hand the IRS several thousand dollars in additional tax liability because they did not anticipate the forgiven balance being treated as taxable income.
Who This Actually Works For
Debt settlement works best when you have unsecured debt above $10,000, you are already behind on payments or facing imminent default, and you have the discipline to keep funding your savings account consistently. It also helps if your creditors are large national banks or well-known brands. Those institutions typically have dedicated settlement departments and can process a negotiation faster than a small regional bank or credit union. It does not work well if your total unsecured debt is under $5,000. The fees often eat up most of the savings. It does not work if you need to maintain a decent credit score during the process. Every missed payment, every collection account, every charge-off stays on your credit report for seven years. And it does not work if you are relying on credit card rewards or cash back on accounts you are about to close out. People who drain their points right before enrolling often regret that decision later.
Red Flags and Where to Look
Before signing anything, check the BBB profile, but read the actual complaints, not just the rating. Look for patterns: companies that refuse to put settlement agreements in writing, that demand upfront fees before any work is done, or that guarantee a specific result. Guaranteeing a result is a lie. No reputable settlement company can promise an exact settlement amount because the creditor controls that decision. Also verify that Iamerica is registered to operate in your state. Debt settlement companies must be licensed in the state where you reside and where the creditor is located. Operating without that license can invalidate your contract and leave you with no recourse.

Alternatives Worth Considering
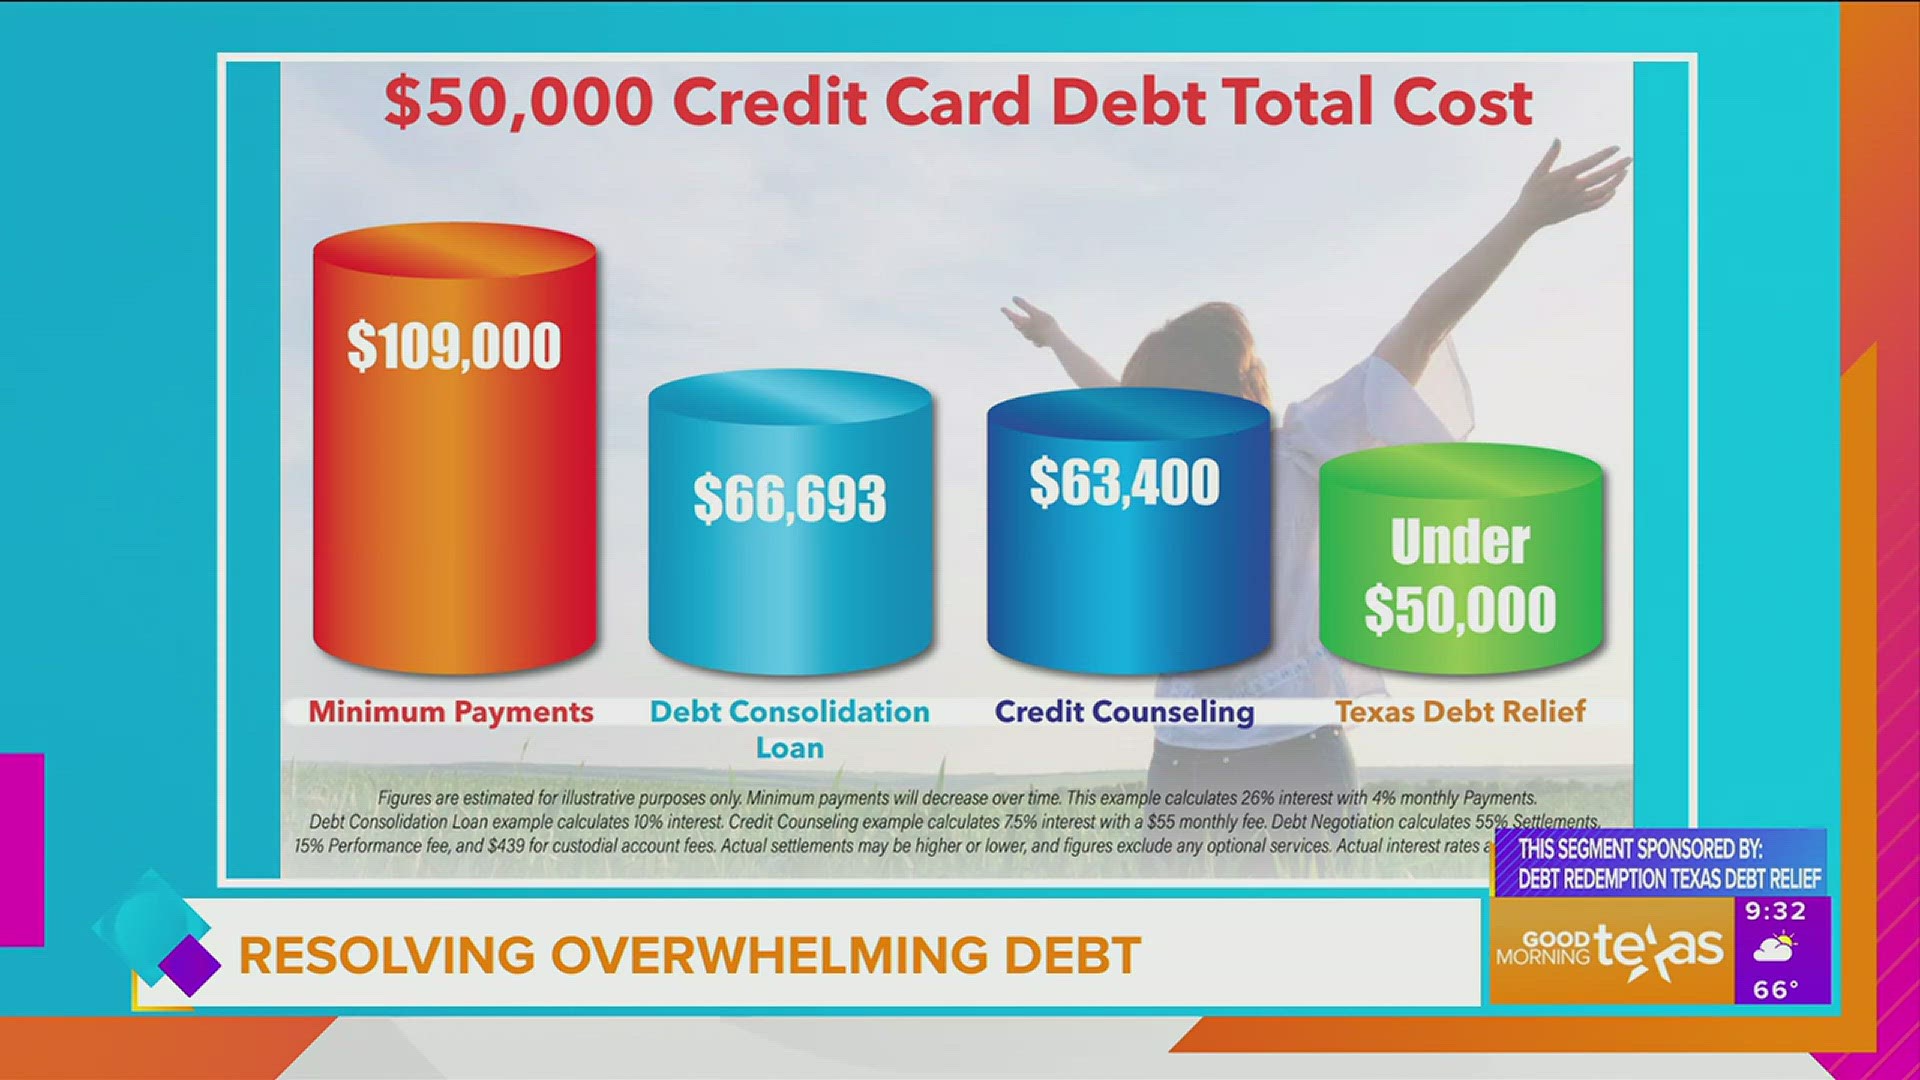
If your debt is smaller or you are not yet behind on payments, a debt management plan through a nonprofit credit counseling agency is usually cheaper and less damaging to your credit. You continue paying your creditors on time. The counselor negotiates reduced interest rates. You pay a small monthly fee. The total cost is lower and your credit history remains intact. If you are facing wage garnishment or a lawsuit, debt settlement will not stop that. You would need legal counsel or bankruptcy consultation. A Chapter 7 filing discharges most unsecured debt in about four months. A Chapter 13 restructures payments over three to five years. Both have credit consequences, but they are predictable and legally binding, unlike a settlement negotiation where the creditor can simply decline to respond.
Bottom Line
Iamerica is a real debt settlement company and the process can save you money if your situation matches the criteria. The catches are the credit damage, the tax liability, and the requirement that you stop paying your bills while building a savings account that you must fund reliably for potentially two to four years. If you can handle all three of those and your debt profile fits, it is a viable option. If you cannot, one of the alternatives will likely serve you better.