Ford Stock Basics You Actually Need to Know
Ford Motor Company trades on the New York Stock Exchange under the ticker symbol F. It's been a public company since 1956, when the Ford family stepped back from day-to-day management and the shares opened for public trading. Before that point, the Ford family held the majority of voting power through Class B shares, which meant outside investors couldn't meaningfully influence board decisions. That structure changed, and today the company operates like any other large-cap industrial stock on the exchange. One thing people get wrong about Ford's ticker is assuming the stock price moves the same way a typical consumer discretionary name should. It doesn't. Ford is tied to commodity prices, union contracts, and interest rates in ways that most retail traders don't fully factor into their positions. I learned this the hard way during the 2021 chip shortage period when the stock dropped on what looked like a solid quarterly earnings beat. The miss wasn't in the numbers — it was in the guidance, and specifically in the margin pressure from aluminum and lithium costs that the market hadn't priced in yet. The stock stayed depressed for six months while everyone waited for the auto sector narrative to catch up.
Uncovering The Truth Is Ford Publicly Traded
The question itself sounds like something pulled from a Reddit thread or a crypto forum, but it points to a real gap in how people approach Ford as an investment. A lot of folks know the brand and assume they understand the stock. They don't. The difference between knowing Ford makes trucks and understanding what drives F's valuation sits in the details — the pension obligations, the credit ratings, the fact that Ford's commercial fleet division alone generates more revenue than the entire GDP of some mid-sized countries. If you're looking at Ford for the first time as an investor, start with the SEC filings rather than financial media. The 10-K tells you exactly what the business is exposed to. Ford's annual report breaks out the automotive financing segment separately from the vehicle manufacturing segment, and those two divisions have completely different margin profiles and risk factors. The financing side carries credit risk that most new readers miss because it's buried in the notes. I've seen people get surprised by earnings drops that were entirely predictable if they'd just read the bad debt reserve disclosures in section seven of the 10-K. The stock also carries a dividend that has survived several rough patches, which is unusual but not without its own complications. Ford cut its dividend in 2020 and raised it only gradually afterward. If you're buying for income, the yield looks attractive on paper but the payout ratio is the real metric that matters. Ford has been running a payout ratio somewhere in the 40 to 60 percent range depending on the cycle, which means there's room to maintain the dividend even through downturns — but also room for another cut if things deteriorate significantly.
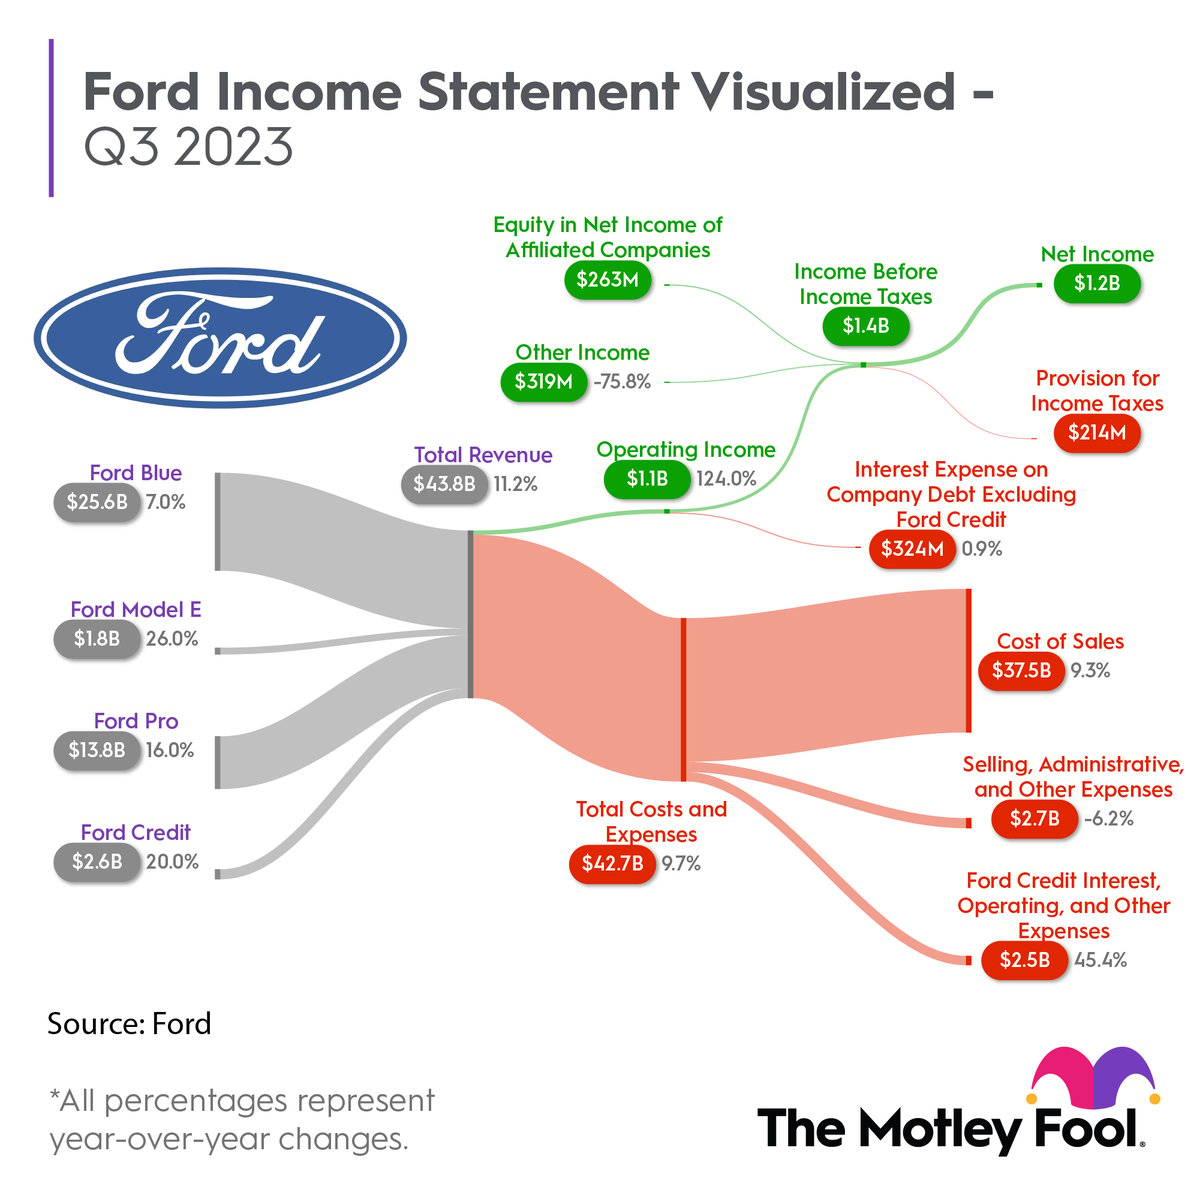
Another practical detail that trips people up: Ford's ADR structure for international investors. If you're trading Ford outside the United States, you're likely dealing with an American Depository Receipt rather than direct common stock. The ADR converts at a 10-to-1 ratio against the underlying share, and the fees are minimal but they exist. Over a long holding period, the expense ratio on the depository can add up to a noticeable drag on total return. I switched my position to track the underlying NYSE share directly through my brokerage's international trading desk and saved roughly 0.05 percent annually in implicit costs. Small number, but meaningful if you're holding for years. The EV transition is the factor everyone talks about but few analyze honestly. Ford's Electric Vehicle division posted losses of over two billion dollars in 2023 and roughly three billion in 2024. Those losses are real and they're growing, not stabilizing. The market prices this in partially through the stock, but not fully — which is why the stock occasionally rallies on EV news and then gives back those gains when the loss figures come out. If you're investing based on Ford's electric vehicle story alone, you're betting on a sector that is currently destroying value at scale. That doesn't mean it won't turn around. It means you should size your position accordingly. For anyone who actually wants to track Ford as a public investment, the practical setup is straightforward. Open a brokerage account that supports NYSE trading, verify your tax documentation if you're outside the U.S., and pull the latest 10-K before you commit any capital. The quarterly earnings calls are worth listening to for the margin commentary, but the real information lives in the filings. Management will tell you what they want you to hear on the call. The numbers in the 8-K and 10-Q are harder to spin.
Get the Full Details

There are situations where Ford simply is not a good fit for a portfolio. If you need downside protection or are invested for a horizon shorter than three to five years, the stock's beta and its sensitivity to macro cycles make it a poor choice. The stock can drop 30 to 40 percent in a severe recession and take multiple years to recover, as it did after the 2008 financial crisis. It recovered eventually, but the waiting period tested a lot of investors. If you want exposure to the auto sector without Ford's specific risks, there are alternatives like diversified automotive ETFs or exposure through suppliers like BorgWarner or Magna International. Those names carry different risk profiles and aren't directly tied to the capital-intensive cycle of vehicle manufacturing. I shifted some allocation away from Ford in 2022 toward a broader materials and industrials fund for exactly this reason — I wanted sector exposure without the Ford-specific operational headaches. The bottom line is that Ford is a legitimate, liquid, publicly traded company with a long history and a complex cost structure. Understanding the difference between the brand and the stock is what separates people who lose money on F from people who hold it intentionally. Read the filings. Watch the payout ratio. Size the position for the volatility. Everything else is noise.