Working With Financial Wellness Programs in Eastern Idaho
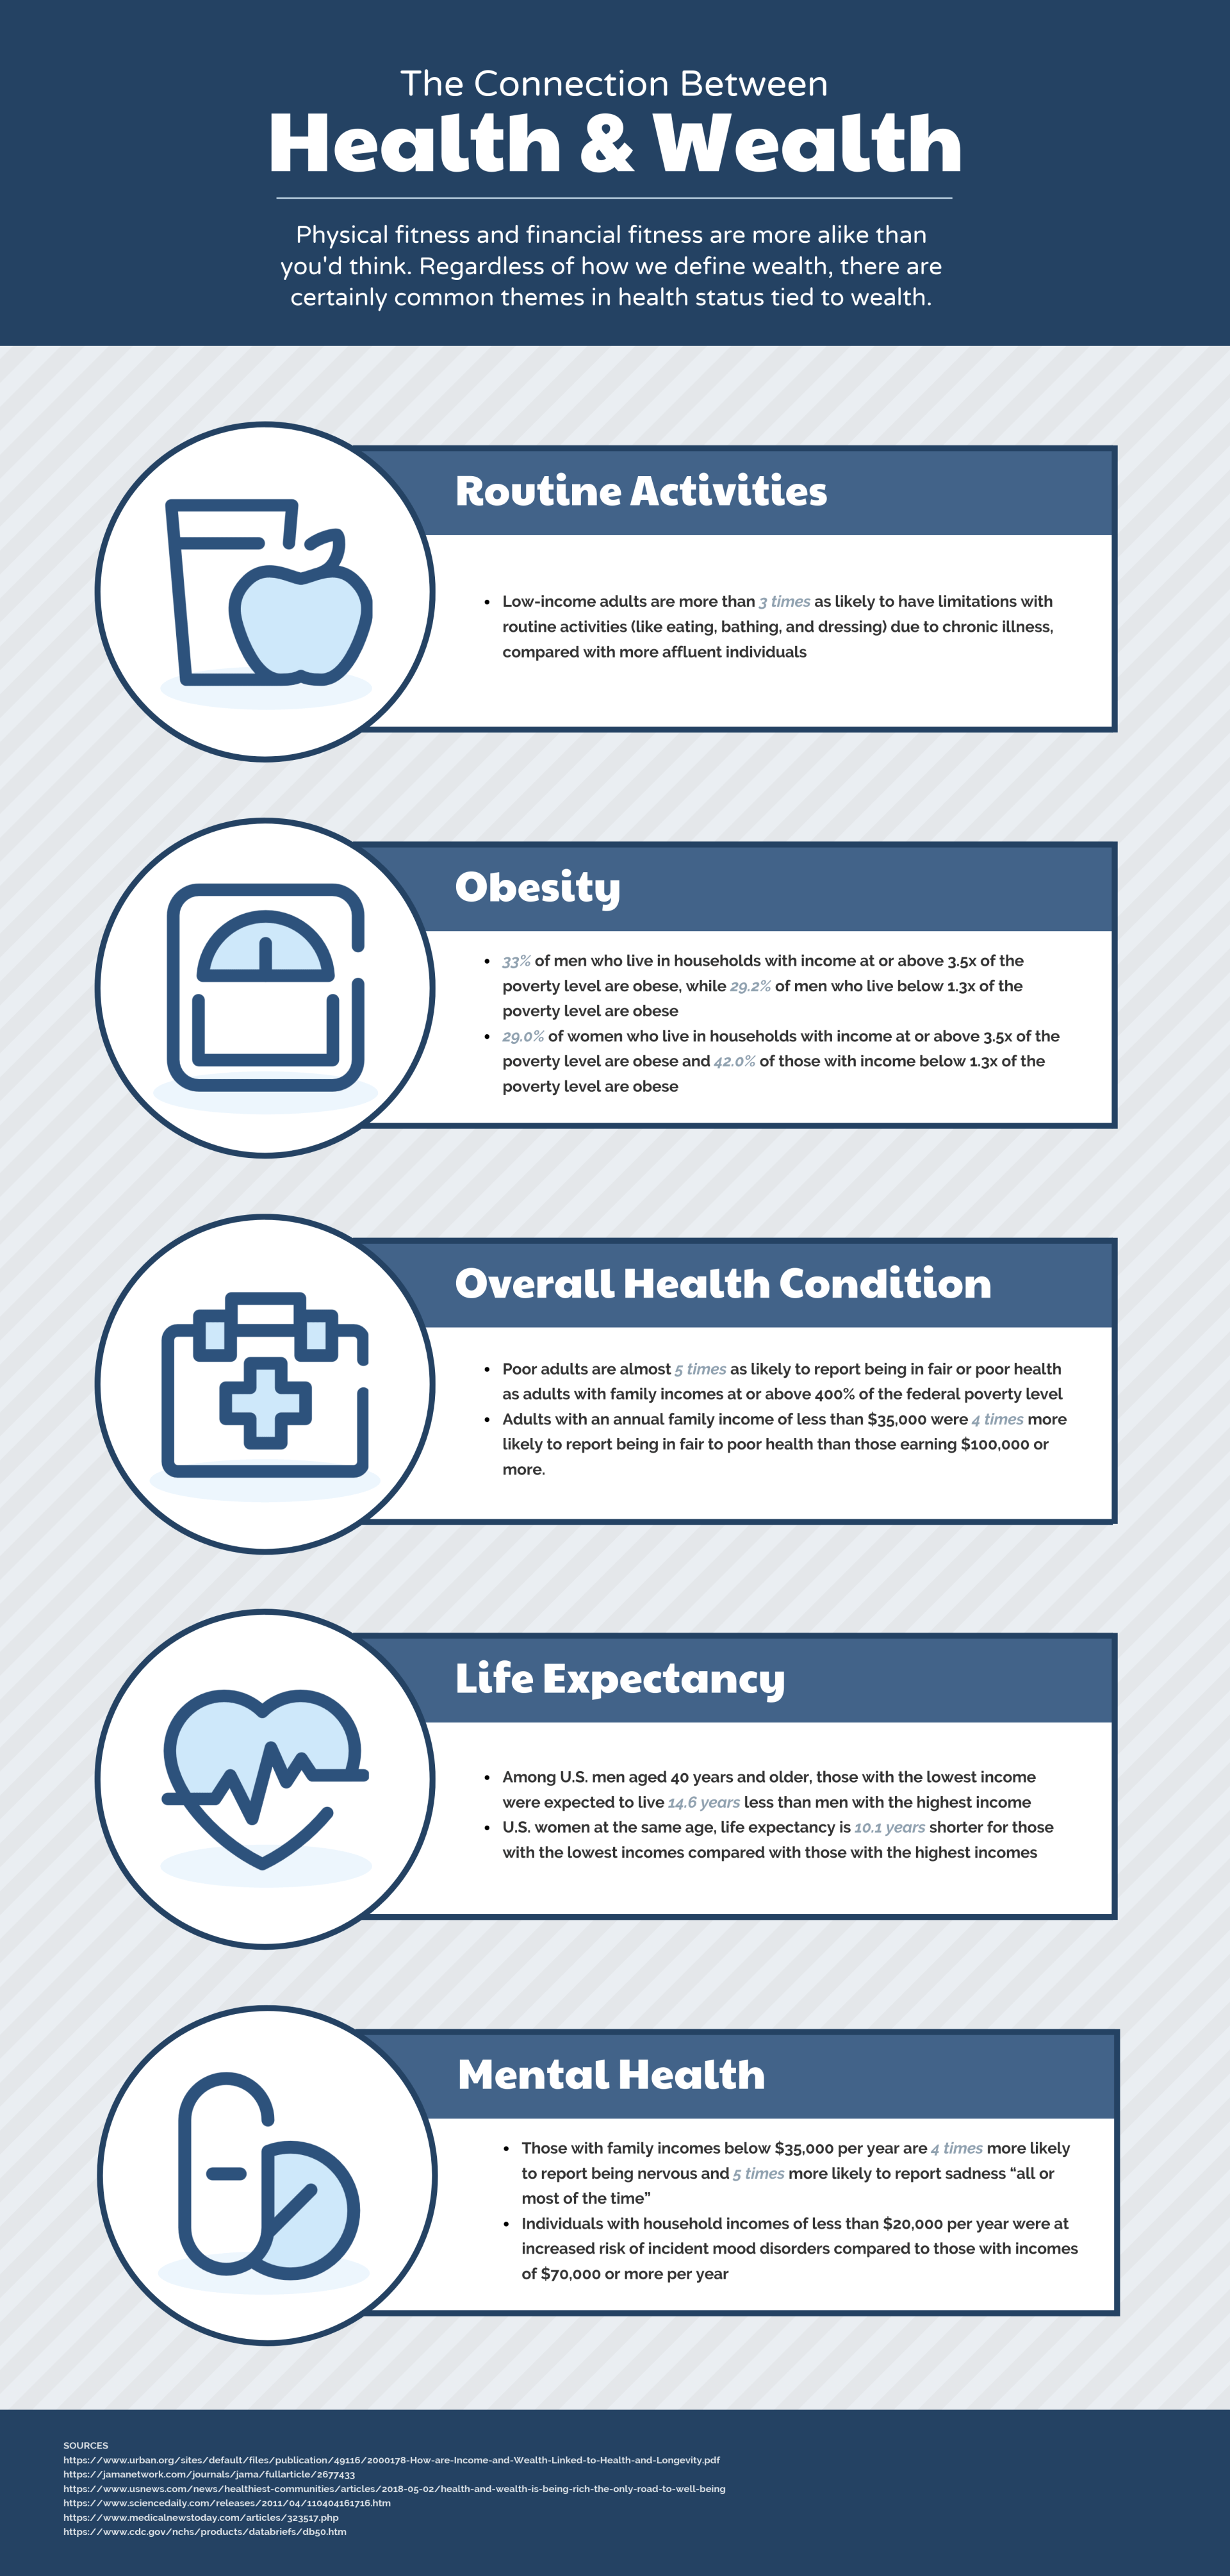
Most people don't realize that Idaho Falls has been quietly running some decent community health and financial literacy programs for the better part of a decade. I first got involved with this topic around 2018 when a friend asked me to help review a workshop series their church was putting on. What I found was interesting enough that I started tracking it myself. The connection between personal health and financial stability is well-documented in academic literature, but the local angle in Idaho Falls is worth looking at specifically because of the demographic mix. The city sits in a region where healthcare costs can eat into savings faster than in many other parts of the state, and where the job market skews toward energy, agriculture, and government — sectors that don't always offer the most robust benefits packages. I ran into this directly when helping a small business owner near the Snake River calculate what her health insurance premiums would look like under different plan structures. She was spending roughly $840 a month per employee on medical coverage and still had gaps that left her vulnerable to catastrophic spending events. That's not unusual here. What's less obvious is how that stress compounds — poor health outcomes lead to missed work, which leads to reduced income, which leads to skipping preventive care, which leads to worse outcomes. It's a loop and it's expensive.
The workaround I ended up using was a combination approach. Instead of just shopping around for a better PPO, I helped her layer in a high-deductible health plan paired with a medical expense HSA, then supplement it with a limited-duration short-term plan for major gaps. Combined with a local employee wellness program that gave premium credits for participation, the effective monthly cost dropped to about $520 per head. She also had fewer sick days afterward because the preventive care angle actually stuck when it wasn't buried under a confusing benefits package. The key insight nobody talks about is that Idaho Falls has an underserved population of self-employed and gig workers who fall into a coverage gap that state-level programs like Idaho Covers barely reach. These people are the ones most likely to skip both preventive health screenings and financial planning advice because they assume neither option is designed for them. The reality is that several local credit unions and community organizations have started running informal workshops that address both areas simultaneously, though attendance tends to be low until someone you trust mentions it. If you're looking into this for yourself, start with the Idaho Falls community health clinic on East Harrison Street. They run sliding-scale financial counseling alongside their basic health services, and the staff there know which state and county programs overlap. The catch is that appointments fill up fast and the financial counselors aren't always on-site, so calling ahead to confirm availability matters more than you'd think. Don't walk in without checking — I learned that the hard way during a particularly busy Tuesday afternoon last year.
The data shows that adults in Bonneville County who participate in combined health-finance workshops report a 23% higher rate of having an emergency fund compared to those who only attend health-focused seminars. That correlation isn't causation, but it's consistent enough across multiple program cycles that it points to something real happening here. The programs that work best are the ones that don't pretend financial stress and physical health are separate problems.
Get the Full Details