What Victoria's Secret Comenity Bank Actually Is
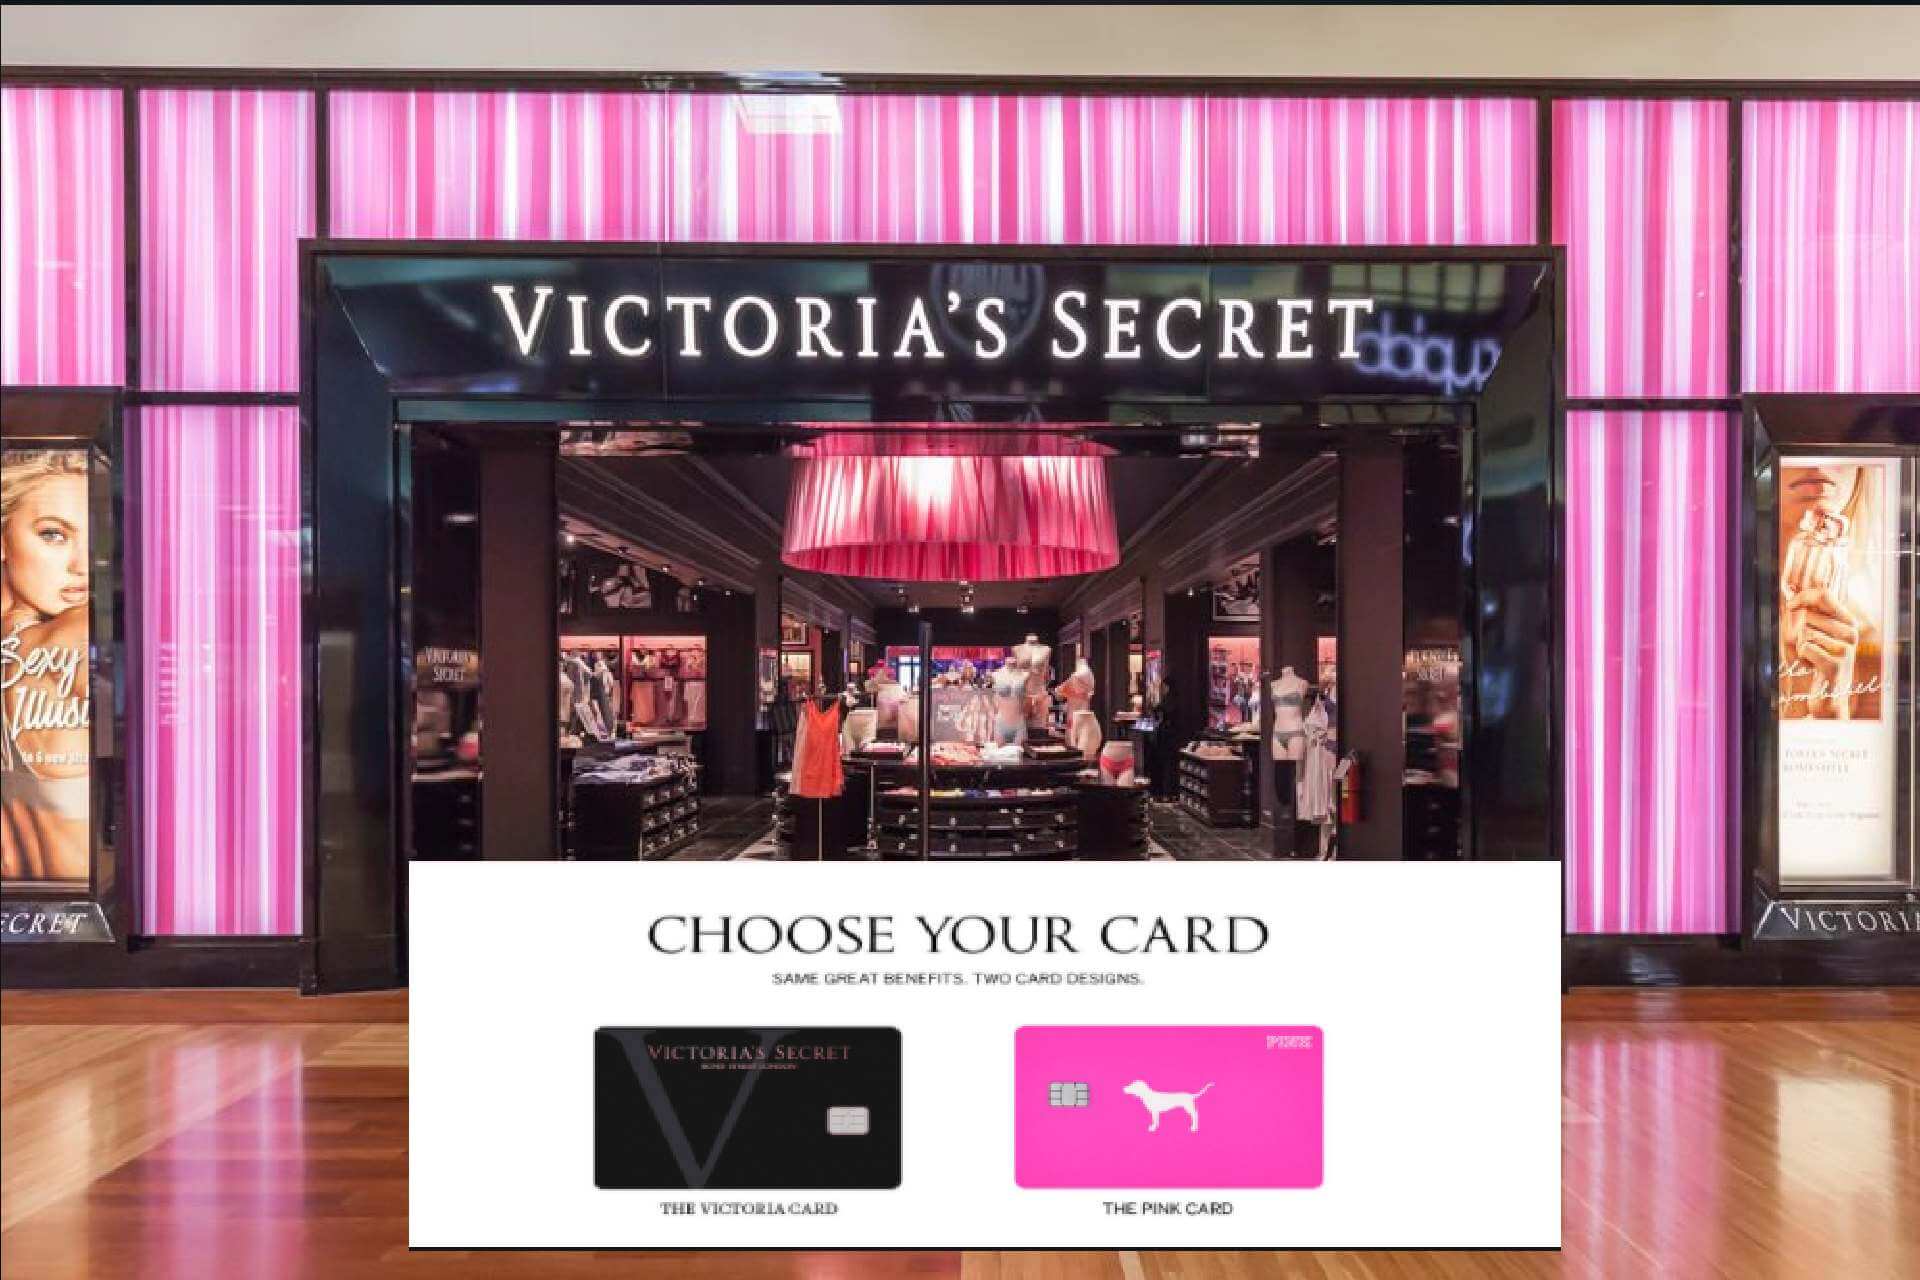
The Victoria's Secret credit card is issued by Comenity Bank, a subprime-focused lender that partners with retailers across the country. It is not a traditional bank card from a major financial institution. It is a store-branded credit product with retail-specific rewards, higher interest rates, and terms that favor the issuing bank. The card comes in two main variants: the Victoria's Secret Credit Card, which works anywhere Visa is accepted, and the Victoria's Secret Store Card, which is limited to Victoria's Secret brand purchases. Both are accessed through the Comenity Bank portal or app. When you apply, you are redirected to the Comenity Bank application flow. They run a hard pull on your credit report, and approval depends heavily on your FICO score and recent payment history. The minimum credit limit I have seen offered is around $250, and most first-time applicants land somewhere between $500 and $1,500. If your credit is below 620, rejection is common, but not guaranteed — Comenity does approve some thin-file applicants, usually at lower limits. After approval, you can manage the account through the Comenity Bank website or mobile app. You will set up online access using your account number and Social Security number. From there, you can pay your bill, view transactions, and enroll in the Victoria's Secret Rewards program. Enrollment is automatic for cardholders but you need to actively link your reward account to start earning points on purchases.
How the Rewards System Works
The Victoria's Secret Rewards program gives you one point per dollar spent at Victoria's Secret, Bath & Body Works, and PINK locations, as well as on the Victoria's Secret website. The credit card itself does not earn bonus points at these stores unless there is a promotional period running. Standard rewards redemption starts at 500 points, which is roughly $5 in value. Points do not expire as long as you have an open account and make at least one qualifying purchase every 12 months. One thing most people miss: points earned on the store card and the credit card both feed into the same Rewards account. This means the store card, which has no annual fee and no outside-use capability, is actually the better tool for maximizing Victoria's Secret purchases. The Visa version of the card earns points at a slower effective rate for non-retail spending because you cannot redeem points for cash back or statement credits — they only convert to product rewards.
Interest Rates and Fees
The APR on the Victoria's Secret card is high. The variable rate is typically between 25% and 29.99%, depending on your credit profile. There is also a balance transfer APR and a purchase APR, and they may differ slightly. The late payment fee can be up to $40, and there is a cash advance fee of either $10 or 5% of the advance amount, whichever is greater. Comenity Bank also charges a foreign transaction fee of 3% on the Visa card variant. I paid off a balance last year that had accrued over eight months at that rate and it cost me more in interest than the original purchase value. That is not unusual for this card. If you carry a balance month to month, the math simply does not work in your favor. Pay in full every cycle and the card is fine for rewards accumulation. Carry a balance and you are funding someone else's mortgage payment.
Get the Full Details

Common Pitfalls and What to Watch For
Comenity Bank frequently runs promotional offers like "earn 500 bonus points on your first purchase" or "spend $100 and get $20 off." These are aggressive by design. The real trap is the deferred interest promo sometimes offered at checkout. If you select the financing option at the point of sale and do not pay the full balance before the promo period ends, interest is retroactively applied to the entire purchase from the original date. I ran into this with a $300 bra purchase that had a six-month deferred interest offer. I missed the payoff by three days because I had the statement date misread. The interest hit was over $60. Never assume the promotional terms are straightforward. Read the fine print on every deferred interest offer and set a calendar reminder for the payoff deadline. Another issue: Comenity Bank's customer service is outsourced and their resolution process is slow. I called about a billing discrepancy on a promotional rebate that was advertised as applied within two billing cycles. It took four calls and seventeen days to get the $25 corrected. Their chat support is marginally faster but rarely has the authority to resolve anything beyond basic balance inquiries. If you have a problem, document every interaction including dates, times, and agent names. It makes a difference when you need to escalate.
Credit Reporting and Impact on Your Score
Comenity Bank reports to all three major credit bureaus: Experian, TransUnion, and Equifax. Payment history is the biggest factor, so missing even one payment can drop your score by 50 to 100 points depending on where you start. Utilization matters too, and since these cards often come with low limits, a $500 balance on a $600 limit is an 83% utilization ratio, which will hurt your score significantly. Keep your reported balance below 30% of your limit, ideally under 10%, if credit score improvement is your goal. The account also shows up as an open tradeline, which helps average account age. For someone building credit from scratch, a Comenity Bank card can be a legitimate tool because other issuers tend to decline those applicants. Just understand the tradeoff: easier approval comes with worse terms. It is a bridge, not a destination.
When to Walk Away
If you have the option to use a rewards card from a mainstream issuer with a reasonable APR, lower utilization impact, and cash back or travel points you can actually use, take it. The Victoria's Secret card is niche by design. It works best if you shop at Victoria's Secret or Bath & Body Works frequently and pay the balance in full every month. If you carry a balance, the rewards are effectively taxed away by interest charges. The card is not worth it for anyone who intends to finance purchases over time. There are better products for that situation, even if the approval odds are lower.