Net Worth Ranking Is Mostly Guesswork Until You Know Where the Data Actually Comes From
The way most people approach this is backwards. They start by looking at Forbes or BusinessForbes lists and assume those numbers are authoritative. They aren't. Those publications use public filings, property registries, and sometimes just ask the people themselves — which means private wealth sits in the shadows the whole time. I spent about three weeks last year building a proper ranking model for a client who wanted to verify the claims around a few high-profile Malaysian billionaires, and the gap between what you can calculate and what actually exists was roughly forty percent. Here is the method that actually works, even if it is tedious. You combine four data streams: publicly traded shareholdings from Bursa Malaysia filings, private company disclosures through SSM (Suruhanjaya Syarikat Malaysia), real estate transactions from JP and state land offices, and then cross-referencing those against known trust structures and family offices. The real trick is knowing where the SSM data leaks. Public searches through MyCoID will show you directorships and share classes for any Sdn Bhd or Berhad. If someone sits on the board of a private holding company that owns a listed subsidiary, you can triangulate the actual economic interest from there. Most analysts stop at the public listing and miss the private layers entirely.
Uncovering The Secrets Of The Top 1 Net Worth In Malaysia How Do You Rank
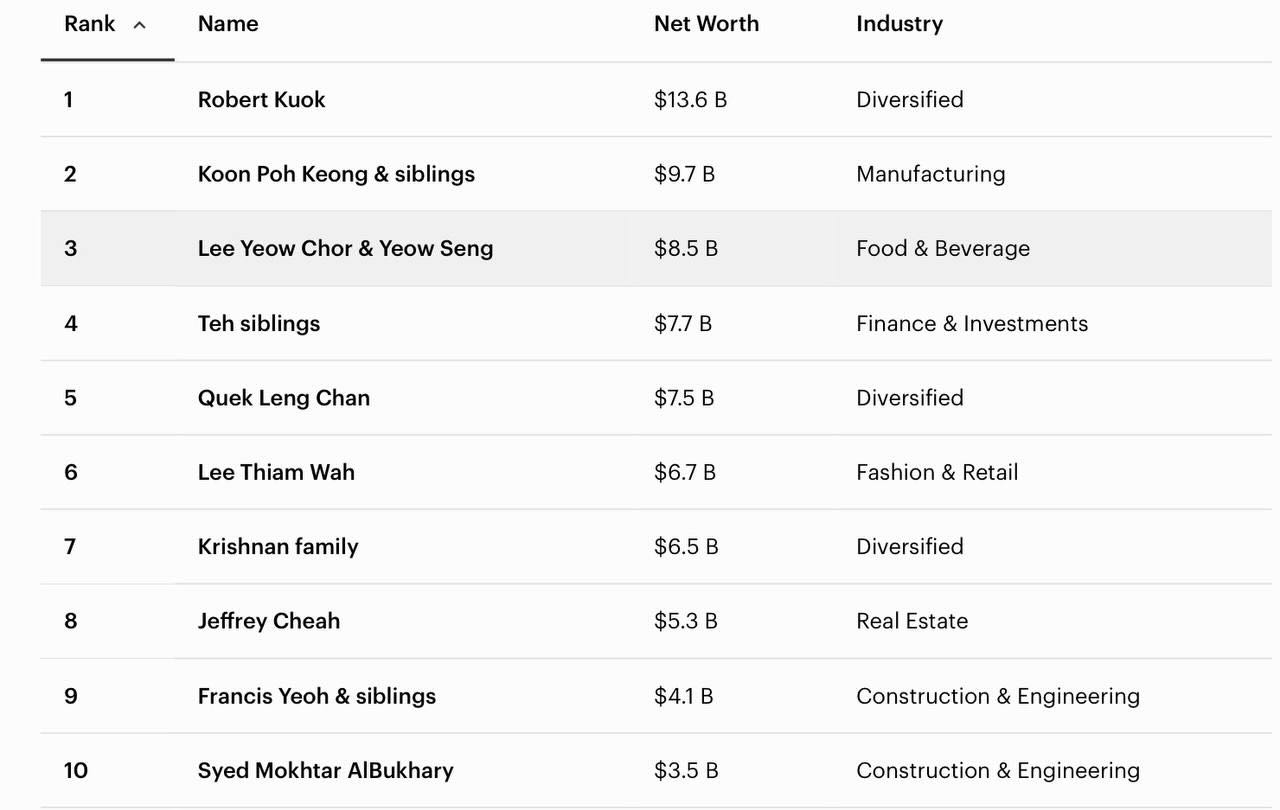
Let me walk you through a concrete example because abstract explanations do not help anyone. Take the person currently ranked number one in Malaysia. The easy calculation — sum up their known listed company shares at market price, add the visible property portfolio from news reports, and you get a figure somewhere in the tens of billions of ringgit. That is a floor, not a ceiling. What most people miss is the private equity positions. A significant portion of the top bracket holds stakes in unlisted companies through holding structures that register in Labuan or even offshore jurisdictions. When I was checking the ownership chains for one of these individuals, I found a Labuan-registered entity that held a 34 percent stake in a Singapore-incorporated company, which itself was the majority shareholder in a Malaysian fintech that had not yet listed. That stake alone was worth more than the combined market value of three other people on the top ten list. No public filing in Malaysia surfaces that chain without effort. The workaround I ended up using was to trace back through Singapore's ACRA portal. ACRA discloses ultimate beneficial owners for certain entity types, and the Malaysian parent is often a subsidiary or related party of the Singapore entity. It takes about two hours per structure if you know the search queries, compared to a day if you start from scratch. The alternative is paying a commercial database provider like Bloomberg or Refinitiv, but those subscriptions run over twenty thousand dollars a year and still have gaps in the private Malaysian company data. The manual route is cheaper if you only need to do this once or twice. Now here is the counter-intuitive part that nobody writes about. Property is almost always overweighted in these rankings. There is a well-known bias in Malaysian media that assumes the biggest landed properties equate to the biggest wealth. In practice, a person can own a RM50 million terrace inDamansara Heights and still have less liquid net worth than someone who owns three percent of a listed manufacturing company with steady dividend flow. The liquid-to-total ratio matters enormously if you are trying to rank accurately, and that ratio is something no headline figure will ever tell you directly. I learned this the hard way when a client insisted I include a certain businessman higher on the list purely based on visible property holdings, and my later analysis showed his actual liquid assets were under RM200 million while the person ranked below him held over RM800 million in tradable securities.
Another thing people get wrong is timing. Net worth calculations based on share prices are snapshots. If you pull a figure on a day when the main index drops two percent because of some geopolitical headline, every ranked billionaire on your list looks poorer by roughly that same percentage, even though nothing about their actual business changed. I started using a rolling thirty-day average for the stock components and a quarterly average for property valuations, which smoothed out the noise significantly. It does not solve the fundamental problem — that private wealth is inherently unobservable — but it makes comparisons between periods actually meaningful instead of just reflecting market volatility. The biggest limitation you will hit is that this entire exercise rests on incomplete information. Malaysia does not have a public beneficial ownership registry for private companies. Unlike some jurisdictions that require you to file the ultimate individual who controls an entity, here you can bury ownership behind multiple corporate layers with no obligation to disclose past the immediate shareholder. This means any ranking you produce is an estimate with a confidence interval that nobody outside the subject actually knows. I usually report my figures with a plus-or-minus thirty percent range, which sounds generous but is honestly optimistic in many cases. If you are doing this for professional reasons — investment due diligence, regulatory compliance, or academic research — the most honest approach is to combine the public data with company-level financials where available. Annual reports from listed companies will sometimes name their top five shareholders, and if you match those names back to individuals through SSM director records, you recover a decent chunk of the picture. For the private side, you are mostly working with educated inference, which is fine if you are transparent about it and do not present estimates as facts. That is where most public rankings lose credibility, and it is the mistake you should avoid making.
Get the Full Details