Where The Account Number Actually Lives On A Cheque
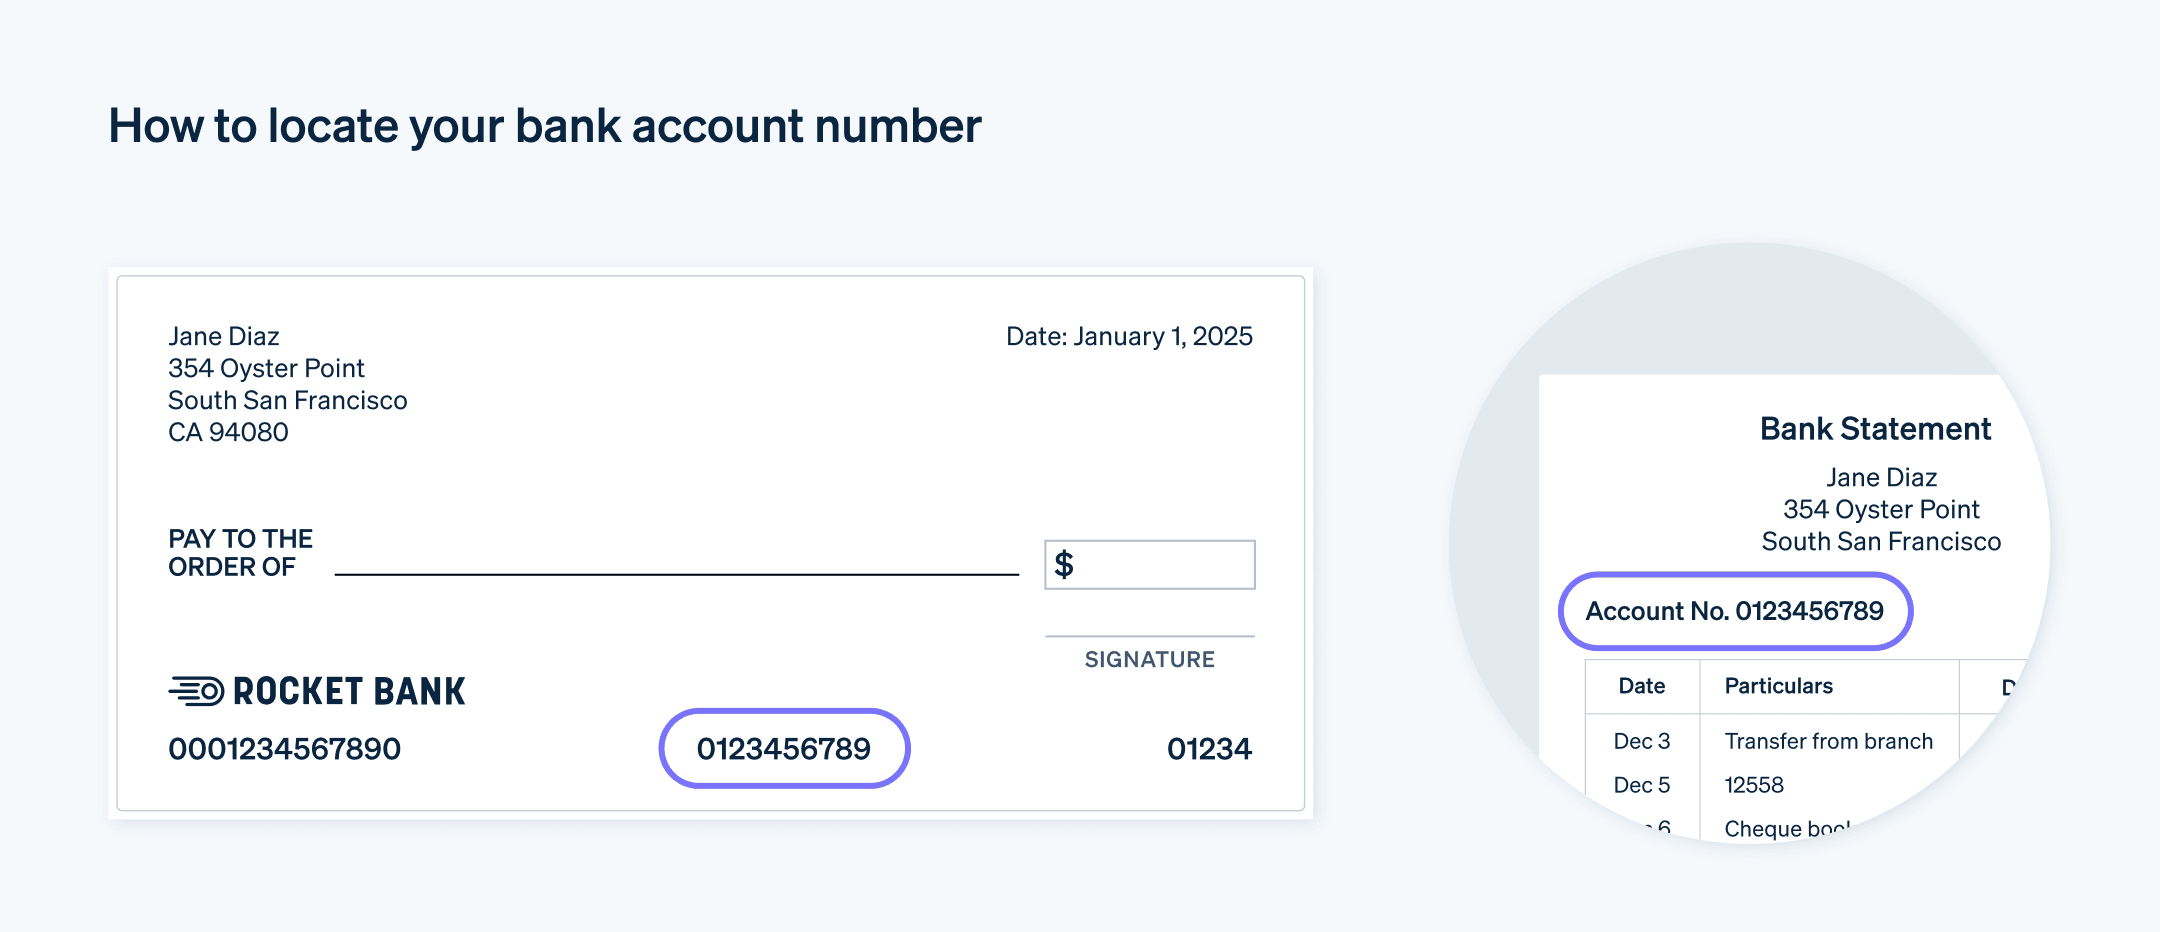
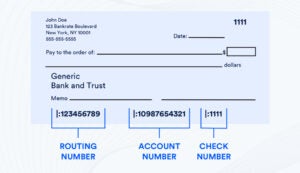
The account number on a standard cheque is almost always encoded within the MICR line at the bottom. That's the string of numbers printed in a special font—Magnetic Ink Character Recognition—that runs across the lower edge. For most cheques in North America, it sits between the routing number and the cheque serial number. Specifically, it's typically the second or third grouping of digits in that bottom line, depending on how your bank formats it. Here is the practical breakdown. Look at the MICR line at the bottom of your cheque. It will have three groups of numbers separated by special symbols. The first group is the routing transit number (9 digits). The second group is usually your account number, and the third is the cheque number. That's it. There is no hidden code. The formatting is standardized by the ABA and E13B specifications, and banks have used this layout for decades. I've seen people stare at cheques for ten minutes trying to find something that isn't there. The account number is just printed right there in plain text on that bottom line. In the US and Canada, the layout is:
Routing number (9 digits) | Account number (variable length, usually 8 to 12 digits) | Cheque number (4 to 6 digits) The symbol between the routing and account number looks like a tiny horizontal line with little upward and downward arrows at each end—this is the transit symbol. Between the account number and cheque number is a dash symbol. If you need to confirm which digits are yours versus the cheque number, count backwards from the end. The last group is always the cheque number. Everything before that symbol is your account number. There is one edge case I ran into recently that trips people up. A client sent me a Canadian cheque where the account number wasn't the obvious middle block. In some older Canadian institutional cheques, the account number gets split—the first few digits appear before the transit symbol as a branch identifier, and the full account number appears after it. I spent about twenty minutes convinced the number I was reading was wrong because it didn't match what the bank's online portal showed. The workaround was simple: call your bank and ask them to verbally confirm the full account number associated with that cheque. They can look it up by routing number and cheque serial in under a minute. Saves a lot of hair-pulling.
Another thing that catches people off guard: some banks now print the account number in larger, more prominent text near the top of the cheque itself, above the MICR line. If your bank does this, you don't need to decode the bottom line at all. Check the upper left area. Some cheques even label it "Account No." in plain English. Not all of them do, and when they don't, you're stuck with the MICR decoding process. One counter-intuitive detail beginners miss: the account number length varies by bank and by country. US banks typically use 8 to 12 digits. UK sort codes and account numbers follow a completely different format—two groups of six digits separated by a forward slash. Australian cheques use the BSB code followed by a 6 to 9 digit account number. If you're working with international cheques, the MICR standard changes. Don't assume the North American pattern applies everywhere. A few practical notes on limitations. The MICR font is designed for machine reading, not human readability. The characters can look squished together, and low-quality photocopies often blur the transit symbols so you can't tell where one group ends and another begins. Handwritten or stamped cheques that obscure the bottom edge are basically unreadable for this purpose. In those cases, you need to pull the account number from your banking app or statement instead.
Get the Full Details

If you need the account number regularly, don't bother decoding cheques. Check your bank's mobile app—every major institution displays your full account number under the account details section. It updates in real time and doesn't require any physical cheque. This is usually faster than finding a blank cheque, printing one out, and then trying to read the MICR line. For verification purposes—like confirming a direct deposit setup or validating a wire transfer recipient—the MICR-derived account number is reliable as long as the cheque is legible and the bank follows standard formatting. I've processed hundreds of these over the years, and the error rate is low when you read the groups left to right and confirm the digit count against what your bank says is normal for your account type. If your cheque has unusual formatting, non-standard character spacing, or you simply can't distinguish the groups, the safest move is to contact your bank directly. They'll give you the exact account number in thirty seconds flat, and you won't have to wonder whether you misread a digit.