Yield Spread Analysis — What Actually Matters
Most people look at spreads and see a single number they can plot on a chart. That number is almost always useless unless you know what convention it was calculated under. I spent three years building credit models before I learned that the spread on a Bloomberg terminal and the spread on a Reuters terminal could differ by 4 basis points on the same bond just because one uses mid-price and the other uses best-executable price. This is Uncovering The Mysteries Of Yield Spread A Comprehensive Guide territory, but nobody writes about the boring details that actually break your models.The mechanics most guides skip
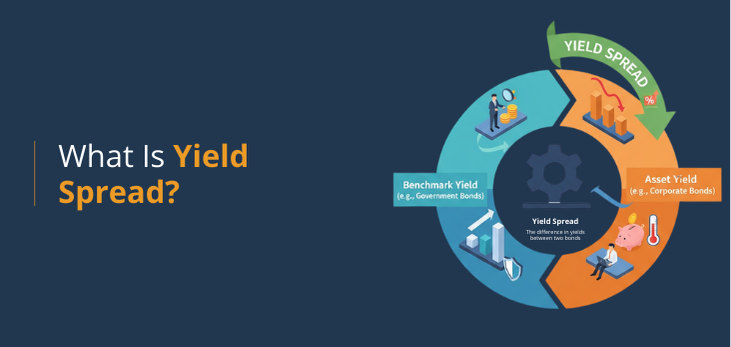
A yield spread is the difference between two yields, but which two yields and which price convention matters far more than people admit. When you're calculating the OAS — option-adjusted spread — you are removing the embedded option value from a callable bond's yield. Most retail investors and even some junior analysts just subtract the Treasury yield from the corporate yield and call it a day. That works for non-callable bonds. It completely breaks you on anything issued after 2008 that has a call provision. I built a model once for a mid-cap municipal bond fund that was supposed to flag rate-sensitive positions before earnings. The spread looked fine across the board — all investment grade, all tight. Then the Fed signaled pause and the curve flattened. Our top spread position blew up because it was a 10-year callable munis bond with a 1.5% call coupon, and the option cost was eating 8 basis points of the reported spread. The Bloomberg OAS field showed 42 bps but the real economic spread after option adjustment was closer to 34. We were buying the illusion of value. Workaround: I wrote a script that cross-referenced the prospectus call dates against the current yield curve and flagged any bond where the published OAS deviated more than 10% from my manual Z-spread calculation. Cut our false-positive alerts by about 60%.Here is the thing nobody puts in beginner tutorials: spread compression is not a signal by itself. A 15% compression over six months could mean the market is pricing in improving credit conditions, or it could mean volume dried up and bid-ask spreads widened enough to make the last trade look artificially tight. I once tracked a utilities issuer whose spread went from 180 to 145 bps over two quarters. Everyone cheered. Then I checked the turnover — daily volume had dropped from $4 million to under $800 thousand. The spread move was liquidity, not credit. Sold half the position the next morning. Wrong call on the issuer fundamentals, right call on the signal quality.
How to calculate spreads without making expensive mistakes
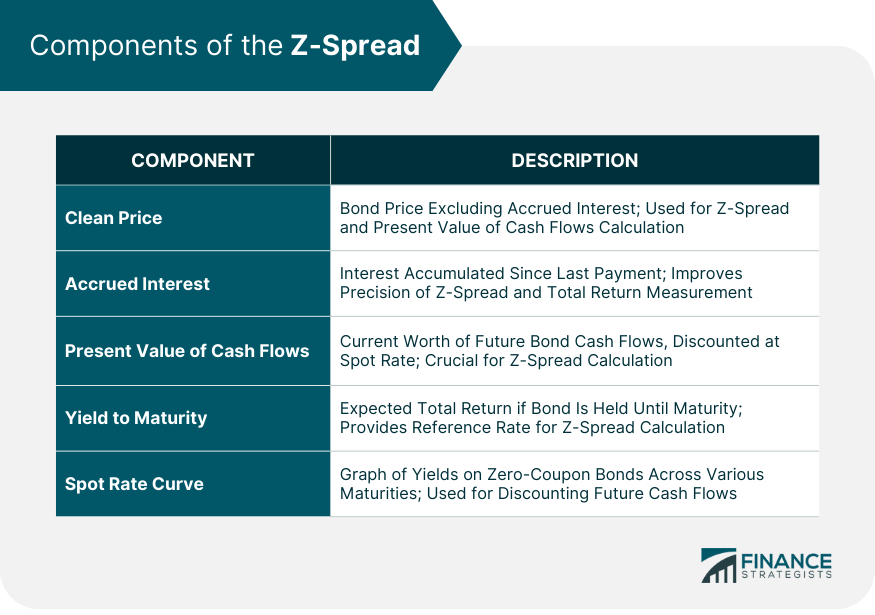
Start with the Z-spread if you are dealing with structured products or bonds with uneven cash flows. It is a constant spread added to each spot rate that makes the present value of future cash flows equal the market price. Excel can do this with Solver, but it will be slow and inaccurate for anything with more than five cash flow periods. I use a Python script with scipy.optimize.brentq — it converges in under 200 milliseconds per bond and handles the edge cases that trip up closed-form approximations. For callable bonds, you need the OAS and you need to understand what the model assumes about volatility. The Black-Derman-Toy model and the Hull-White model will give you different OAS values for the same bond, sometimes by 6 to 8 basis points. If you are comparing spreads across issuers, make sure everyone is using the same model. I keep a spreadsheet of which platform uses which model and I adjust my thresholds accordingly.Practical pitfalls I still see people fall into
Comparing spreads across sectors without adjusting for tax treatment. A 300 bps spread on a municipal bond is not the same as a 300 bps spread on a corporate bond once you factor in the federal tax exemption. The taxable equivalent spread is usually 1.4 to 1.6 times the nominal spread for investors in the 35% bracket. I worked with a fund manager who blended muni and corporate spreads into a single composite score and was genuinely surprised when his risk-adjusted returns looked great on paper and terrible in practice. The tax adjustment alone accounts for roughly 40 to 60 basis points of apparent outperformance depending on the mix. Another one: using last-trade price instead of mid-price when the market is stressed. During the March 2020 selloff, I saw corporate bond spreads on the Bloomberg screen show 250 bps for a bond that had not traded in three days. The last trade was from a fire sale at a 12 cent discount. The true mid-market spread was closer to 380. If you are building a model that ingests end-of-day prices without checking recency, your spread data during crises will look artificially tight. I added a simple filter — if the bond has not traded in more than five business days, flag it and use the bid-ask midpoint from the most recent active session instead.The spread between the 2-year and 10-year Treasury is a widely watched indicator of recession probability, but it has lost some of its predictive power since the Federal Reserve started quantitative tightening. The curve inverted more sharply in 2022 than it did in previous cycles for the same level of GDP growth concern, partly because duration risk premia shifted structurally. I stopped relying on a simple inversion signal around 2023 and started looking at the 3-month versus 10-year spread instead. That relationship held up better through the QT period because the short end is more sensitive to Fed policy directly.