Short-term notes payable is one of those accounting line items everyone glosses over until an audit asks why the number doesn't match the bank statement.
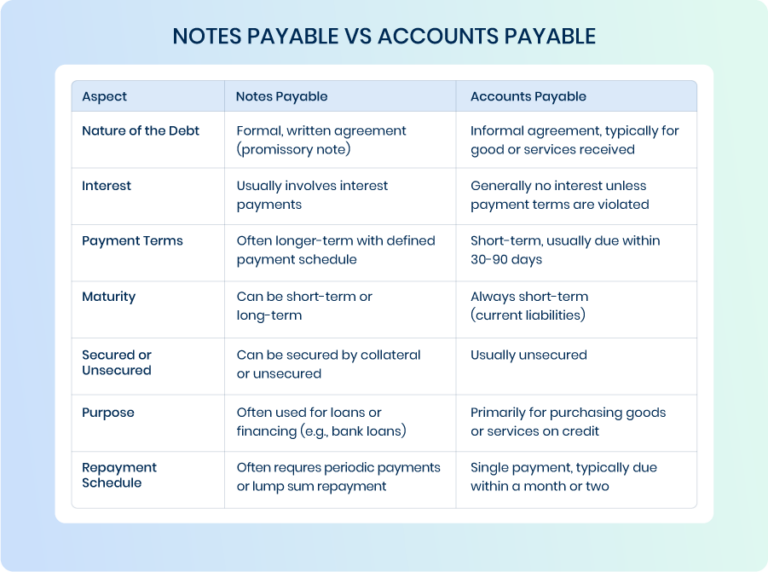
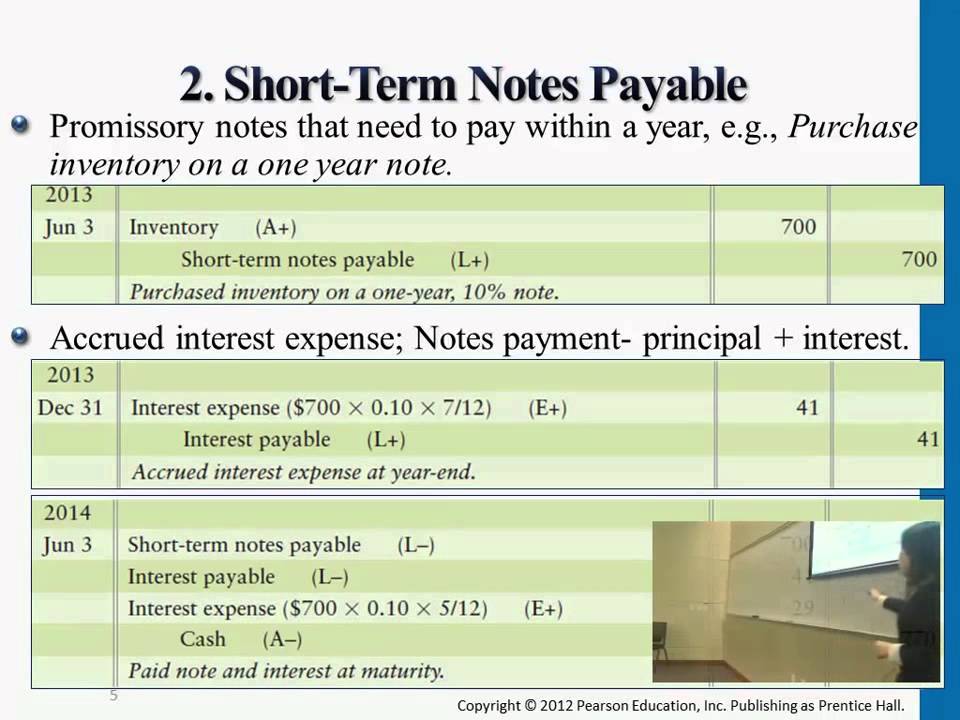
I've reconciled enough of these to know the usual suspects: accrued interest not being recorded monthly, maturity dates getting rounded incorrectly, and notes being classified as current when they've rolled over into long-term territory. The basics are straightforward, but the edge cases are where people get tripped up. A short-term note payable is a written promissory note where a borrower owes money to a lender with a formal interest rate and a defined repayment schedule. It appears on the balance sheet under current liabilities when the maturity date is within one year. That's the definition your textbook gives you. Here's what it actually looks like in practice. You sign a note for $50,000 at 6% annual interest, payable in 180 days. The journal entry when you receive the cash is straightforward: debit cash, credit notes payable for the principal. But the interest accrual is where things get messy. You need to record adjusting entries every month for the interest that has accumulated but not yet been paid. If you skip this, your expenses are understated and your liabilities are incomplete.
I worked with a company once where the controller had been recording notes payable at face value without accruing interest monthly. When we caught it during a quarter-end close, the interest expense was off by roughly $1,200 across three notes. We corrected it with a compound adjusting entry, but the real problem was that they were using a 360-day year for some notes and a 365-day year for others. That inconsistency matters more than people think. It creates small discrepancies that compound over time and look suspicious to anyone reviewing the ledger. The formula for accrued interest is principal times rate times time. Time is the tricky part. You need to count the actual days the note has been outstanding. Some lenders use a 360-day banker's year, others use 365. Check the note agreement before you calculate anything. Assuming a standard year when the contract specifies otherwise will give you the wrong number every time. Here's a practical workflow that works for most situations. First, pull your notes payable subsidiary ledger and verify each note has a maturity date, interest rate, and payment schedule documented. Second, calculate accrued interest for each note as of the reporting date using the correct day-count convention from the contract. Third, post the adjusting entries. Fourth, reconcile the total notes payable balance plus accrued interest to your general ledger control account. This usually takes about 30 to 45 minutes for a small business with under ten notes. If you have more than that, you should be using an automated accrual tool instead of spreadsheet math.
One thing beginners consistently miss: notes payable can be renegotiated or renewed without being formally paid off. When a short-term note is rolled over into a new note with a maturity beyond one year, you need to reclassify it from current liabilities to long-term liabilities on your balance sheet. I've seen auditors flag this specifically because the original note agreement still said one year, even though the parties had verbally agreed to extend it. The documentation needs to match the economic reality, not just the paper trail. Another nuance involves discount notes. Sometimes a lender will deduct interest upfront, meaning you receive less cash than the face value of the note. The difference is recorded as a discount on notes payable, which gets amortized over the life of the note using the effective interest method. This affects both your cash flow presentation and your interest expense calculation. A $50,000 note with a 6% discount for 180 days means you actually receive about $48,500, but you still owe $50,000 at maturity. Your effective interest rate is closer to 6.25%, not 6%. Disclosure requirements are another area where shortcuts cause problems. Public companies need to disclose the terms, interest rates, maturity schedules, and any restrictions or covenants attached to their notes payable in the footnotes. Private companies don't always think about this, but if you're seeking a loan or preparing financial statements for a lender, they will expect that level of detail. Skipping footnote disclosures is one of the fastest ways to lose credibility with a reviewer.
Get the Full Details

The biggest bottleneck in handling notes payable manually is tracking multiple notes with different terms across different fiscal periods. Spreadsheet templates break down after about five or six notes. Once you hit that threshold, the risk of formula errors increases significantly. At that point, moving to accounting software with fixed asset and liability modules pays for itself quickly. I've seen firms reduce their monthly close time for this area from roughly four hours to under thirty minutes after switching to QuickBooks Online with the loan management add-on, though the exact time depends on how many notes you're carrying. There are also scenarios where notes payable simply don't make sense as the right instrument. If you're dealing with related-party transactions, the terms need to be arm's length or you'll run into transfer pricing issues. I encountered a situation where a company issued a zero-interest note to its owner. The IRS required imputed interest to be calculated using the applicable federal rate, and the company had to file amended entries and adjust their tax positions accordingly. It cost them more in professional fees than the interest would have been if they'd priced it correctly from the start. For anyone working through this, the most useful thing you can do is create a notes payable schedule. It should list each note, the origination date, the principal, the interest rate, the day-count convention, the accrual frequency, the maturity date, and the current status. Update it whenever a payment is made or a note is renewed. This single document will answer most questions that come up during review, audit, or internal analysis without requiring you to dig through journal entries.
The key takeaway is that short-term notes payable are simple in theory and moderately complex in practice. The complexity comes from the variations in day-count methods, the need for timely accruals, the reclassification rules when terms change, and the disclosure expectations. Get the basic mechanics right and maintain a clean schedule, and the rest follows naturally.