Understanding the Permian Basin From the Ground Up
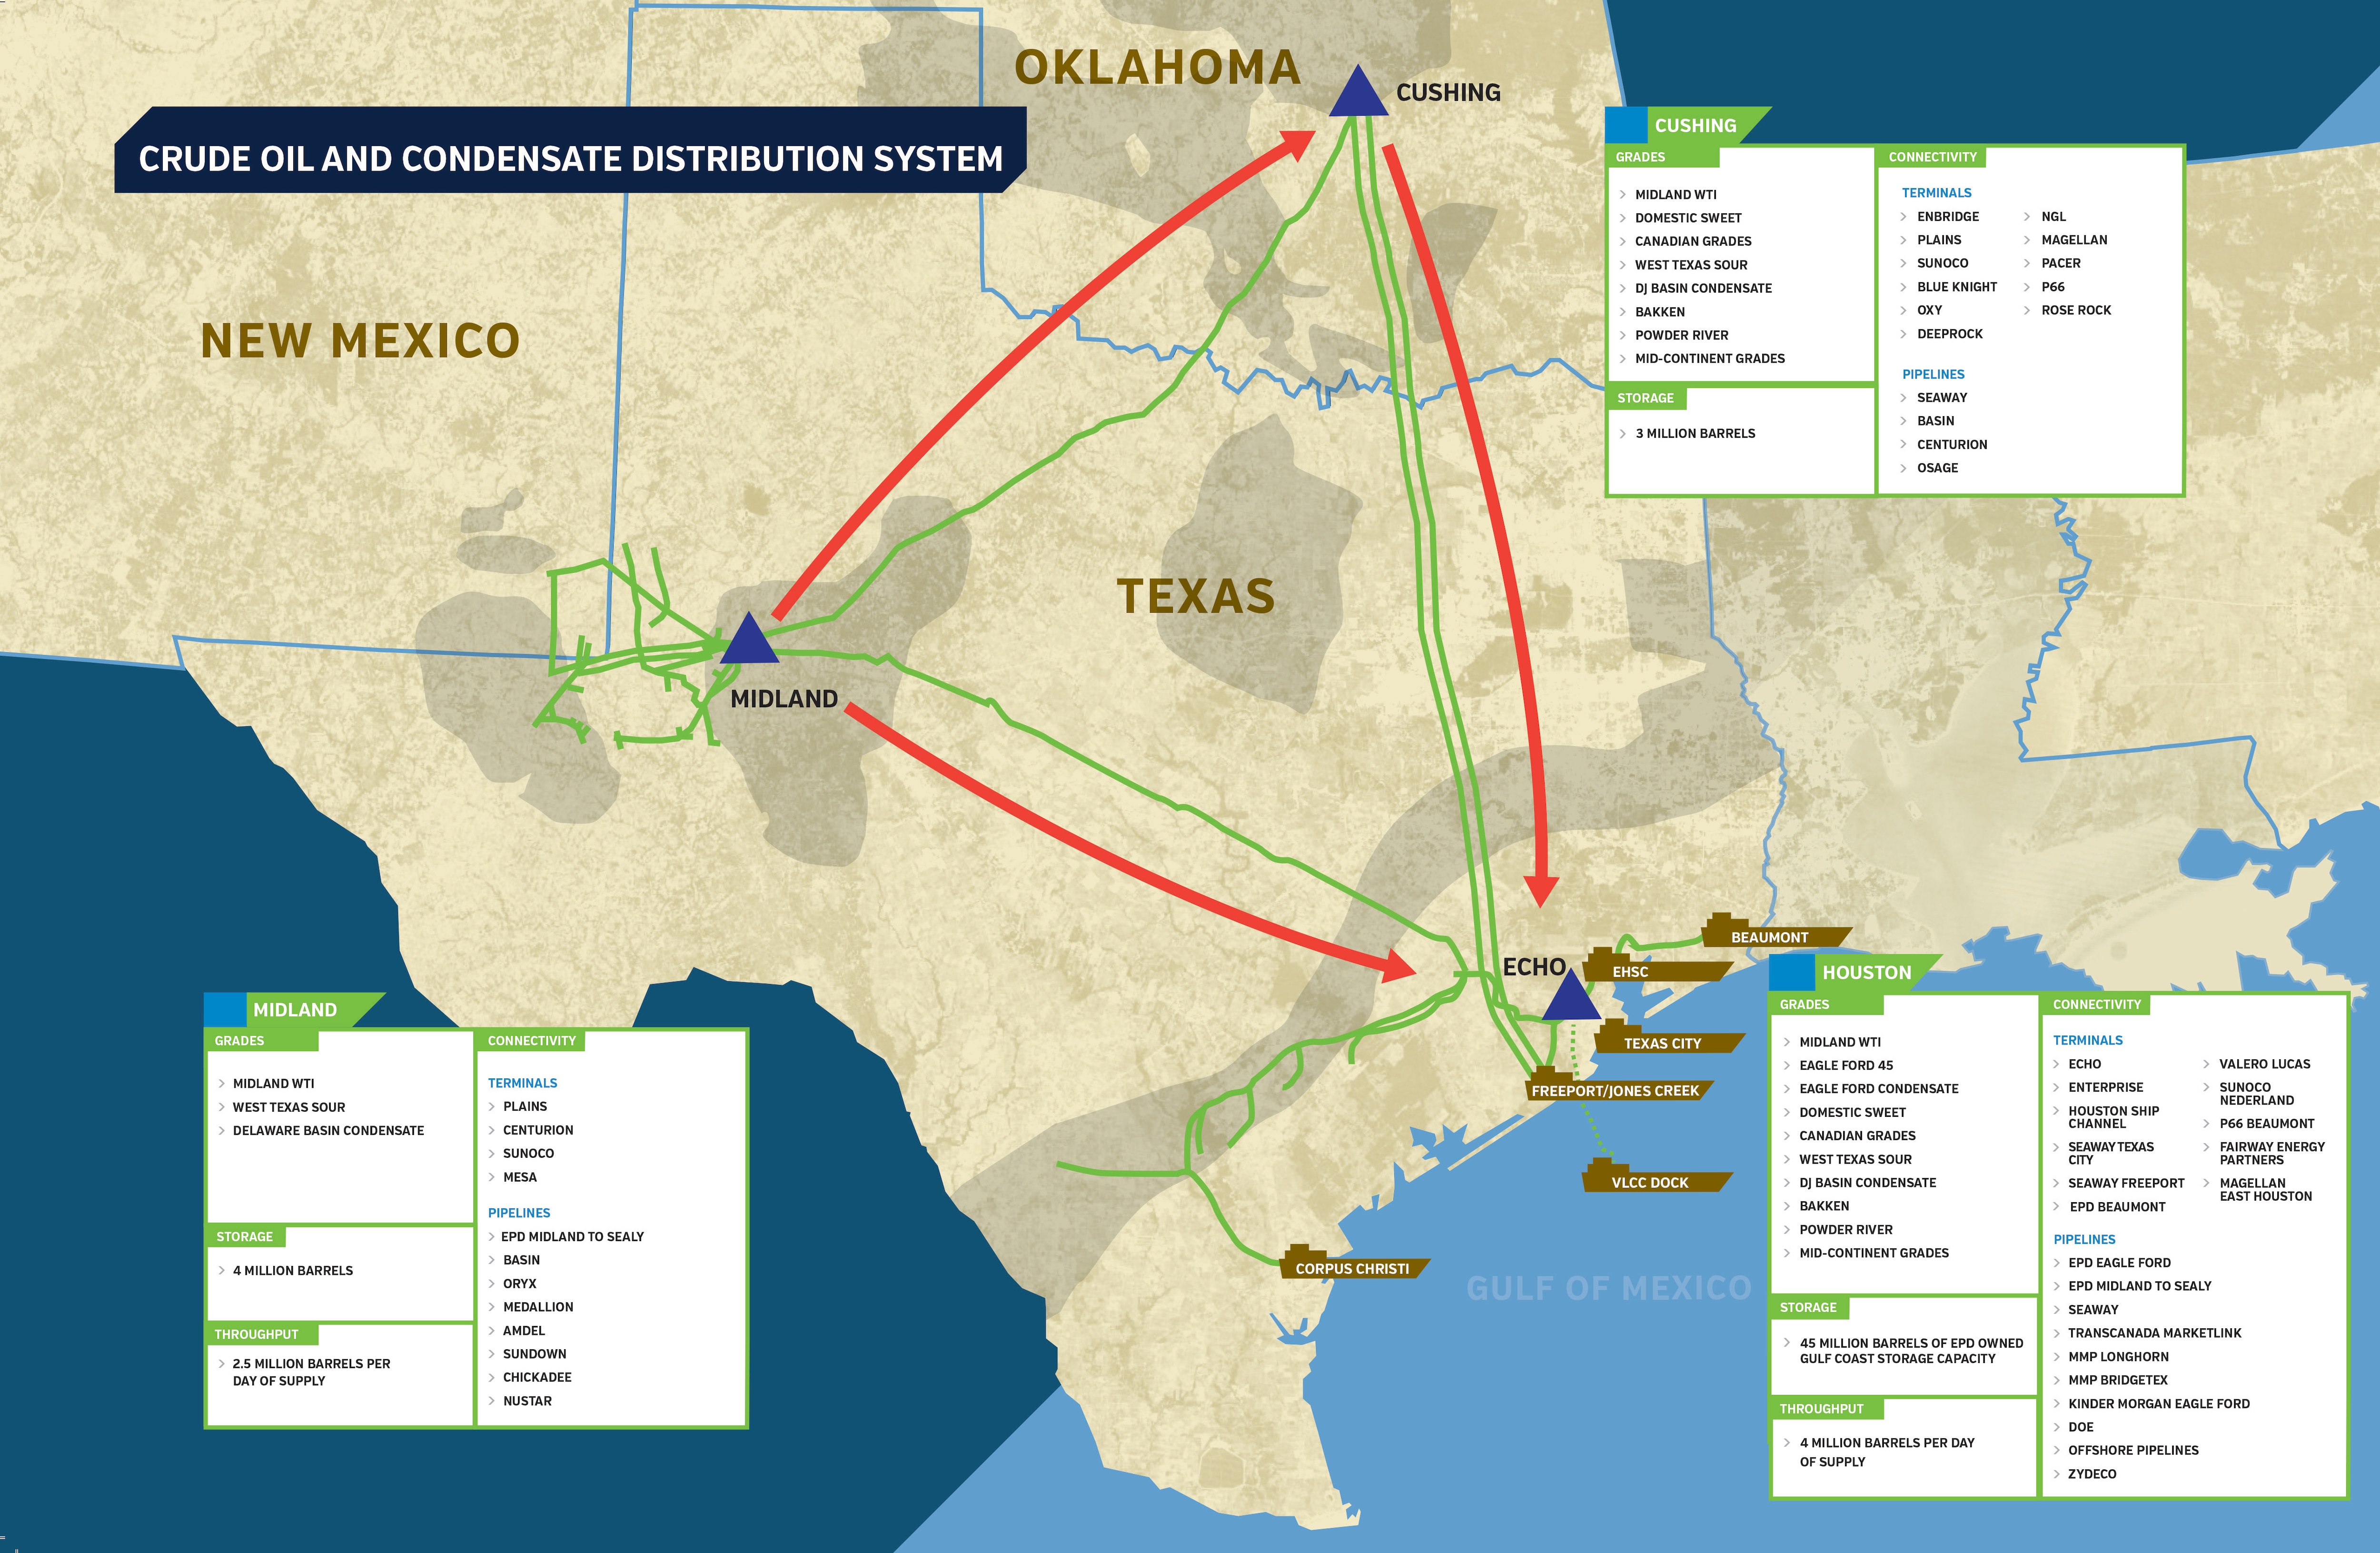
West Texas oil and gas isn't what it was twenty years ago, but it's still productive if you know how to read the subsurface. The Permian Basin covers roughly 75,000 square miles across West Texas and southern New Mexico, and within it are two main sub-basins—the Midland Basin to the east and the Delaware Basin to the west—separated by the Central Basin Platform. That's the basic geography. What matters more is what you do with the data once you're looking at it. I spent years working lease acquisitions and production tracking out of Midland, and the thing most people miss is that the easy money in West Texas isn't about finding new wildcat plays anymore. It's about re-evaluating existing production through better data and smarter engineering decisions. When I first started, everyone was chasing the Wolfcamp and Spraberry trends like they were unexplored frontiers. They aren't. You can pull public records from the Railroad Commission of Texas to map every well that's ever been drilled in the basin. What separates people who make money from those who don't is how they interpret what those records tell them about remaining pocket dynamics and pressure depletion patterns. Here's a practical example of what I mean. A few years back, a client of mine inherited a small working interest in a Delaware Basin property that had been sitting on the shelf for three years after an initial frack job underperformed. The operator had stopped spending on it, and everyone around him wrote it off. I pulled the pressure transient data from the well's production history and noticed something the operator missed—the reservoir pressure hadn't fully stabilized yet because the wellbore storage effects were masking the true drawdown behavior. We ran a simplified type curve analysis and found that the well was still in the transition flow period, not bound to a low-production future. After a remedial acid wash and a refracture with higher proppant load, the well came back to roughly 60 percent of its original rate. It turned a $200,000 liability into something that paid for itself within fourteen months. The property wasn't dead. Nobody had just looked at the right data.
Data sources you actually need to use: The RRC (Railroad Commission) publishes weekly and monthly production reports that are free and downloadable. Don't skip the unitized field data—they'll show you depletion trends across entire fields, not just individual wells. The EIA also publishes Permian basin level data, though it's aggregated and less useful for specific properties. For lease-level detail, you'll want to pull Oklahoma Corporation Commission records too since some Permian acreage extends southward, though most of the action is Texas-side.
Working Interests, Royalty Interests, and Why the Split Matters More Than You Think
The mineral estate in Texas is severed from the surface estate more often than people outside the industry realize. You can own the minerals under a quarter section and have no idea there's a pad site on the surface above you. When you're evaluating a property, the first thing you need to confirm is whether the royalty interest you're looking at is a net revenue interest or a pure overriding royalty, because the tax treatment and your actual cash flow from production are completely different. A net revenue interest (NRI) carries a share of both the revenue and the operating expenses. An overriding royalty interest (ORRI) pays a share of revenue with zero operating expense obligation, but it usually doesn't extend past the primary term of the lease unless there's a shut-in royalty clause or actual production. I've seen buyers get excited about an ORRI that looked like a nice passive income stream, only to find out three years later that the well had been idle and the ORRI had expired because the lease never had a Pugh clause protecting the deep formations. The Midland Basin is layered with multiple productive formations—Wolfcamp, Bone Spring, Spraberry, Dean, and others—and a standard lease might only hold the top formation through secondary drainage. If the operator drills deeper and the ORRI doesn't cover those zones, your income disappears even though the well is producing like crazy. Counter-intuitive point: Most people assume a higher royalty percentage is always better. It isn't. A 20 percent NRI with high OpEx can pay you less than a 15 percent ORRI with minimal operating costs. Do the math on a per-barrel basis before you get seduced by the headline percentage. Factor in gathering fees, compression costs, water disposal charges, and separation expenses. Those deductions eat into an NRI faster than most people calculate.
Get the Full Details

Enhanced Oil Recovery and the CO2 Cycle
The Delaware Basin has significant CO2 EOR operations running, primarily through companies like Pioneer Natural Resources and Occidental. CO2 injection works by mixing with the crude oil underground, reducing its viscosity and allowing it to flow more easily to production wells. It's been going on in West Texas since the 1960s in the Yarell field near Pecos, and the technique has expanded dramatically since 2015 with the shale boom. The catch is that CO2 EOR is capital-intensive upfront and has a long payback period. You're looking at tens of millions of dollars for compression infrastructure, CO2 sourcing, and injection well networks before you see incremental production. But once it's running, the decline curves are flatter than conventional wells. A typical EOR well in the Permian might produce for 20 to 30 years at a stable rate instead of the steep hyperbolic decline you see on a horizontal frac job. That makes EOR acreage valuable for long-term holders who don't need quick returns. I ran into a situation where an investor was evaluating CO2 EOR acreage and only looked at the stated incremental oil production numbers from the operator. He didn't factor in the CO2 cost per barrel of injection, which varies depending on whether the CO2 is naturally sourced or synthesized. Natural CO2 comes from Texas panhandle fields and costs less to transport, while captured or synthetic CO2 adds significant expense. The net effect on his NRI was materially different once you subtracted the full CO2 cycle cost from the gross incremental revenue. We adjusted the model and the deal that looked like a home run at first glance turned into a marginal play that only worked at lower oil price assumptions.
Water Handling—The Hidden Cost That Kills Margins
Every barrel of oil produced from the Permian comes with several barrels of produced water. In some Delaware Basin wells, the water-oil ratio can exceed 10:1. That water has to be processed, treated, and either disposed of via injection wells or recycled for subsequent fracturing jobs. The cost of water handling is one of the biggest hidden operating expenses in West Texas, and it varies wildly depending on your location and proximity to disposal infrastructure. If you're evaluating a property, check the water disposal costs in the area. Some fields have plenty of Class II injection wells within a reasonable radius, which keeps hauling costs down. Others are miles from any disposal option, and trucking water can run you $2 to $5 per barrel depending on distance and fuel costs. Over the life of a well, that adds up to millions in operating expenses that directly reduce your NRI. I once reviewed a deal where the acquisition price was attractive on paper, but the property sat in an area with limited disposal capacity and rising water handling costs that were eating 40 percent of the gross revenue. The numbers only worked at $80 oil. At $60, the property was unprofitable.
Unitization and Pooling—Where Things Get Complicated
Texas has compulsory pooling statutes, which means if you own mineral interest in a drilling unit and the majority of the unit owners agree to drill, you can be forced into the unit even if you object. This is called compulsory pooling, and it's governed by the Railroad Commission. The state determines your minimum contribution to the well costs and your share of production based on your tract's proportion of the unit's total acreage. The problem is that the forced pooling ratio isn't always fair to small interest holders. In some cases, the unitization process can create a situation where your mineral interest gets pooled into a large unit but your royalty share gets diluted because the unit boundaries don't align cleanly with your tract. I had a client who owned a 1/16th royalty in a single quarter section. When that tract got unitized into a 640-acre spacing unit with eight other tracts, his effective royalty dropped to 1/128th because the unit included adjacent lands with larger mineral estates. He was producing from a well on his land but earning the same rate as someone who owned nothing but happened to sit on the edge of the unit. It's not illegal. It's just how the statute works, and it's something you need to model before you buy.
Re-evaluating Older Conventional Wells
Not all value in West Texas is in horizontal shale plays. There are thousands of vertical conventional wells in the Spraberry, Bonespring, and other formations that were drilled decades ago and have been underperforming their potential. Many of these wells were completed with minimal stimulation by modern standards—some were just open-hole or lightly fractured. The technology for fracture design, proppant selection, and fluid chemistry has improved dramatically since the 1980s, and re-treating these older wells can unlock significant additional reserves. I worked on a project where we identified a cluster of five vertical Spraberry wells that had been producing at declining rates for fifteen years. We pulled the original completion records, which showed simple hydraulic fractures with coarse sand and low pumping rates. Using modern microseismic data from nearby horizontal wells as a guide, we designed a remix job with finer proppant, higher fluid volumes, and a crosslinked gel system. Three of the five wells doubled their initial flow rates and extended their economic life by another eight to ten years. The total job cost was under $400,000 per well, and each well generated over $1.5 million in net revenue over the following three years. The key was having access to good geomechanical data from the area so you know which zones are still pressurized and which ones have depleted to the point where a re-fracture won't connect.
Where This Approach Fails
Not every underperforming well can be salvaged. If the reservoir pressure has dropped below the bubble point and there's no solution gas drive remaining, a refracture won't help. You might be stimulating a dead zone. Also, in areas with heavy water cut—above 80 or 90 percent—the economics of further investment are almost never favorable. The produced water cost alone will exceed the value of the incremental oil. Be honest about when a well is truly exhausted versus when it's just underperforming. The distinction matters. Another limitation is data availability. The RRC publishes production data, but the reporting lag can be two to three months for some fields, and historical data before 2010 is harder to piece together comprehensively. If you're evaluating a property based on outdated production curves, you might misjudge the depletion rate. Always cross-reference with downhole pressure data and pressure transient analysis when it's available, rather than relying on surface production numbers alone. The Permian Basin remains one of the most productive oil and gas regions in the world, but the window for obvious, low-hanging gains has closed. The opportunities now are in the details—re-evaluating existing assets with better data, understanding the real cost structure including water and CO2, and knowing when a well is worth saving versus when it's time to write it off. The market doesn't reward people who chase headlines. It rewards people who dig into the raw numbers and find what everyone else overlooked.