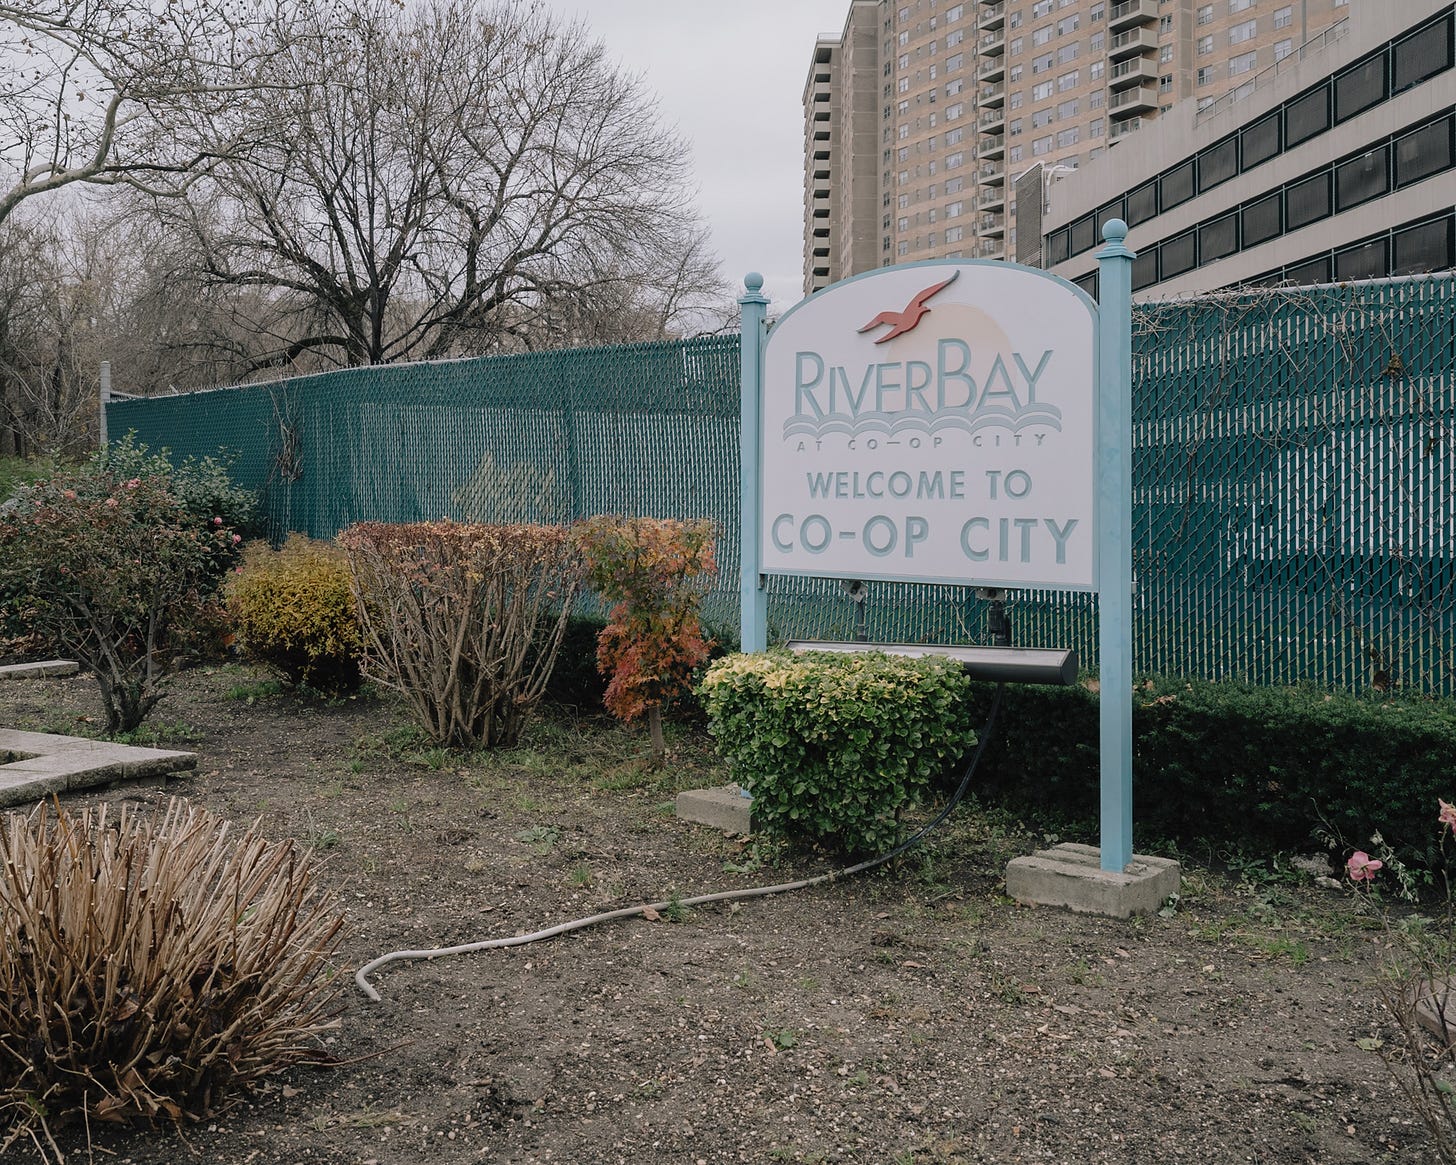
What Coop City Actually Is
Coop City is a cooperative housing development in the Soundview neighborhood of the Bronx. It covers about 1,000 acres and contains roughly 35,000 residential units across 69 buildings. About 55,000 people live there. It was built starting in the late 1960s by William Zeckendorf's company and opened in phases through the mid-1970s. It's one of the largest housing cooperatives in the United States, not just New York City. The way it works is different from a rental building or a traditional condo. You don't own an apartment. You own shares in a corporation that owns the entire development, and those shares come with a proprietary lease for a specific unit. Your monthly maintenance covers your share of the building's operating costs, property taxes, and mortgage. The board of directors — elected from residents — manages everything. That structure is what creates both the advantages and the friction.
Uncovering The Hidden Gem Of Coop City A Bronx Ny Community Like No Other
The reason people call it a hidden gem usually comes down to three things: price, community, and space. You can buy a two-bedroom unit there for significantly less than comparable co-ops in Manhattan or Brooklyn. The common areas are unusually large for the borough — wide sidewalks, multiple plazas, a recreation center, and more green space than most neighborhoods of that size have. And because the population is so dense and the design forces interaction at mailrooms, laundries, and bus stops, you end up knowing your neighbors faster than in almost any other NYC neighborhood. But here's what most guides leave out. The board approval process for buyers is rigorous. A typical purchase requires a minimum down payment of 10 to 20 percent, a solid financial profile, and an interview with the acquisition committee. I watched a buyer get rejected last year because their debt-to-income ratio was 38 percent when the board's cutoff was 35 percent. The unit was priced below market and sat on the market for six months after the rejection because the seller hadn't priced it with co-op financial hurdles in mind. That's a practical detail you won't find on StreetEasy.
How to Navigate Buying Into Coop City
Step one is getting pre-qualified before you look. Not pre-approved for a mortgage. Pre-qualified for a co-op share purchase. The financing is different — it's a share loan, not a traditional home loan. Some lenders specialize in this. Others don't. If you walk into a bank that only does conventional mortgages, you'll waste three weeks before anyone explains the difference. Find a co-op-literate broker or lender first. Then start looking. Step two is understanding the financials of the specific building. Coop City isn't a single entity with uniform finances. It's divided into multiple cooperatives within the larger development. Each building or cluster has its own board, its own maintenance fee, its own reserve fund status, and its own tax assessment. A unit in Building 10 will cost differently than a similar unit in Building 23. Request the last two years of financial statements and the most recent year-to-date figures. Look at the reserve fund balance relative to annual maintenance. If reserves are underfunded by more than 15 percent of annual operating expenses, flag it. That usually means a special assessment is coming. Step three is the flip tax. Coop City has a transfer fee — commonly called a flip tax — that runs between 1 and 2 percent of the sale price or the assessed value, whichever is higher. It goes to the cooperative, not the seller. Factor that into your cost calculation. On a $300,000 purchase, that's $3,000 to $6,000 you need to bring to closing beyond your down payment and closing costs.
Get the Full Details

Step four is the interview. The board will ask about your financial stability, your employment, your references, and sometimes your lifestyle. They want to know you can pay maintenance consistently and won't become a problem. Be honest. Don't hide a late credit card payment from five years ago — they'll find it in your credit report anyway. What they care about more than perfection is consistency. Steady income, manageable debt, and a track record of paying housing costs on time matters more than a perfect credit score.
What Life There Actually Feels Like
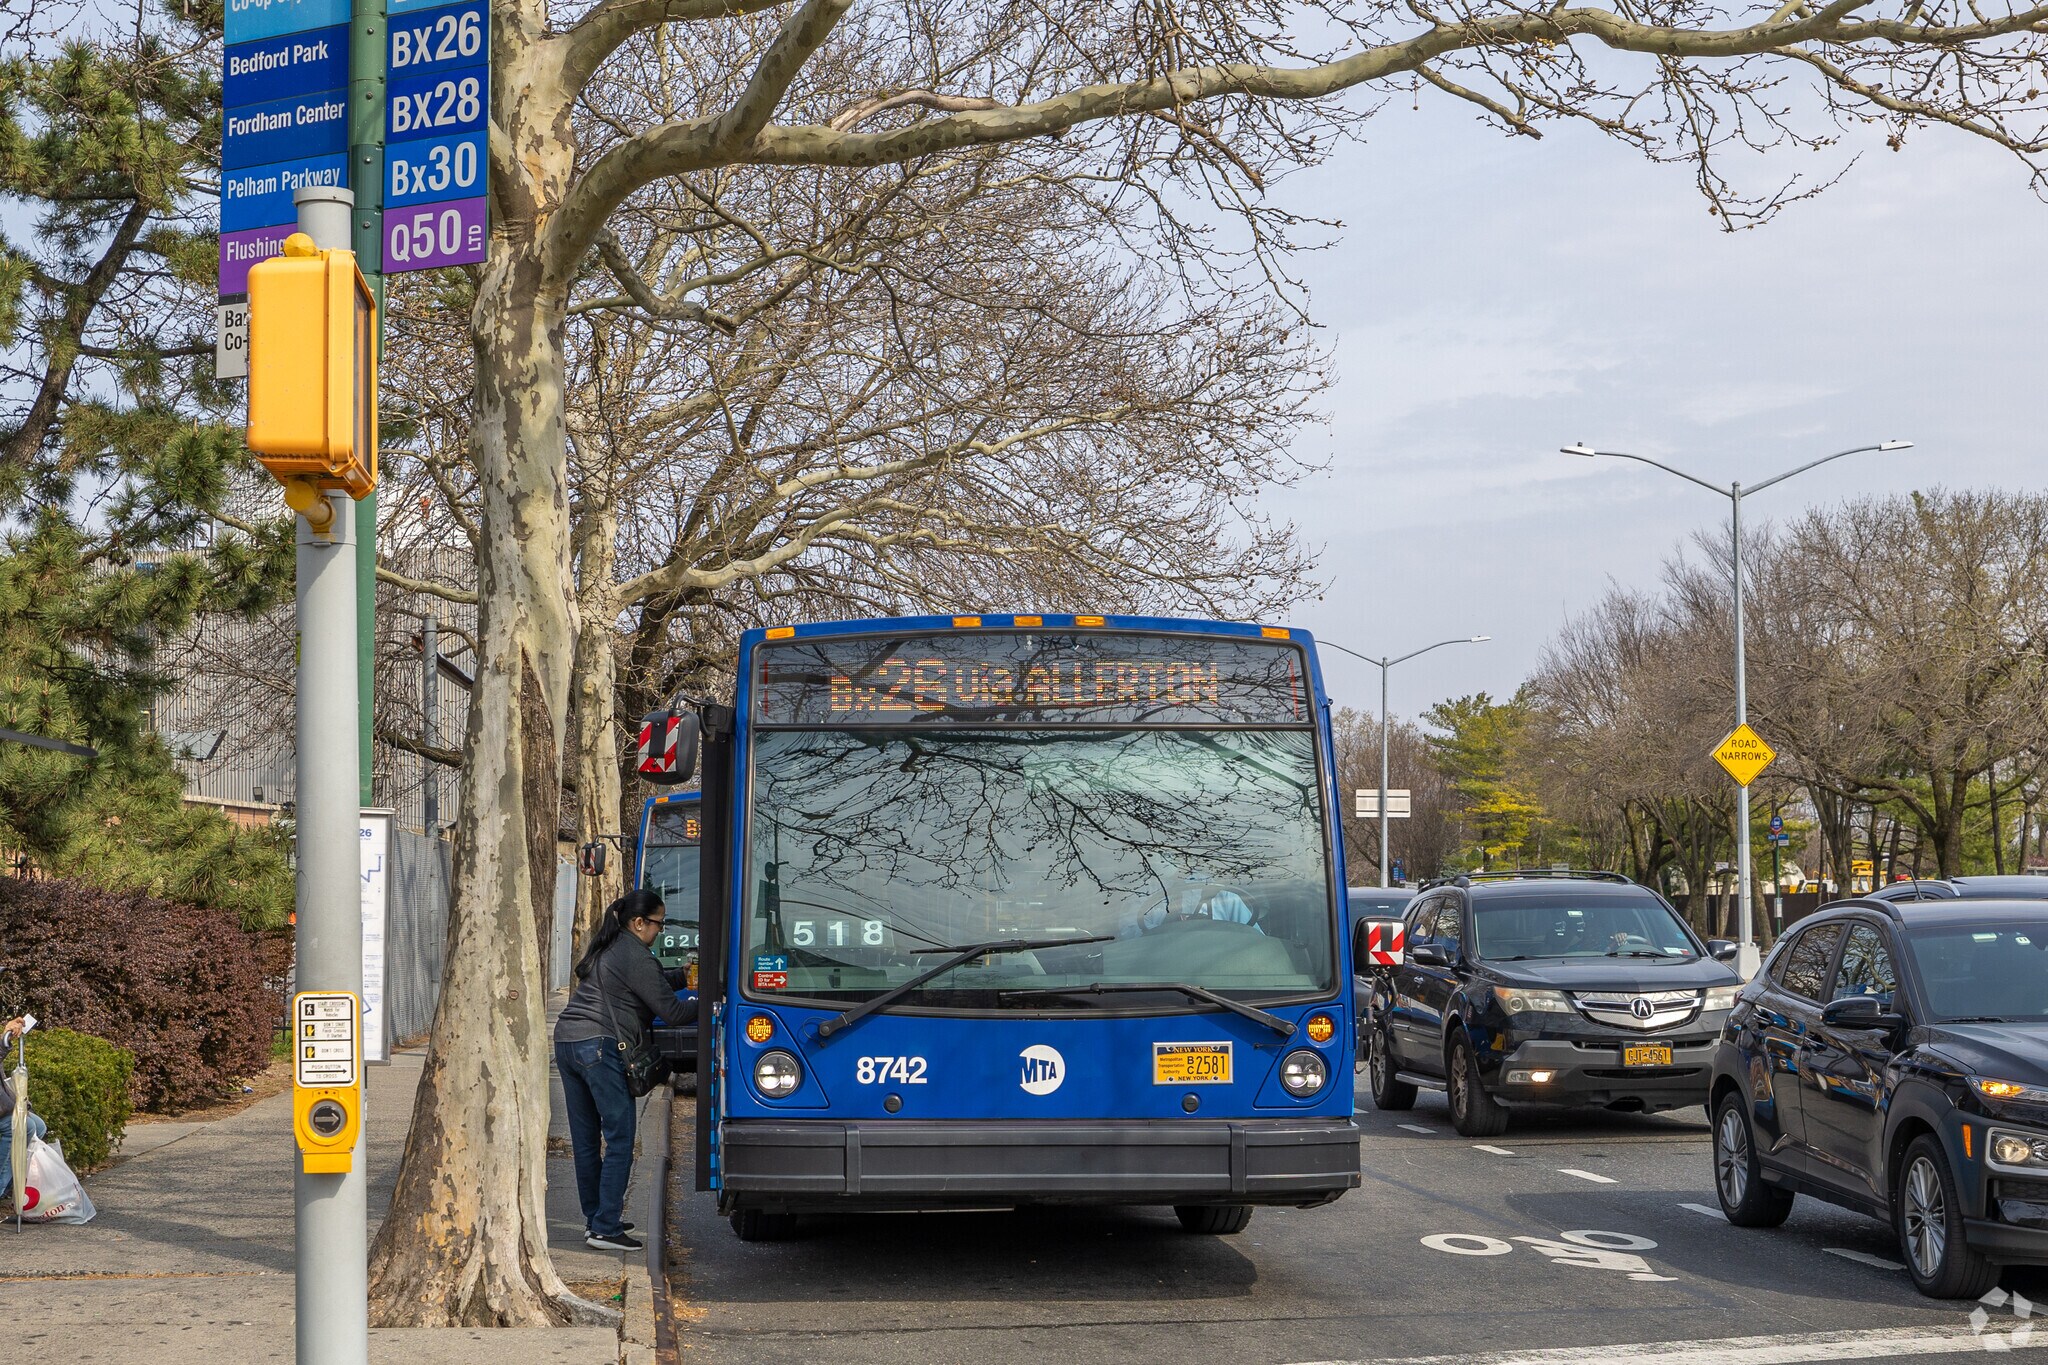
The layout is car-oriented in a way that surprised me when I first visited. Wide roads connect the towers, and parking is available but competitive. Most residents who work in Manhattan take the Bus Bx12 or Bx29 to the subway, or drive to the Bruckner Expressway. The 6 train at Baychester Avenue is the closest subway option for many residents, about a mile away in most cases. It's not walkable to the subway in the way Midtown residents expect walkability. The commercial corridor along Westchester Avenue has grown considerably over the last decade. You have grocery stores, pharmacies, banks, and a range of restaurants. It's not Upper West Side-level variety, but it's functional and improving. The real social infrastructure is internal — the community centers, the resident organizations, the block associations. If you join one of those, your experience changes dramatically. People who stay isolated in their units tend to report feeling disconnected. People who participate in building activities or the cooperative's governance report high satisfaction. I ran into a specific issue once that nobody warns you about. The maintenance fee includes heat and hot water, which is standard for New York co-ops. But Coop City's heating system is centralized and old. In January of a particularly cold year, several buildings had inconsistent heat because the boiler capacity couldn't keep up with a sustained freeze. Some floors were 68 degrees, others 58. The board responded by opening a warming center in one of the community rooms and distributing space heaters. It lasted four days. What I learned from that: check which building you're in, and whether the board has a documented emergency heating plan. Buildings with recent boiler replacements or upgrades were noticeably more comfortable during that event. It's the kind of detail that only comes up during an actual crisis.
Common Pitfalls
Underestimating the sublet restrictions. Many Coop City buildings limit how often you can rent out your unit if you need to relocate temporarily. Some require board approval for any sublet. If you anticipate needing to rent it out at any point, read the bylaws carefully before buying. I've seen people get stuck because they assumed they could sublet after two years and the bylaws actually required a full five-year ownership period before any sublet was permitted. Ignoring the special assessment history. Some buildings have had major assessments for roof replacement, facade work, or elevator modernization. These show up in meeting minutes and financial statements, but casual buyers often miss them. A $15,000 special assessment per unit is not unusual for older buildings in the complex. Factor it in. Assuming silence means peace. Coop City is loud. The density, the bus traffic, the playgrounds, the proximity to the Major Deegan Expressway — it's not quiet. If you're coming from a quieter part of the Bronx or from suburbia, the noise level is a real adjustment. Visit the unit at different times of day. Walk the block during evening hours on a weekday. You'll hear what you're getting into.

The Realistic Tradeoffs
Coop City is not for everyone. It's far from Midtown. The architecture is uniform — brutalist-influenced high-rises that some people find depressing and others find practical. The board can be slow to respond to requests. The application process is tedious and sometimes arbitrary. Property values appreciate more slowly than in many comparable NYC neighborhoods, though they've stabilized and improved since the early 2010s. What it offers in return is affordable homeownership in New York City, a strong sense of community among residents who engage with it, and a level of space that's nearly impossible to find elsewhere at similar price points. It works well for families, for first-time buyers who can't afford Manhattan, and for people who prioritize community and cost over prestige and location. If you want something closer to Manhattan with equal affordability, look at parts of East Harlem or Wakefield. If you want a newer building with amenities, look at private developments in Astoria or Long Island City — but you'll pay significantly more. Coop City occupies a specific niche. It's not a hidden gem for everyone. It's a hidden gem for the right person.