
Understanding Payment Options at Retail Stores
Kohl's has several ways you can pay, and understanding them helps you pick what works. I worked retail for years, so I've seen people get tripped up by payment terms more than anything else. Let me walk you through what actually exists. Kohl's doesn't offer a traditional weekly payment plan. What they do have is the Kohl's Card and sometimes third-party financing through Affirm. I used to work the register and watched customers ask about weekly payments constantly. The answer was always no, but there are alternatives. When people ask about weekly payments, they're usually thinking about budgeting. You spend $100 this week, $100 next week. It sounds manageable. Reality is different. Kohl's Card charges interest after the promotional period. Affirm splits payments over months, not weeks. Neither matches the mental model of "pay a little each week."
My experience with customers who wanted weekly payments fell into two groups. Some needed cash flow flexibility. Others just didn't understand how credit worked. The cash flow people usually ended up better off with a store card and paying it off monthly. The confused ones needed clearer explanations about minimum payments and interest. Here's what actually happens when you use Kohl's financing. You spend $500 on clothes. The promotional period might be 6 months no interest if you pay in full. Miss one payment, and retroactive interest hits. I saw this happen to a lady who thought she had a payment due on the 15th. It was actually the 5th. She lost her promo rate and got charged back interest from the purchase date. The workaround I learned was simple. Set up autopay for the minimum. Then pay extra when you can. It keeps your account in good standing and reduces total interest. Don't rely on remembering due dates. My own card payments autopay because I've missed too many times in the past.
Another thing nobody tells you about store cards. Using them affects your credit utilization ratio. If you have a $200 limit and spend $180, your utilization is 90%. That tanks your score. Spend $50 and it's 25%. Much better. I see people max out their Kohl's cards at holiday sales without realizing the credit damage. Affirm is different. They do installment loans at checkout. Three months, six months, twelve months. Fixed payments. No revolving debt. Some people prefer this because it's predictable. The downside is origination fees on some loans, and they report to credit bureaus either way. Here's the counter-intuitive part. Sometimes it's better to use a regular credit card and pay over time, rather than a store card or Affirm. Why? Because your regular card might have a lower APR, or rewards points, or better fraud protection. Store cards are designed to make money from people who carry balances. Their APRs are often 25% or higher.
Get the Full Details
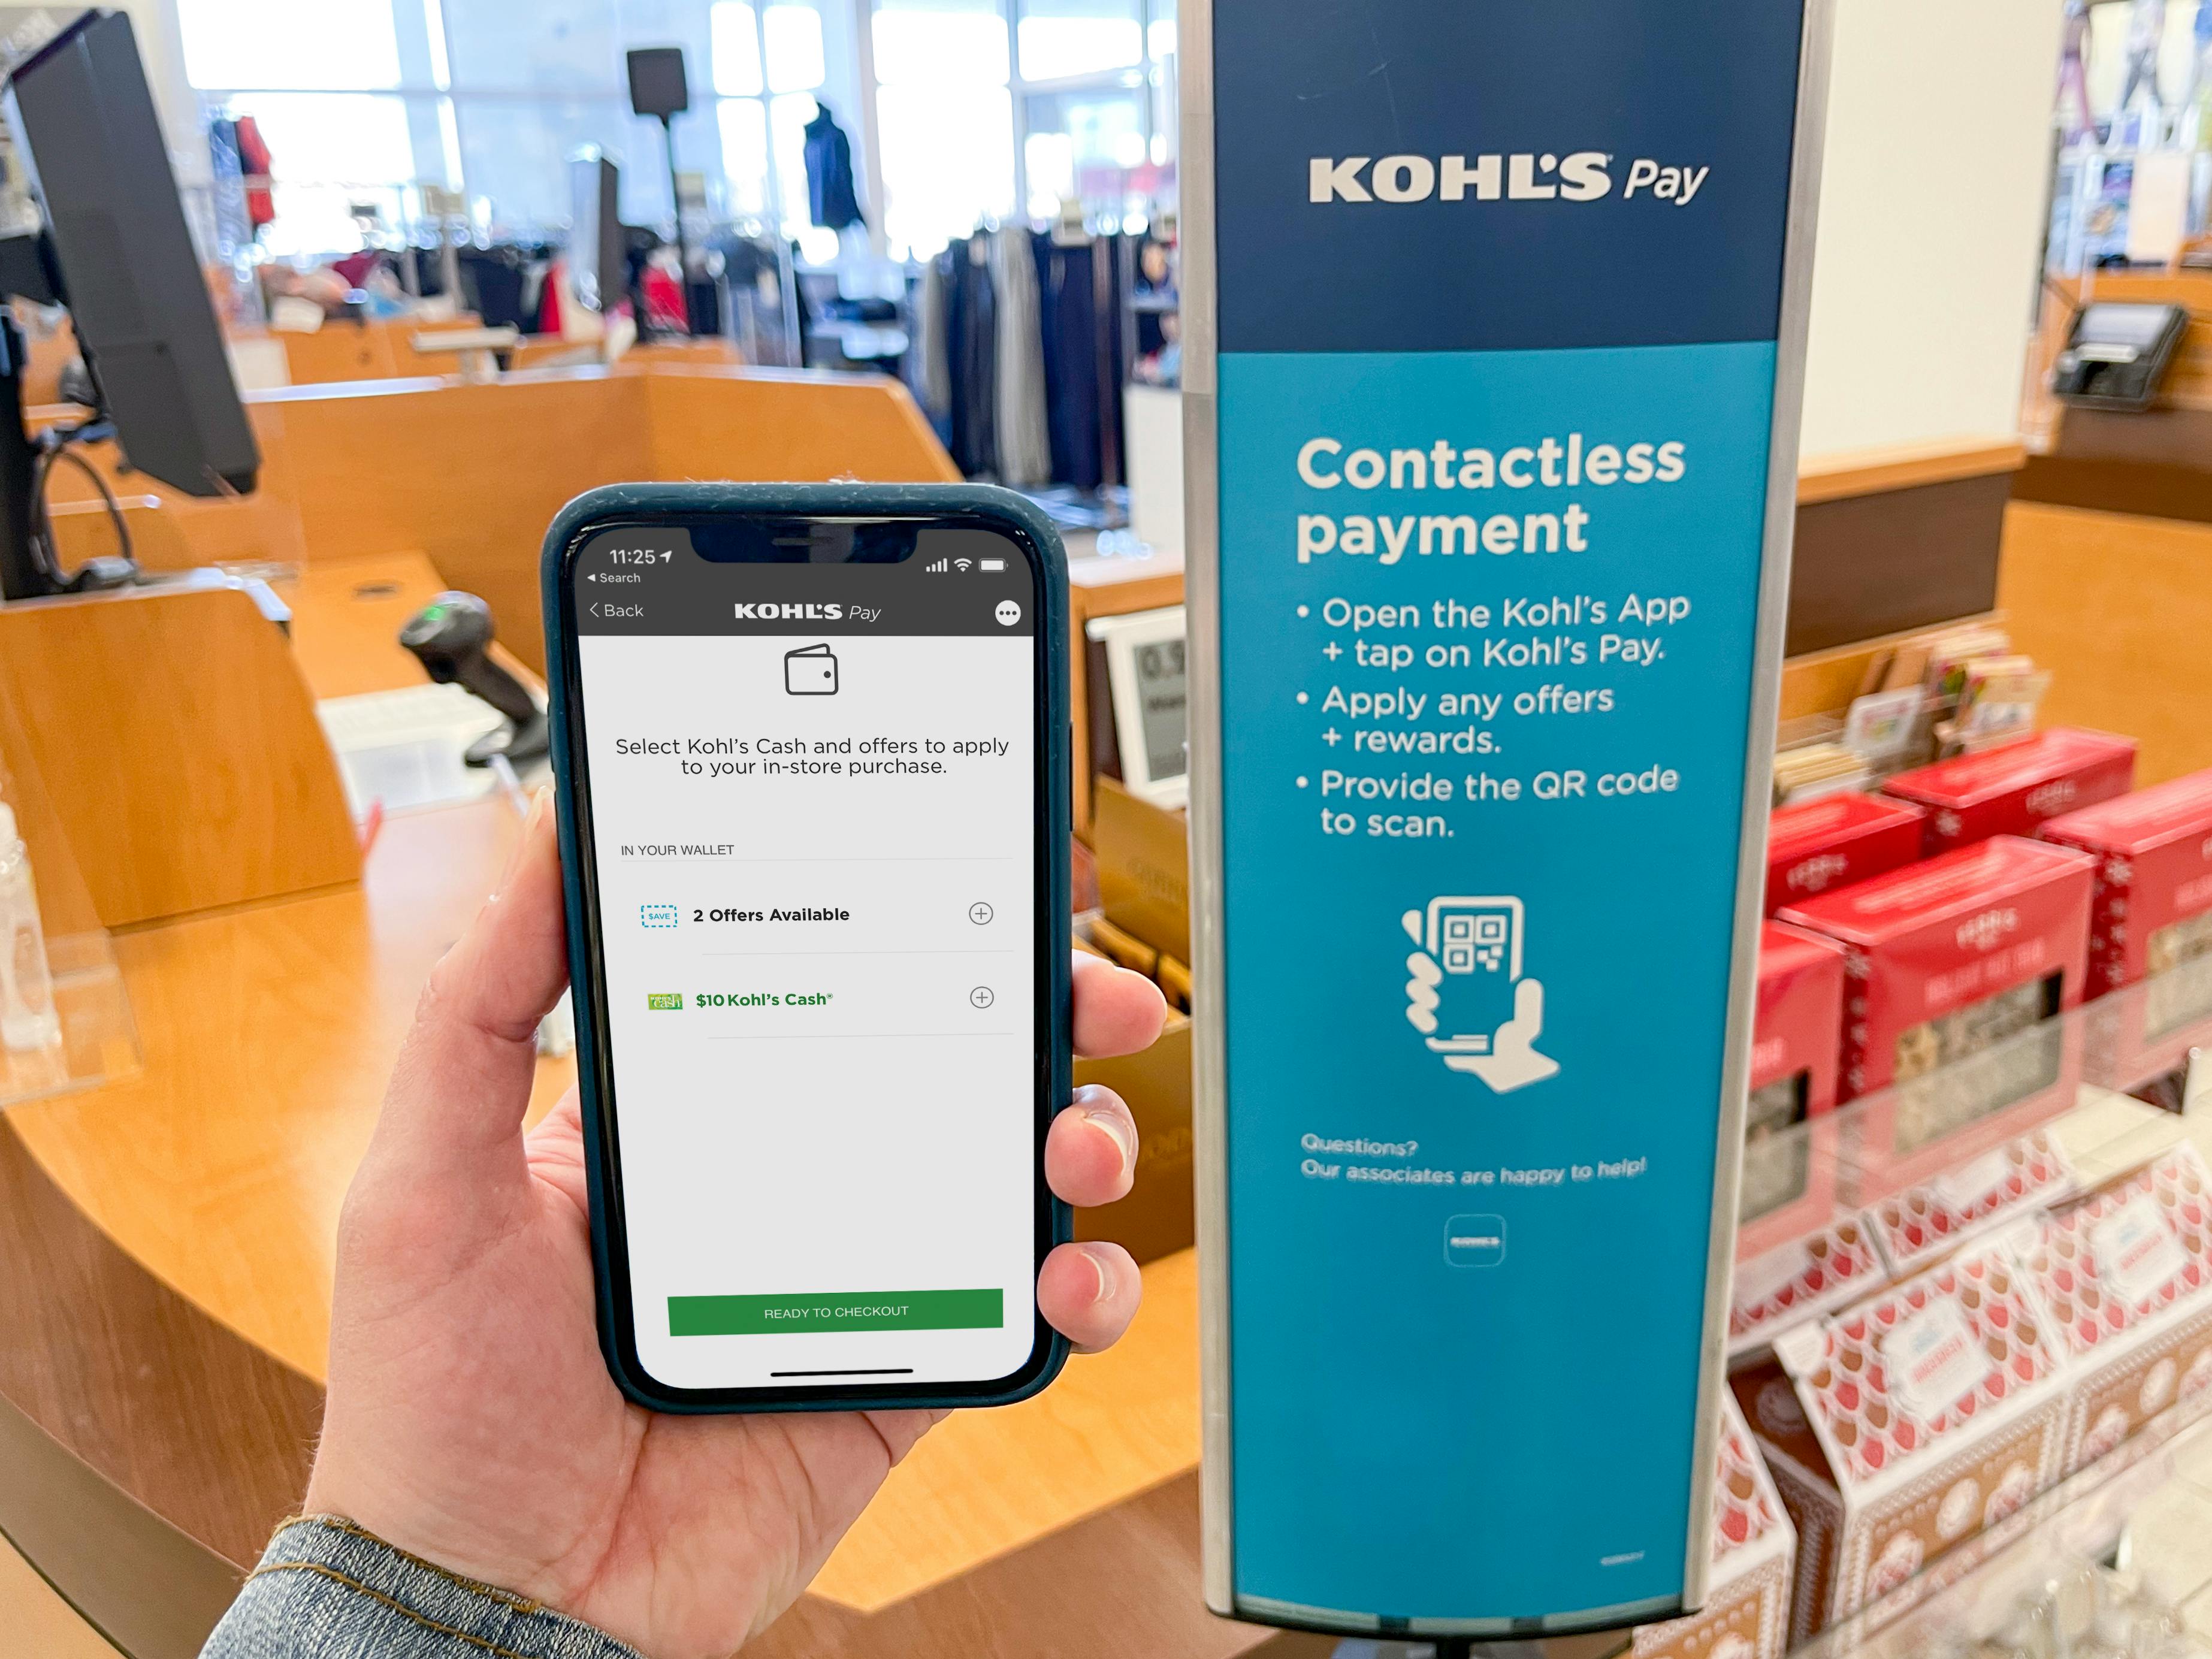
I once helped a coworker switch from Kohl's Card to a Chase card with 0% intro APR for 15 months. She had $800 she was paying down. With the Kohl's Card, she was paying interest on top of principal. With Chase, she paid zero interest the whole time. Saved maybe $60 in interest charges. Weekly payments aren't really a thing at Kohl's. You have revolving credit (Kohl's Card) or installment loans (Affirm). Neither is weekly. If you really want weekly budgeting, consider using a prepaid debit card loaded with a set amount each week. Spend only what's on there. No interest, no debt. The pitfall most people hit is thinking they can manage store credit easily. They don't. Interest accrues immediately after promos end. Minimum payments keep you in debt longer. I watched a guy pay off a $600 TV over three years with $30 monthly payments. He ended up paying $900 total. The math seemed fine when he started.
If you do use Kohl's Card, pay the full statement balance every month. Not the minimum. The full amount. That way you never pay interest. Treat it like a debit card, just with delayed payment. If you can't do that, don't use it. Simple as that. Another edge case worth mentioning. Kohl's sometimes offers special financing on big purchases like appliances. That's separate from the regular card terms. Read the fine print. "No interest if paid in full within 18 months" means exactly that. Miss one payment by a day, and you owe interest for the entire 18-month period calculated at the standard rate. I found the best way to handle this is writing down the promo end date on your calendar and setting a reminder two weeks before. Life happens. Bills get delayed. But if you know the deadline coming, you can plan around it.
Weeklies don't exist at Kohl's. Pick what fits your situation and read the terms carefully. Most problems come from not reading what you're signing.


