How To Access And Manage Your TD Auto Finance Account Online
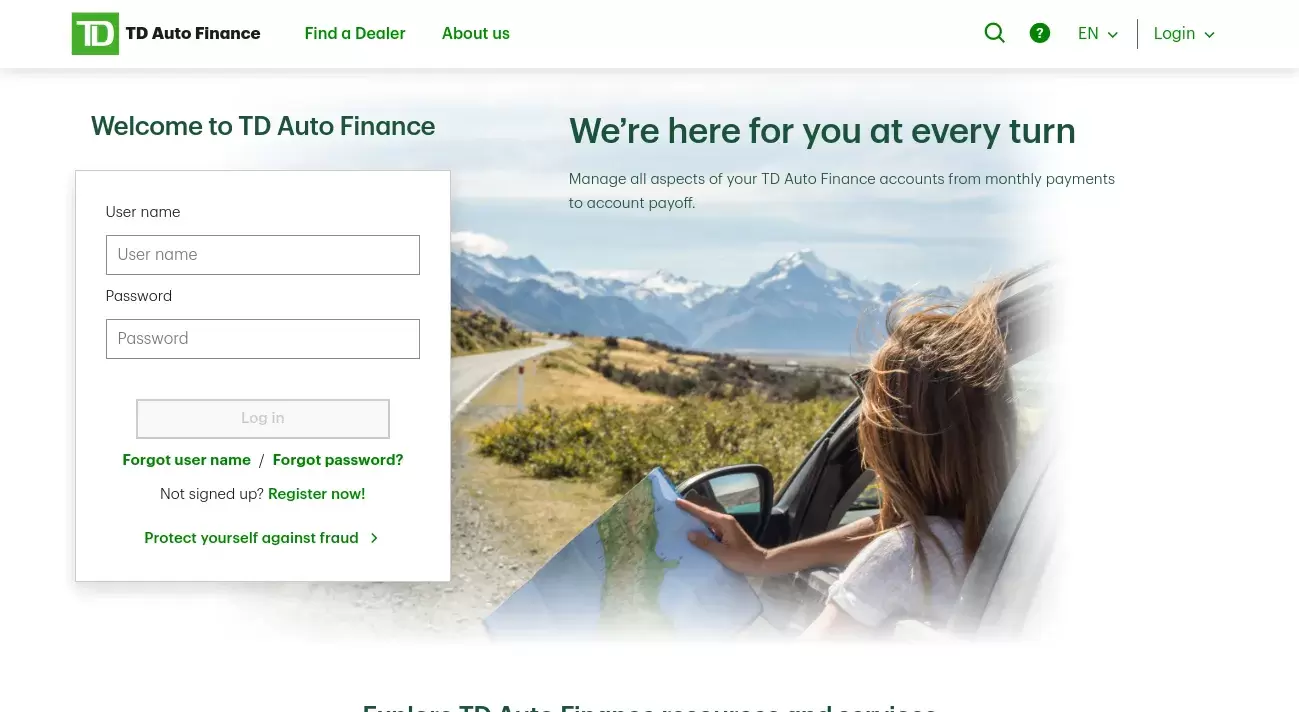
TD Auto Finance runs one of the more straightforward auto loan servicer portals out there, but the first time you log in, there are enough friction points that you will probably waste twenty minutes clicking around before you figure out what actually matters. The login page lives at tdautofinance.com, and you will need your account number, which is printed on your monthly statement or your original promissory note. If you do not have those handy, you can find your account number by calling the servicer line at 866-743-7779, but expect to wait on hold during business hours. The online portal supports two-factor authentication through a code sent to your phone or email, which is a good thing, though it does mean you cannot recover access to your account remotely without having your original phone number still active. Once you are logged in, the dashboard gives you your current payoff quote, which is the number you actually need if you are thinking about refinancing or selling the vehicle. Most people confuse their current balance with their payoff balance, and that is a mistake that costs money. Your current balance is what you owe as of today, while the payoff balance includes interest that accrues daily and is only valid for a short window, typically ten days. The payoff quote refreshes in real time, which is useful, but it also means if you are sitting on the phone with a dealership trying to sell the car, you need to get the quote and close the deal within that ten-day window or the number changes again. There is no way to lock in a payoff quote for a longer period. The autopay setup is where most people encounter problems. You need a checking or savings account that is under your own name, and the bank must support ACH debits from Canada and the United States since TD Auto Finance operates cross-border. If you are using a credit union or a smaller regional bank, their ACH enrollment process can take three to five business days to activate, during which time your autopay enrollment will sit in a pending state. I learned this the hard way when I enrolled autopay on a Thursday using a new community bank account, and by the following Tuesday the payment had not gone through because the bank was still verifying the account. I ended up making a manual payment online to avoid the late fee, and the autopay finally kicked in two weeks later. The workaround is simple: set up autopay at least two full billing cycles before you need it, or verify with your bank that ACH enrollment is complete before relying on the automatic debit.
The document upload feature works, but it is slow. If you need to submit proof of insurance, a lien release, or a title transfer document, you can use the secure upload area in your account. Files must be PDF or JPEG format and under ten megabytes each. The system does not read or validate the content of the document automatically, so if you upload a blurry scan or a corrupted PDF, you will not know about it until someone calls you a week later asking you to resubmit. Always confirm that your uploaded file opens correctly on your own device before you hit submit. There is a feature that most account holders miss entirely: the ability to request a 1091 form directly from the portal. If you refinance with another lender or sell the vehicle, the old lender is required to provide this form within sixty days of the account closure, but requesting it early from the portal speeds things up. I have seen people wait until after their loan was paid off and then scramble because the new lender needed the 1091 for tax filing season. The portal lets you request it at any time after you make your final payment, and it typically processes within five to seven business days. Calling it in separately does not speed that up and usually adds a call center hold. One thing the portal does not do well is let you manage multiple vehicles under a single login if they are held by different servicers. If you have one car loan with TD Auto Finance and another with a different lender, you need separate accounts. This sounds obvious, but people routinely try to add a second vehicle to their existing login, which the system rejects. There is no unified view across multiple lenders, and TD Auto Finance does not offer a feature to link or aggregate accounts from other servicers.
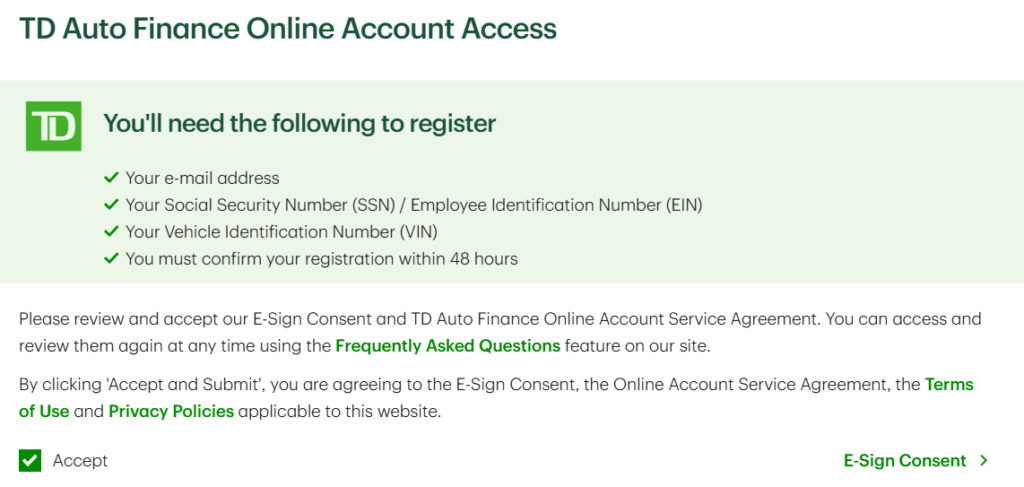
The mobile app exists, but it is a stripped-down version of the web portal. You can check your balance, make payments, and set up autopay from the app, but you cannot upload documents, request payoff statements, or access your payment history older than ninety days. If you are doing anything beyond a routine payment check, the app will redirect you to the browser version anyway. The app crashes occasionally on Android devices when you try to view detailed transaction histories, and there is no workaround other than switching to a different browser or device. I stopped using the app for anything important and just stick to the desktop portal, which has been stable for years. If you ever lose access to your registered phone number or email, account recovery is not seamless. You will need to verify your identity through a series of questions that include your Social Security number, the vehicle VIN, and your most recent payment amount. This process takes two to four business days, and you cannot make any changes to your account during that window. The workaround is to update your contact information proactively before you need it, not after you have lost access. The portal allows you to update your email and phone number at any time, so keep those current. The satisfaction rating for TD Auto Finance's online services is decent but not exceptional. The site loads quickly, the forms are not overly complicated, and the payment system works reliably. The main complaints center around the customer service wait times and the autopay activation delays, both of which are outside the portal's direct control but affect your overall experience. If you need immediate help with a billing issue or a dispute, the online chat feature is available during business hours, but the chat agent often cannot resolve complex issues and will escalate you to a phone call anyway, which defeats the purpose of using chat in the first place. For simple tasks like checking a balance or making a payment, the portal is fine. For anything involving account disputes, lien corrections, or payoff negotiations, you will eventually need to pick up the phone regardless.
Get the Full Details