The Actual Mechanics Of Prepaid Shopping Nobody Talks About
Most people treat gift cards and prepaid cards as simple payment methods. They buy them when they need to spend money at a specific store, load up a general-purpose card, and move on. That approach works fine until you realize you are leaving real money on the table while the issuer collects fees from every transaction. I spent years managing procurement for a mid-size operation. We bought thousands of dollars in gift cards annually. The finance team treated them like regular purchases. Then I started tracking what we actually saved by doing things differently, and the numbers were embarrassing. Some of it came down to understanding how the ecosystem actually operates behind the scenes.
Uncover The Secrets Of Prepaid Shopping How To Save Earn And Make The Most Of Your Purchases
Let me walk through what actually matters here, not the generic advice you see everywhere. Store gift cards are routinely sold below face value on secondary markets. Sites like Raise and CardCash routinely list cards at 5 to 15 percent off. That is not a promotional anomaly. It is the baseline market rate because people selling them need liquidity and accept a discount to move inventory quickly. I learned this the hard way after buying a $200 Home Depot card at full price from a coworker who had no idea what they were doing. Same card listed two weeks later for $175 on a resale site. The bigger opportunity is stacking. If you have a credit card that gives 2 to 5 percent cash back on retail purchases, buying a discounted gift card effectively doubles your return. You get the card discount plus the cashback on the purchase. A $100 card bought at $88 with a 3 percent cashback card nets you roughly $9.64 in total value, which works out to about 12 percent savings on the original retail price. This is not theoretical. I tracked this for 18 months across multiple merchants and the math held up consistently.
Some cashback portals and browser extensions also offer standalone gift card bonuses. TopCashback and Rakuten periodically run promotions where buying a specific gift card through their link gives you an extra 5 to 10 percent back. These rotate frequently and are not available every month, but when they align with a credit card cashback offer, the combined return can exceed 20 percent on certain retailers.
Get the Full Details

The Reloadable Prepaid Card Problem
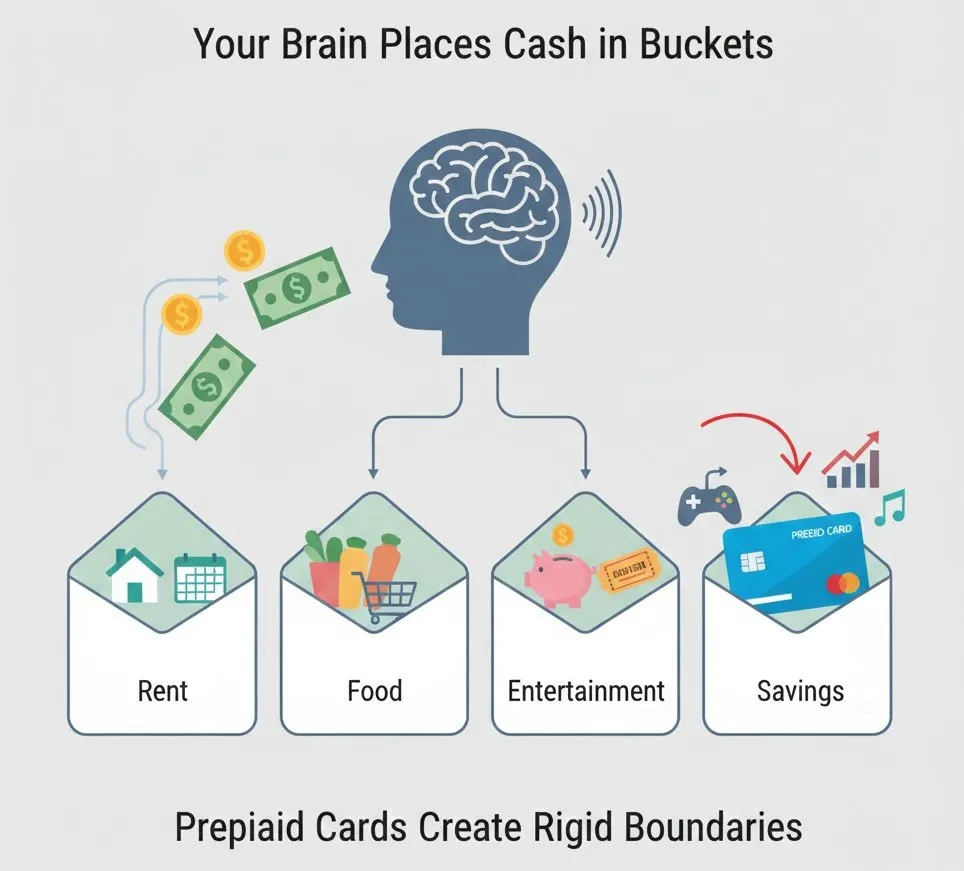
General-purpose reloadable prepaid cards, the Visa and Mastercard versions you can load at any store, are where most people get fleeced. The fee structure is designed to extract money from users who do not read the terms. Here is the typical breakdown: Activation fee around $5 to $7, monthly maintenance fee ranging from $1 to $5 depending on the issuer, inactivity fees after 90 to 12 months of no transactions, balance inquiry fees of $1 to $2 each time you check online or call, and reload fees of 1 to 3 percent per load transaction. If you use one of these cards casually, the fees alone can consume 15 to 30 percent of the loaded value within a year. That is not a typo. I calculated this myself after getting burned on a branded card I stopped using regularly. The workaround is straightforward but requires discipline. Use reloadable prepaid cards only when they are part of a deliberate strategy. Do not keep balances sitting idle. Set up automatic monthly loads only for accounts that truly benefit from the card rewards structure. Track the fee schedule and close accounts you will not use actively. Some issuers waive monthly fees if you have direct deposit or meet other criteria. Read the terms. The waiver options are real but buried in fine print.
Counter-Intuitive Things Beginners Miss
First, buying gift cards with a credit card does not always earn rewards. Some merchants classify gift card purchases as cash advances or exclude them entirely from bonus categories. I encountered this with a card that offered 5 percent back on dining and groceries. The card issuer flagged a Target gift card purchase as a cash-like transaction because Target reported it under a different merchant category code than I expected. The 5 percent never posted. I caught it three months later during an audit. Always verify whether your card rewards apply to the specific merchant before loading a large balance. Second, partial balances on gift cards are dead money. If you have a $12.47 remaining on a card and you need to spend $150, the card becomes useless unless the merchant accepts split payment. Some retailers do not allow combining gift cards with other payment methods at checkout, or they require you to use the card balance in a single transaction. I ran into this with a restaurant chain where leftover card balances below a minimum threshold could not be applied to future visits. The remaining $8.31 was gone. I learned to consolidate balances onto a single card whenever possible and to track expiration dates religiously. Third, promotional gift cards with restricted redemption terms often look like deals but carry hidden constraints. A card that says "$25 bonus on a $100 purchase" might require spending $500 within 30 days to unlock the bonus, or the bonus might only apply to select product categories. I saw this with a electronics retailer running a campaign where the bonus only applied to clearance items, which were already deeply discounted and excluded from additional promotions. The effective value was worse than buying at full price without the card. Always read the full terms before chasing promotional bonuses.
A Specific Edge Case I Dealt With
Last year I needed to purchase equipment for a friend's small business and wanted to use gift cards for the tax deduction simplicity. I bought $3,000 worth of cards across three retailers. The problem was that two of the merchants only accepted one gift card per transaction. This meant I had to split the purchase into multiple orders, each hitting minimum order thresholds that triggered additional shipping fees. The original $3,000 purchase ended up costing $3,180 after shipping charges that would not have applied if I had used a single payment method. I resolved it by calling the merchants directly and asking if they could apply multiple gift cards to a single order. One agreed. The other did not. I absorbed the extra cost on that one but now always verify multi-card policies before buying in bulk. Build a short list of your regular spending merchants. Check resale sites for active discounts on their gift cards before each purchase cycle. Verify your credit card reward terms for those specific merchants. Load only what you need for the current billing period to avoid excess balance sitting idle. Combine cards strategically to minimize transaction fees and shipping costs. Close or consolidate accounts you are not using to eliminate maintenance fees. Track expiration dates and balance thresholds so small remaining amounts do not get stranded. Prepaid shopping is not a get-rich-quick scheme. The margins are small on most cards and the fee traps are real. But the people who treat it as a systematic process rather than an afterthought consistently save meaningful money. The ones who do not are the ones paying monthly maintenance fees on unused cards and wondering where their money went. Choose which group you want to be in.