How Money Orders Work at Meijer Stores
Meijer locations across the United States offer money order services through their customer service desks or front checkout areas. These are prepaid payment instruments that function similarly to cash but provide a paper trail for the sender. You fill out the recipient information, pay the face value plus a small fee, and hand the completed money order to whoever needs it. The process is straightforward, though there are a few details worth knowing before you go. The fee structure at Meijer has generally ranged from $0.50 to $1.00 per money order, depending on the location and the amount being sent. Some stores may charge slightly more for larger denominations. As of my recent visits, the standard limit per money order was $500, though you can purchase multiple money orders in a single transaction to send larger amounts. The total you can send in one visit effectively depends on store policy and whether you need to fill out additional paperwork.
Uncover The Secrets Of Money Order At Meijer A Comprehensive Guide
Here is what actually happens when you walk into a Meijer to buy a money order, based on my experience at several locations in Michigan and Illinois. You do not need an account or a Meijer card. The money order is available to anyone who walks through the door. I have purchased them with cash, debit card, and occasionally with a check from my checking account at the store. Credit cards are typically not accepted for money order purchases, which makes sense from a risk management perspective since it would essentially be a cash advance with a fee attached. The staff member who handles money orders is usually stationed at the customer service desk rather than a regular register. In some Meijer locations, particularly the larger Supercenter formats, you might find the service near the front of the store close to the main entrance. In smaller or older locations, it could be at a dedicated service counter near the back. I once spent about twelve minutes looking for it in a Meijer in Gary, Indiana before asking a employee who directed me to the correct desk. This is not something you need to stress about, but it is worth noting that the placement varies by store layout.
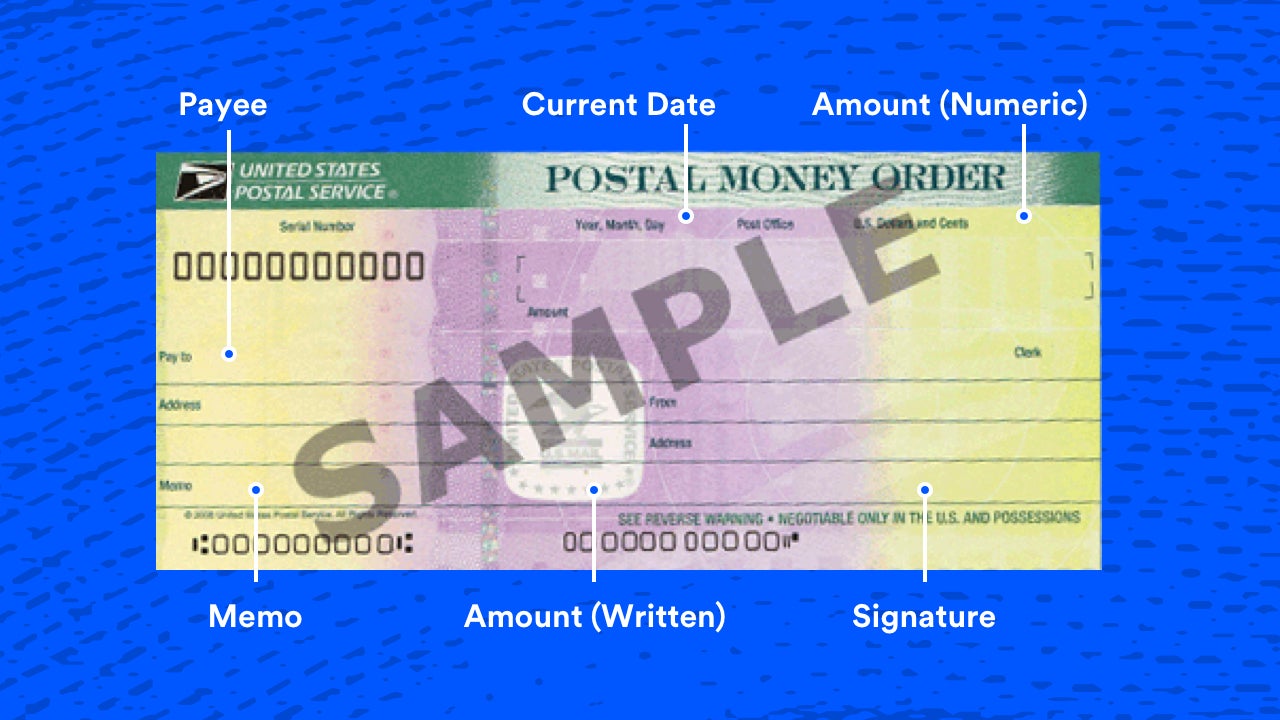
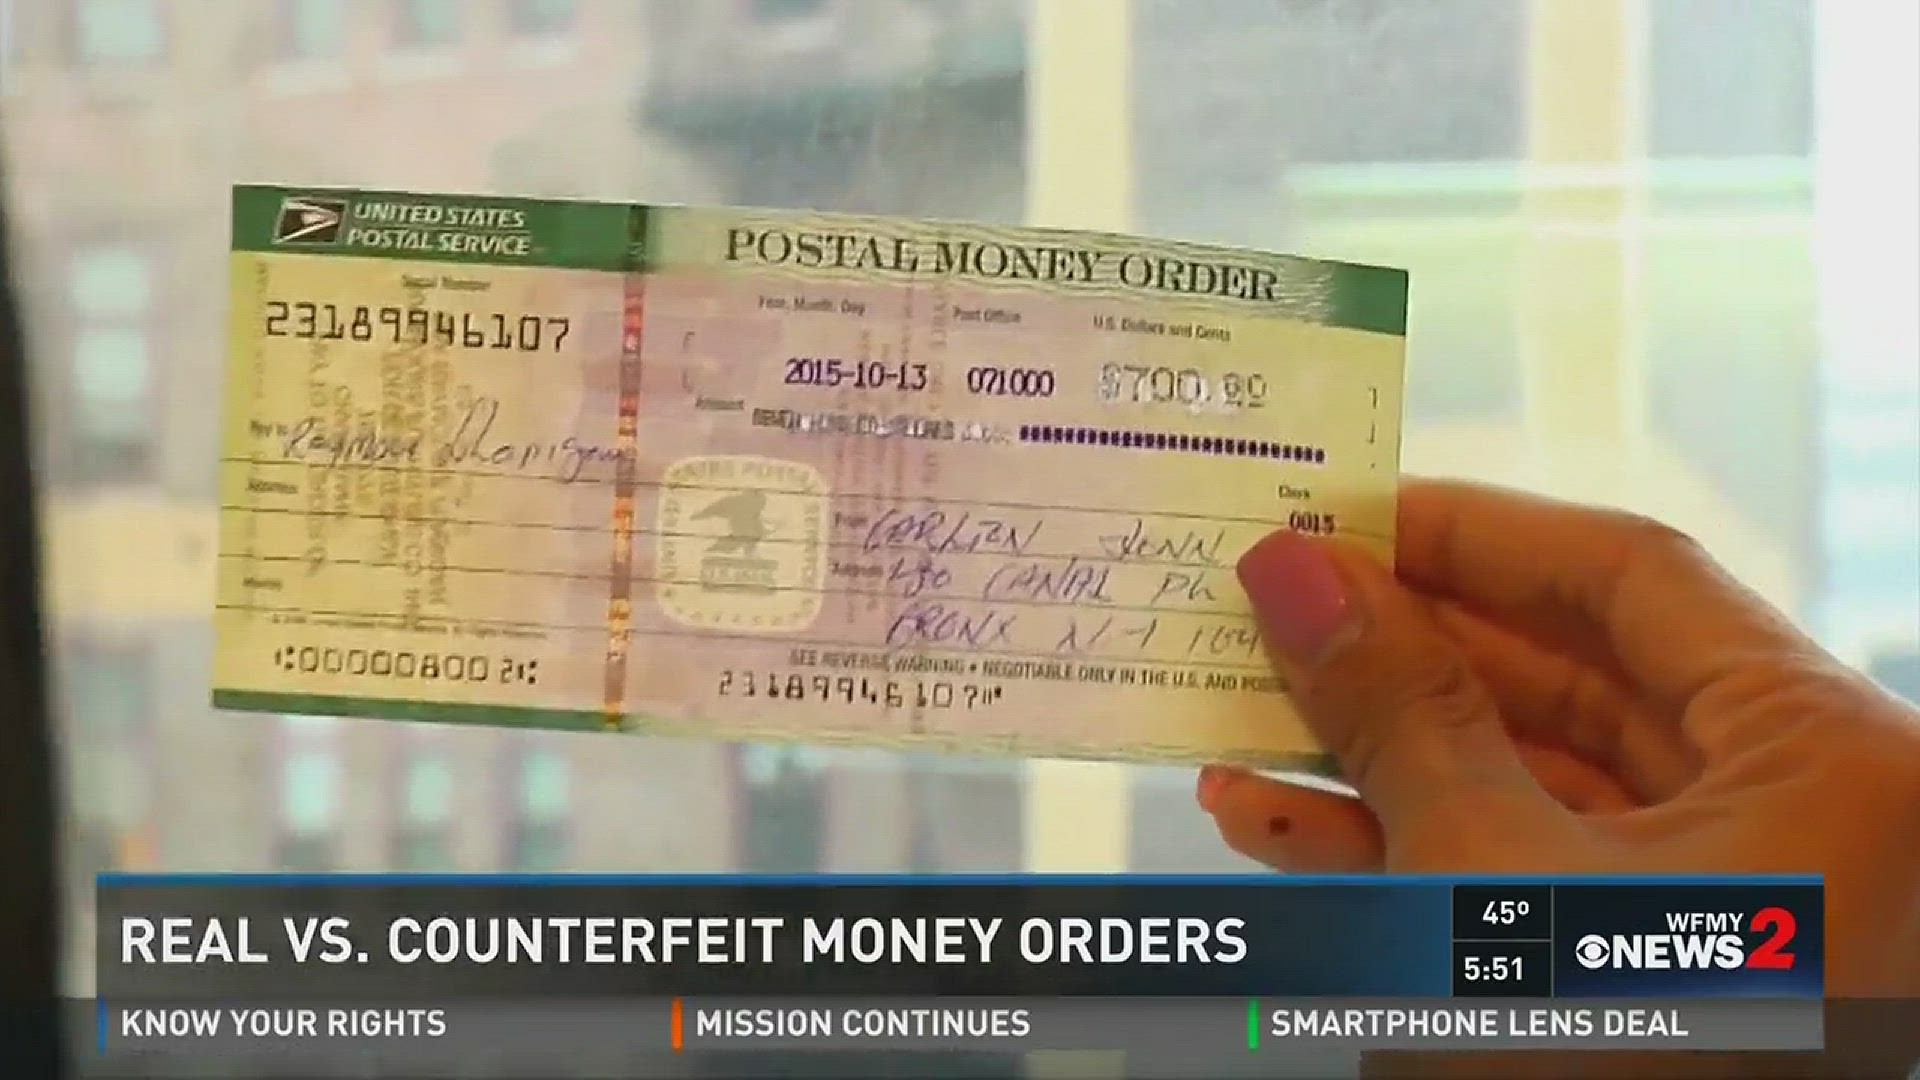
When filling out the money order, you write the recipient name in the "Pay to the order of" field and often your own name and address in the "From" or "Purchaser" field. The memo line is optional but recommended if you are sending payment for a specific bill or purpose. I have found that writing clearly in blue or black ink prevents any issues during processing, especially if the recipient needs to endorse it later. One thing that caught me off guard during my first purchase was the ID requirement. Some Meijer locations ask to see a government issued photo ID when you buy a money order, particularly if the amount is above a certain threshold. The policies are not consistent across all stores, which I learned after being asked for my driver's license at one location and not at another just twenty minutes away. Carrying your ID is the safest approach regardless. The money order itself is a printed document on secure paper with watermarks and other anti-fraud features. You receive a receipt stub that you should keep until the recipient confirms they have deposited or cashed it. This stub contains the money order number, the amount, and the date, which is useful if anything goes wrong. I learned this the hard way when a family member misplaced theirs and had to spend nearly an hour on the phone with the issuer to trace a payment that ultimately went through without issue.
Get the Full Details
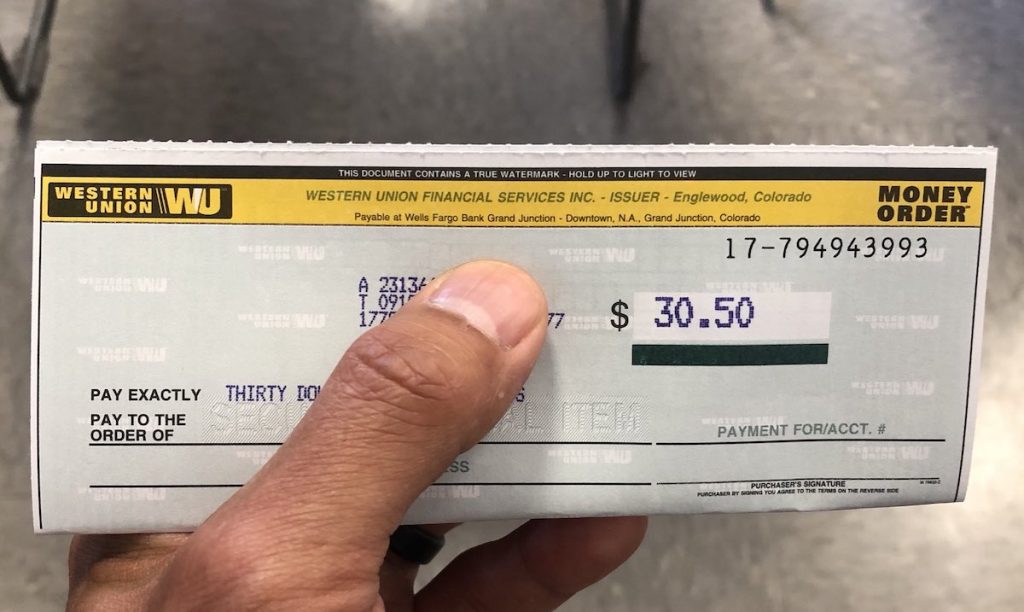
Processing times vary depending on how the recipient uses the money order. If they deposit it at their bank, funds are usually available within one to three business days, though some banks hold money orders for longer if the amount is unusual or the store is not a recognized issuer. If they cash it at a check cashing store or the issuing company's location, it can sometimes be done the same day. I have found that calling ahead to the recipient's bank or the check cashing establishment to confirm they accept Meijer money orders saves a lot of unnecessary trips. There are limitations you should be aware of. Money orders are not the same as checks drawn on your bank account. They do not have a routing number and account number printed on them, which means they cannot be used to set up recurring payments or automated withdrawals. If you are paying a utility company or rent that accepts only electronic or check payments, a money order will not work for those purposes. Additionally, money orders do not earn interest and do not provide the same fraud protections as credit card payments. Once the money is spent, it is generally gone with limited recourse. The primary advantage of a Meijer money order is accessibility. You do not need a bank account to purchase one, which makes it useful for people who are unbanked or who prefer not to share banking details for a particular transaction. You also do not need to visit a dedicated money order outlet or a post office. Meijer locations are widespread, with hundreds of stores across the Midwest and beyond, so you are likely to find one within a reasonable driving distance.
Security is another factor. Money orders are less risky than sending cash in the mail because they can be tracked and, in some cases, replaced if lost or stolen. The receipt stub is your proof of purchase, and you should treat it as important as the money order itself. I recommend taking a photo of both the front and back of the money order and your receipt before mailing or handing it off, just in case anything goes wrong during transit. If you need to send larger amounts regularly, a Meijer money order may become inconvenient due to the per-transaction limits and fees. In those situations, a direct bank transfer or a service like PayPal or Venmo might be more cost effective, though those options require a bank account and a digital setup. For occasional, smaller payments where simplicity matters more than price, the Meijer money order remains a practical choice. I have used them for paying rent to a landlord who preferred paper payments, sending emergency funds to relatives in other states, and covering situations where I did not want to use a credit card. Each time, the process took about five to ten minutes at the store, not including any waiting time in line. The entire experience is largely unremarkable, which is probably why so few people bother documenting it online. But if you are reading this because you need to buy one soon, the information above should cover the basics without sending you on a wild goose chase.