When Your Terminal Says Pick Up Card, Here Is What Actually Happens
I have processed thousands of transactions across different POS systems and merchant accounts. The "Pick Up Card" decline is one of those responses that makes every cashier freeze and every manager panic. You are standing at a checkout, the customer swipes or taps their card, and the terminal flashes an instruction that looks like it belongs in some kind of security protocol rather than a retail environment. The situation feels awkward and confrontational, and most people handling it for the first time do not know how to proceed without making things worse. The response code itself comes from the issuing bank or the card network. When a transaction returns "Pick Up Card," the bank is telling you that this particular card has been flagged for retention. The most common reasons are straightforward: the card was reported lost or stolen, it has been associated with suspected fraudulent activity, or the account holder requested the bank freeze the card. Less commonly, it can appear when there is a mismatch between the card data and records on file, though that usually triggers other decline codes first.
Uncover The Secret Behind Card Declined Pick Up Card Sf Meaning And Solutions Understanding The Frustrating Problem And
The "SF" designation you sometimes see attached to this response typically indicates the region or processor routing the authorization request. In my experience working with mid-market merchants in Northern California, SF often points to a specific acquiring bank or payment processor routing node rather than meaning something fundamentally different about the decline itself. The underlying reason for the pick-up instruction remains the same regardless of what geographic tag appears in the logs. Here is what you need to do when this happens at your terminal. First, do not return the card to the cardholder immediately. The issuing bank is explicitly instructing you to retain it. Ask the customer to step aside politely and explain that there is a security flag on the card that requires you to hold it. Most reasonable customers understand this, though you will encounter the occasionally aggressive one who insists on their card back. That is when you explain that you are following bank instructions and that returning the card could create legal liability for your business. Second, call the acquiring bank or your payment processor's support line. You need to verify whether the card should actually be surrendered to law enforcement or whether the processor can resolve it on the spot. I once had a merchant in Oakland call me at 11 PM on a Friday because a customer was demanding their card back at gunpoint, essentially. The terminal showed Pick Up Card, the customer was escalated and agitated, and the merchant had no idea what to do. We called the acquirer, confirmed the card was indeed flagged for fraud, and the customer eventually calmed down once they realized we were not just making excuses to keep their card. They left without it, and we secured the card in the register safe until local authorities could be contacted the next morning.
Third, document everything. Write down the card number (only the last four digits, do not write the full number anywhere), the time, the customer's description, and the name of the person handling the call with your processor. If law enforcement gets involved, that documentation is going to matter more than anything you remember later.
Get the Full Details
Why This Response Is Different From Other Declines
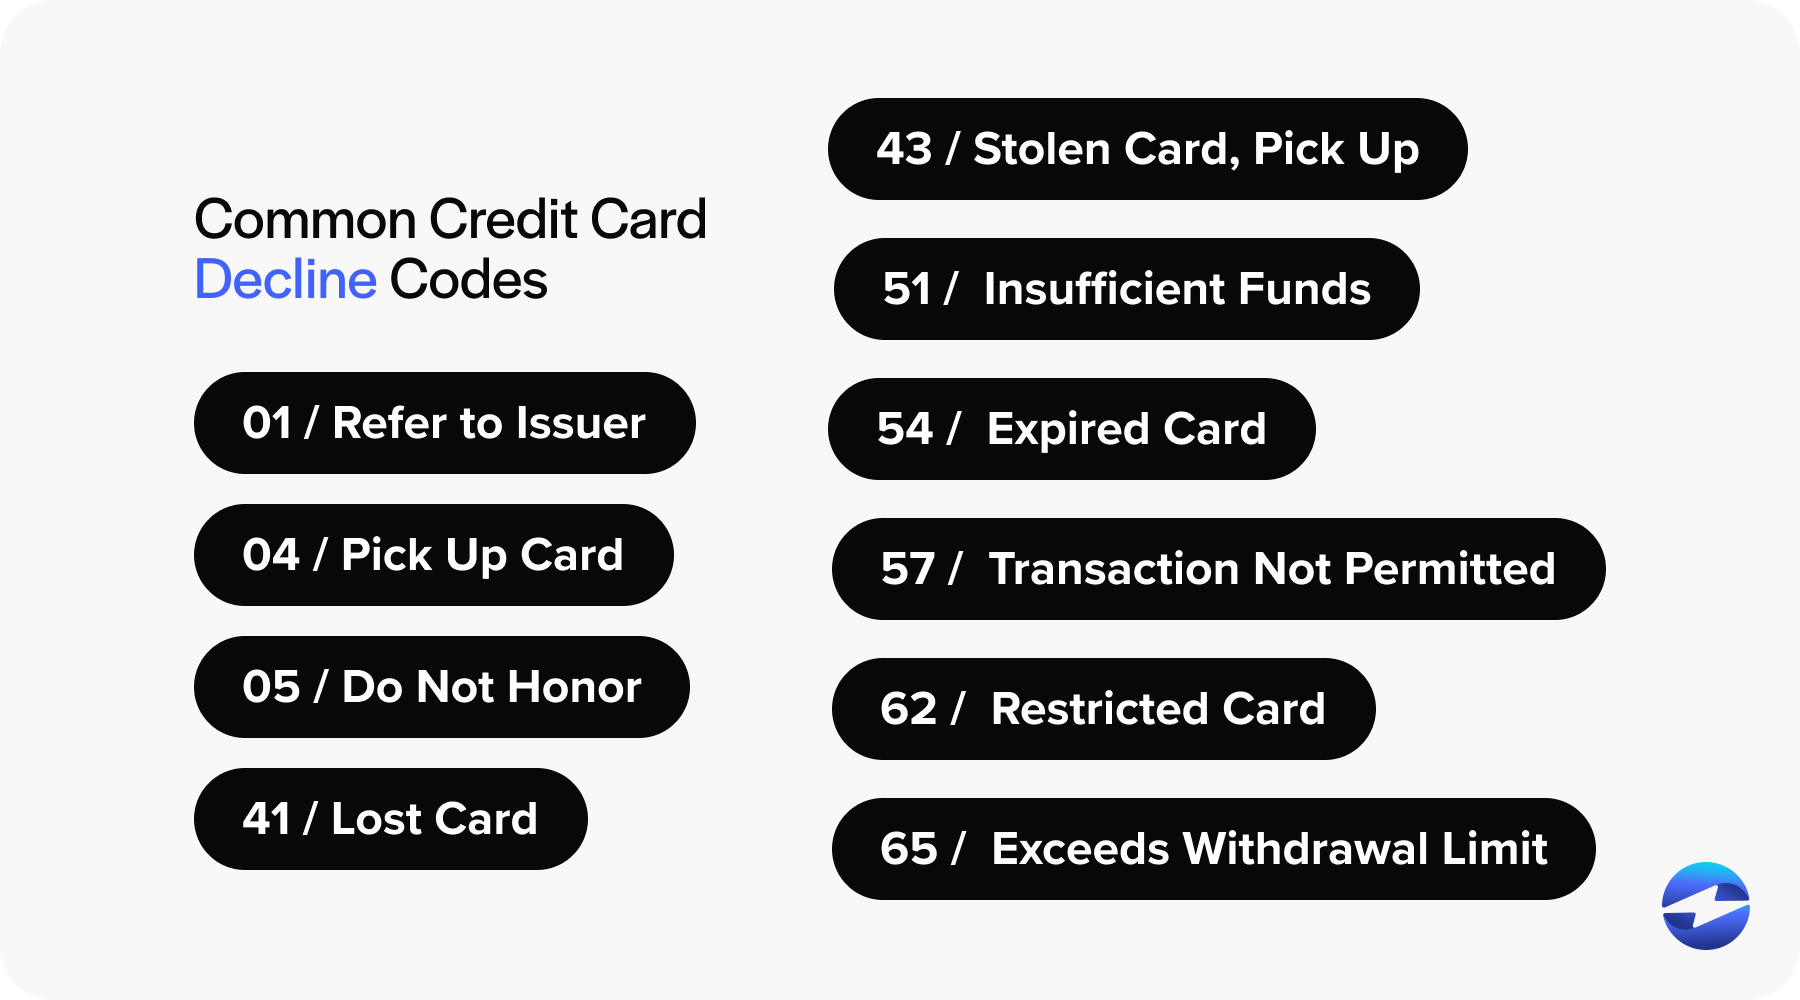
Most decline codes are transaction-level issues. Insufficient funds, expired card, incorrect CVV, hitting the daily limit. Those are things you can often resolve by asking the customer to try a different card or a different payment method. Pick Up Card is not a transaction problem. It is a card-level security directive. The card itself is considered compromised or dangerous in some way, and the instruction applies regardless of whether the current transaction has sufficient funds or any other technical issue. This distinction matters because many cashiers and even some managers treat it like a normal decline. They hand the card back and say "try another one," which means you have effectively ignored a direct instruction from the issuing bank. In most cases the worst outcome is that the transaction simply fails and the customer leaves. But in edge cases where the card truly is stolen property being used by someone other than the legitimate holder, returning it could mean you become an unwitting participant in the disposal of stolen goods. I have seen it happen. Not often, but enough that I make sure every shift lead in my operations understands the difference.
Common Mistakes That Make Things Worse
The biggest mistake I see is confronting the customer aggressively. You do not need to accuse anyone of fraud. A simple statement that the card has a security flag and needs to be retained is sufficient. The second mistake is processing the card again anyway after getting the decline. Some terminals allow retry attempts, and some merchants think a second swipe might bypass the flag. It will not. The flag lives on the issuer side, not your terminal, and retrying only increases suspicion and can escalate the situation with the customer. Another mistake is not having a written procedure for this scenario. When Pick Up Card appears on the screen, there should be a clear playbook: who calls the processor, who talks to the customer, where the card goes, what information gets logged. Without that, you get chaos and inconsistent handling from one shift to the next.
What Does Not Work
There is no workaround for a legitimate Pick Up Card decline. You cannot override it through your processor, you cannot get it reversed by calling the bank as a merchant, and you cannot convince the terminal to approve it by adjusting any settings. If someone is telling you otherwise, they are either misinformed or trying to sell you something that will not help. The only real solution is the proper retention and documentation process I described above. Some merchants try to use alternative payment verification methods, like checking the card against a manual imprint or running the card through a different channel. This is not recommended because it does not change the status of the card and can create additional compliance issues. The pick-up instruction is final from the issuer's perspective.
The Realistic Outcome You Should Expect
In the vast majority of cases, the customer will either accept the situation and use another payment method, or they will become difficult and eventually leave. The card gets turned over according to your processor's instructions, which may mean holding it until a manager arrives, mailing it to the issuer, or coordinating with local law enforcement depending on your agreement with the acquirer. The transaction is lost. That is the reality. You are not going to save it. What you can control is how professionally you handle the moment and how well documented the event is. Merchants who treat Pick Up Card responses with the seriousness they deserve tend to have far fewer problems down the line than those who brush them off as just another declined sale.