Mobile Home Rentals Are Not What You Think
The rental market for manufactured housing is a completely separate ecosystem from conventional apartment living. Most people search for a place, see a price, and assume the deal is straightforward. It rarely is. The hidden part isn't secrecy; it is the sheer volume of variables that nobody warns you about before you sign anything. I spent three years managing a portfolio of twenty-two manufactured homes in three states. I learned this the hard way, mostly through eviction filings and utility bills I never anticipated. The difference between a bad experience and a manageable one usually comes down to understanding the land versus the structure.
Uncover The Hidden World Of Mobile Homes For Rent A Comprehensive Guide
This distinction matters because most listings blur the line intentionally. A $850 monthly payment sounds reasonable until you realize it covers the home but not the lot. In many parks, you pay lot rent separately, and lot rents increase annually by five to twelve percent depending on the region. That $850 becomes $1,100 within two years without any mention in the ad. I once took on a property where the tenant thought they were paying a mortgage. They were actually paying lot rent at a park that had no written cap on increases. The landlord raised the space fee by eighteen percent in year one. The tenant couldn't move the home out because the park lease didn't allow subletting. It took fourteen months to resolve through a county mediator, and the tenant walked away with nothing. The first thing you need is a clear understanding of whether you are looking at a pad rental, a manufactured housing community, or a private landlord situation. Each carries entirely different legal protections and costs.
Parsing Listing Reality
Most platforms don't categorize manufactured housing properly. Zillow lumps them with site-built rentals. Facebook Marketplace listings are almost entirely unmoderated. You will find ads that say "mobile home for rent" when the reality is a space in a park, or worse, a home being sold with a lease-back arrangement that is essentially a predatory loan. Look for these markers in any listing: HUD tag visible in photos indicates the home meets federal construction standards. Homes built before 1976 have fundamentally different structural and financial realities attached to them.
Lot rent explicitly stated rather than buried in fine print. If the ad says "home only" or "rent includes home and lot," push for the breakdown in writing before scheduling a showing. Community rules section mentioned up front. Some parks prohibit guests staying more than ten days, ban certain vehicle types, or require home insurance that meets specific thresholds. These rules aren't optional after you move in. I found a place in central Texas listed at $795 including everything. The disclosure packet had seventeen pages of park covenants. One clause required approval for any exterior modifications, including awning installations. Another mandated that all trash be stored in enclosed bins behind the home, not in the visible side yard. The management company enforced the bin rule through fines of $25 per violation, weekly. Over a year, that can total over a thousand dollars if you miss a single pickup day.
Get the Full Details
The Inspection You Should Actually Do
Standard home inspection advice doesn't translate well to manufactured housing. The systems are different, the failure points are different, and the repair economics are completely unlike stick-built properties. Skid and underbelly assessment should come first. Look for torn vapor barriers, exposed insulation, rodent damage, and uneven skirting. Water intrusion under the home is the single most expensive problem you can inherit. I once documented a case where replacement of rotted subfloor joists beneath a manufactured home cost $4,200 because the work required lifting the entire structure andblocking it. That wasn't covered by the tenant's renter's insurance, obviously, and the landlord refused to touch it. The tenant ended up paying for it to stay in the home. Plug-in utility connections need verification. Manufactured homes often connect to city water and sewer through quick-disconnect fittings. Check for corrosion, cracked seals, and evidence of previous leaks around the connection points. A failed sewer connector can create a sewage backup situation that is both a health hazard and a repair bill you will be responsible for if you signed a lease assuming tenant maintenance of those components.
Roof seam inspection is critical. Manufactured home roofs use sealed seams that degrade faster than traditional shingle roofs. Look for dark streaks along seams, raised sealant beads, or areas where the coating has worn thin. Roof repairs on manufactured homes run $1,500 to $4,000 depending on size and damage scope. A full roof replacement can exceed $8,000. HVAC sizing and condition deserves specific attention. Many units ship with undersized systems that struggle in extreme climates. If the home has a single packaged unit on the roof, ask about its age and maintenance history. These units cost $3,000 to $6,000 to replace. Proper documentation of the unit's service record should be provided before any lease is signed. Anchor and tie-down verification matters in wind-prone regions. Homes not properly anchored can be damaged or destroyed in storms, and some insurance policies require proof of tie-down compliance. I worked with a homeowner in Oklahoma whose insurance was voided because the tie-down certificates had expired. The storm damage claim was denied outright. Check that documentation exists and is current.
The Lease Structure Nobody Talks About
Manufactured home leases come in fundamentally different forms, and confusing them leads to serious financial exposure. A pad lease means you own the home but rent the ground it sits on. Your rights depend heavily on state law. Some states treat pad leases as residential tenancies with full eviction protections. Others classify them differently, giving landlords more leverage to raise rent or terminate with minimal notice. A community lease in a manufactured housing park typically covers both the space and the home. These operate more like traditional rentals, but the park's rules and fee structure add layers that standard apartment leases don't have. You may face additional charges for amenities, waste removal, or even mandatory community events.
A landlord-owned home rental means you pay rent for both structure and land. This is the simplest arrangement legally but also the one where maintenance responsibilities are least clear. Many landlords in this category treat the home as an investment asset rather than a dwelling, meaning they defer maintenance until problems become catastrophic. I encountered a situation in Georgia where a landlord owned a row of twelve homes and rented them all out. He collected rent but performed zero maintenance beyond emergency calls. By the third year, four homes had unreplaced HVAC systems, two had roof leaks patched with tarp and caulk, and one had foundation settling that caused door frames to warp shut. The rent was $675 per month, well below market rate for the area. The hidden cost showed up in the form of $340 emergency repair invoices that appeared on monthly statements without prior notice. The lease clause allowing "necessary repairs" with billing added to rent was legally enforceable under Georgia law at the time.
Cost Breakdown Beyond the Monthly Payment
People calculate affordability wrong with manufactured housing. The sticker price misses most of the real costs. Homeowners insurance for a rented mobile home typically runs $400 to $900 annually, depending on age, location, and coverage level. Some parks require minimum coverage amounts that push this higher. Property tax may or may not be included. If the home is titled as personal property rather than real estate, you might pay personal property tax separately from rent. In some states, this adds $200 to $800 yearly to your effective cost.
Utility setup fees for transferred service can run $150 to $400 per utility. Electric, water, gas, and trash each carry their own connection or transfer charge when you move in. Maintenance reserves should be planned at 1 to 2 percent of the home's value annually. A $40,000 home needs $400 to $800 per year set aside for repairs. This isn't optional. Plumbing failures, appliance breakdowns, and roof issues will happen. Park fee escalations are the silent budget killer. I tracked a park in North Carolina where lot rent increased by 7 percent annually for five consecutive years. The tenant had signed a month-to-month agreement with no rent cap. Over five years, the monthly payment rose from $650 to $910 without any change to the home or services provided.
Where to Actually Find Listings
Major rental platforms are inadequate for manufactured housing. They lack the filtering and categorization needed to separate pad rentals from community rentals from private landlord deals. Manufacturer-specific forums like Talk MobilHomePros and various regional groups on Facebook are where actual landlords and property managers post directly. These communities have real discussion about specific parks, management quality, and hidden fees. The information is unstructured and requires sifting, but it is far more accurate than any aggregated listing site. Local manufactured housing dealerships often know which properties are available for rent because they handle sales and trades in the area. Dealers talk to landlords constantly. A quick phone call to a dealership fifty miles from your target area can surface listings that never hit the internet.
County tax assessor records can reveal property owners. If you drive through a neighborhood of manufactured homes and find one that looks maintained but has no "for rent" sign, the assessor's office can tell you who owns it. A direct approach sometimes works better than waiting for a listing to appear online. I've closed deals this way twice, both involving landlords who were tired of managing vacancies through unreliable platforms. State manufactured housing associations publish directories of parks and sometimes available homes. These organizations exist specifically to advocate for residents and property owners, so their listings tend to be from operators who take the business seriously.
Red Flags That Should End the Deal Immediately
Certain patterns appear repeatedly across decades of manufactured housing rentals. Learning to recognize them saves months of wasted time and significant money. Vague or declining to provide written lease terms before you move in. Verbal agreements are nearly impossible to enforce. Demand the full lease document and read it yourself before signing anything. No written policy on rent increases. If the landlord says "rent goes up every year" without specifying the amount or frequency, that is a problem. Get it in writing or walk away.
Avoidance of inspection access. A landlord who refuses to let you inspect the home, underbelly, or mechanical systems before signing is hiding something. I had a landlord in Alabama refuse entry to the crawl space, claiming "there's nothing to see." The next tenant discovered a collapsed support beam that had been covered with plywood and skirting. Structural failure cost that tenant $6,000 in temporary housing and a months-long legal battle. Requests for cash payments only. Any landlord insisting on cash or money order without a receipt is operating outside normal channels. This creates no paper trail and no legal protection for either party. Prior tenant complaints about the same issue. Drive by the home at different times of day. Talk to neighbors. Check if other units in the same park have similar maintenance complaints posted online or in community groups.
The Application and Approval Process
Application requirements vary wildly. Some parks use standard credit checks with minimum score thresholds. Others operate on a discretionary basis where the landlord reviews everything personally. Credit requirements in manufactured housing communities tend to be more flexible than apartment complexes, but that doesn't mean loose standards. Many parks accept scores in the mid-600s if you can demonstrate stable income. A denied application usually comes down to unresolved evictions, active collections above a certain threshold, or insufficient income relative to rent. Income verification typically requires pay stubs covering sixty to ninety days, or tax documents if self-employed. Some landlords accept bank statements instead. The standard ratio expected is income of at least 2.5 to 3 times the monthly rent including lot fees.
Background checks are standard but the scope varies. Most landlords check criminal history and eviction records. A few also pull driving records, which matters if you'll be operating heavy equipment or vehicles as part of your job. The cost of these checks ranges from $25 to $75 and is usually non-refundable. I learned to prepare a rental resume before applying anywhere. It included employment verification, two previous landlord references with contact information, a brief statement of rental history, and copies of recent pay stubs. This document cut my average application processing time from eleven days to four days. Some landlords moved quickly because they saw organized applicants as lower risk regardless of credit score.

Moving In and Setting Up Correctly
The first thirty days in a manufactured home rental determine whether you will have ongoing problems or a stable living situation. Most mistakes happen during this window. Document everything photographically before you unpack a single box. Walk through every room, outside surfaces, the underbelly access panels, the electrical panel, the water heater, and the HVAC unit. Take dated photos of any existing damage, including small cracks in walls, stained ceilings, or worn flooring. Email these photos to the landlord and keep a copy. This creates a timestamped record that prevents you from being charged for pre-existing conditions. Test every system individually. Run water in every sink, shower, and toilet. Flush each toilet to confirm proper sealing. Turn on all lights and outlets. Test the HVAC in both heating and cooling modes. Check that windows open and close fully. Note any issues in writing and submit them to the landlord within forty-eight hours of move-in.
Locate all shut-off valves immediately. The main water shut-off, the gas shut-off if applicable, and the electrical panel location should be known before an emergency happens. I've responded to calls from tenants who had no idea where their water shut-off was during a flooding incident. The damage from a forty-five-minute delay can exceed $5,000 in affected belongings and structural materials. Understand the maintenance response timeline. Ask the landlord in writing what their expected response time is for different types of repairs. Non-emergency maintenance might take two weeks. Emergency issues like no heat in winter or a major leak should be addressed within twenty-four to forty-eight hours. Get these commitments documented, because enforcement requires proof of what was agreed to.
Know When to Walk Away
Not every situation is fixable. Some manufactured home rentals have structural, financial, or legal problems that no amount of careful management can overcome. If the home has significant foundation settling that causes doors to bind, walls to crack, or floors to slope noticeably, the repair cost will likely exceed any rent discount offered. Foundation repair on a manufactured home ranges from $2,000 to $15,000 depending on severity. If the park is facing code violations or has a history of regulatory action, the instability affects your ability to stay long-term. I once watched a park in Florida lose its operating license due to repeated fire code violations. Thirty-two families were displaced within six months with little advance notice.
If the landlord has no insurance on the structure and refuses to obtain any, you are effectively paying rent for a building that would not be covered if it burned down or was damaged by storm. In that scenario, you bear the full risk of losing your belongings with no recourse against the landlord for the structure itself. Some manufactured home communities have restrictive covenants that limit who can live there beyond what local fair housing laws permit. Age-restricted communities, for example, may legally exclude families with children under fifty-five-or-one rules. Understand these restrictions before committing to a lease.
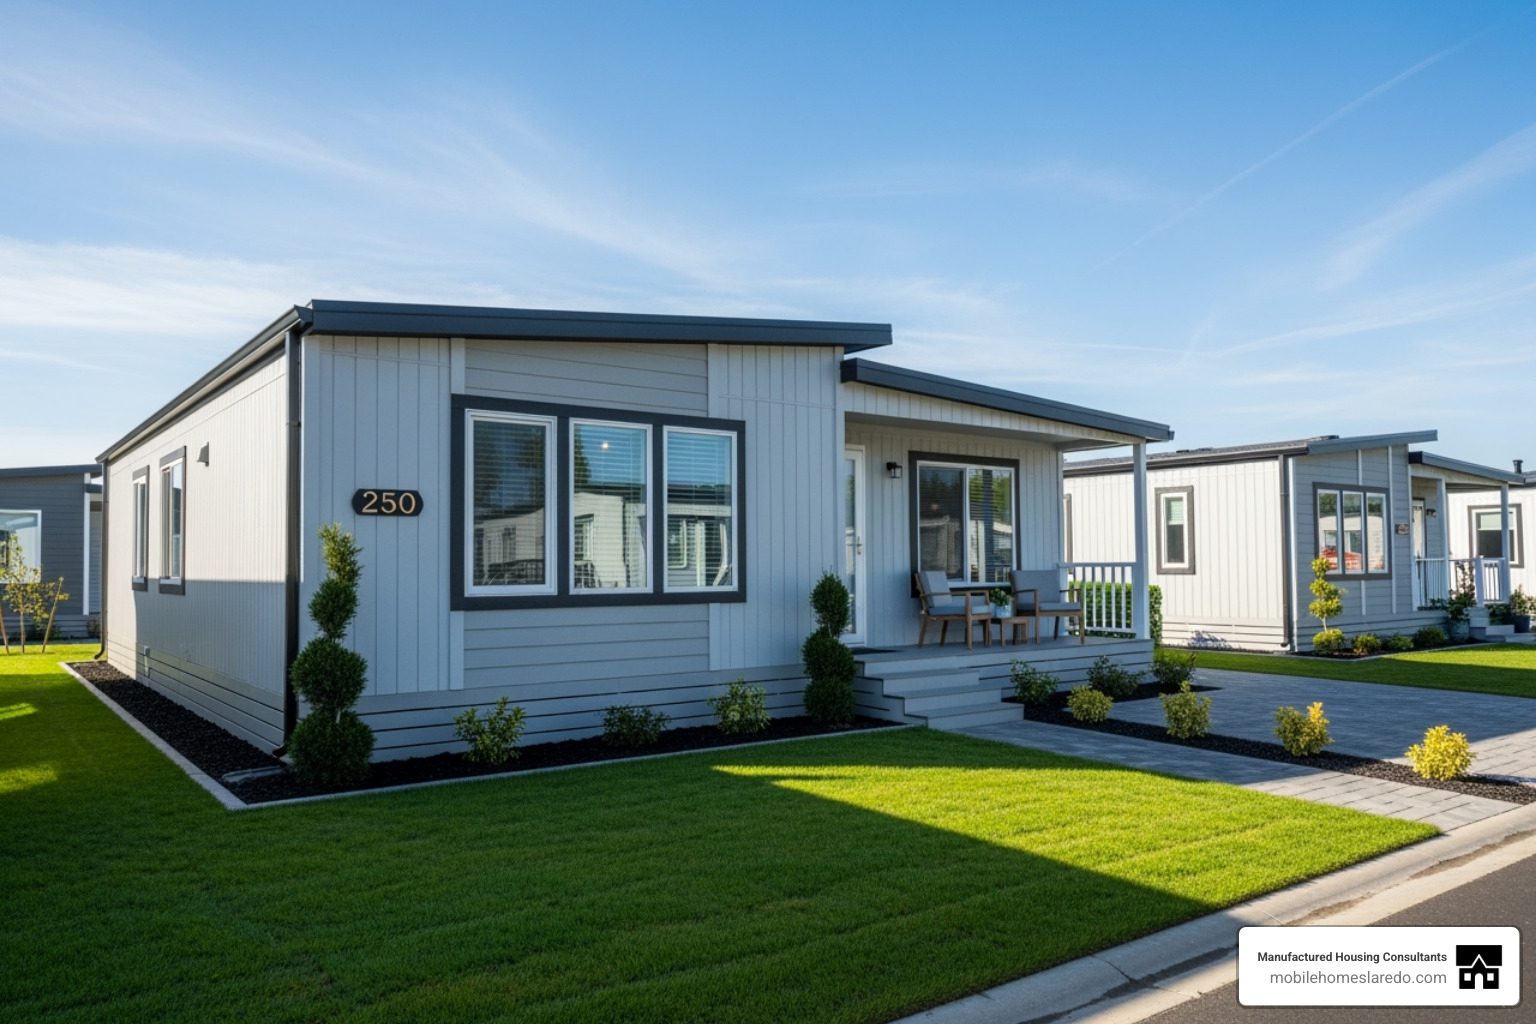
Long-Term Considerations
Manufactured home renting is not a permanent solution for most people, but it is a viable intermediate step if managed correctly. The key is understanding exactly what you are renting and what risks you are assuming. Building equity through renting is impossible. Every payment goes to the landlord. If your goal is eventual ownership, save aggressively and target purchase rather than long-term renting. The gap between purchase price and monthly rent in manufactured housing can close faster than people expect, especially in markets where home prices remain moderate. Negotiation is possible in most manufactured housing rental situations. Landlords who have had vacancies speak to this. A well-prepared applicant with strong references and a rental resume can negotiate rent reductions, waived fees, or included maintenance responsibilities. I once secured a $75 monthly reduction plus a written agreement that the landlord would handle all HVAC maintenance in exchange for signing a twelve-month lease instead of month-to-month.
State law varies significantly. Some states provide robust protections for manufactured home tenants. Others provide almost none. Research your state's specific statutes before signing any lease. The Mobile Housing Act in states like North Carolina and Texas offers specific tenant rights that do not exist in states without comparable legislation. Knowing your rights changes the power dynamic dramatically. The manufactured housing rental market operates on information asymmetry. Landlords know the problems. Tenants usually don't. The gap between those two positions determines whether you end up with stable housing or a costly lesson. The information above closes that gap partially. Reading actual lease agreements, asking direct questions, and documenting everything completely closes it further.
