So You Want To Enter The Rum Market
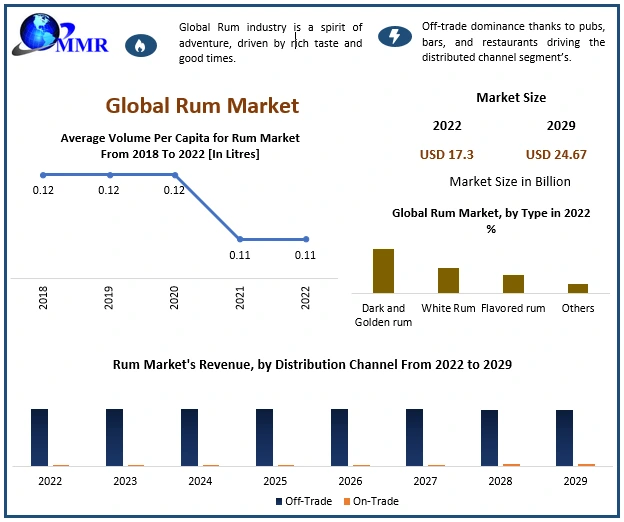
Rum has been having a moment for about ten years now. What started as a niche conversation among bartenders in Brooklyn and London has metastasized into something the major spirits conglomerates can't ignore. Diageo, Pernod Ricard, and Bacardi are all shifting their capital allocation toward premium aged rum portfolios. If you're looking at this from a market entry or investment angle, the surface-level data is misleading. The opportunity exists, but the barriers are different than they appear. The global rum market sits at roughly 4.8 billion dollars as of 2024. That number sounds small next to whiskey's fifteen billion dollar footprint, but the growth rate is where the story lives. Premium and super-premium rum is growing at about eight to ten percent annually, nearly double the rate of standard rum. The consumer is trading up. People are drinking less total alcohol but spending more per drink, and rum is one of the categories where that shift is most visible. I spent about three years working on distribution strategy for a mid-tier Caribbean distillery trying to break into the American market. The hardest part wasn't the product. It was explaining to retailers why they should shelf a rum that costs six dollars more than the flagships at the bottom of the shelf. You learn quickly that retail placement in spirits is about margin math, not taste. A $32 rum that moves three cases a month will always lose to a $28 rum that moves eight. This isn't a new insight, but people entering the market underestimate how rigid this logic is, even at the premium tier.
What Actually Differentiates Rum Right Now
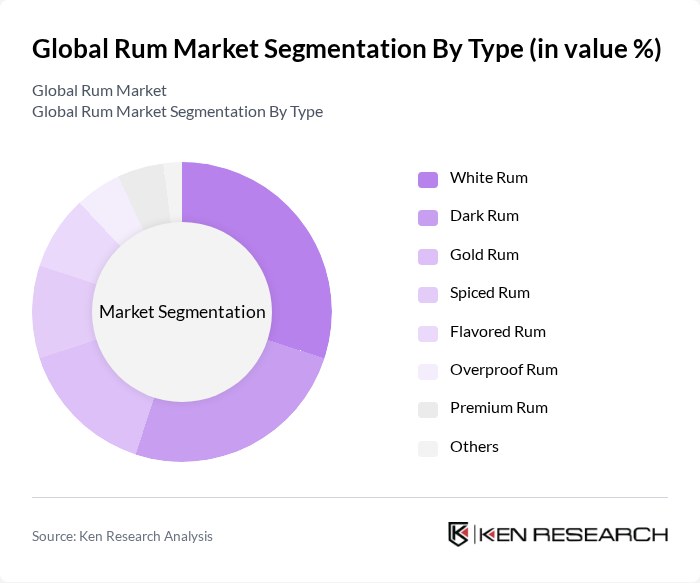
The old taxonomy divides rum into white, gold, dark, and spiced. That framework is dead. The market has moved to a completely different classification system based on production method and aging approach. The three categories that matter are: Aged rum from pot stills: These are usually single-distillery products from places like Haiti, Jamaica, and Martinique. They tend to be heavier, funkier, and more expensive to produce. The congener count from pot still distillation is significantly higher than column still rums, which creates that distinctive molasses-forward, sometimes barnyard character that commands premium pricing. But here's what most people miss: pot still rum has a narrower appeal window. You either love it or you find it undrinkable. The market is smaller but the loyalty is deeper and the margins are healthier for producers who can consistently hit the profile. Aged rum from column stills: This is the bulk of what you see on shelves from Guyana, Barbados, and the Spanish-style producers. Lighter, cleaner, more approachable. The problem here is that the consumer differentiation between products is almost nonexistent. When you're tasting three column-still rums side by side at the same age statement, the variance is minimal. This compression makes brand positioning everything, which is why marketing spend in this segment is so disproportionate to the actual product cost.
Rhum agricole: This is rhum made from fresh cane juice rather than molasses, mostly from the French Caribbean islands. It has an AOC designation system similar to wine. The quality floor is high because the regulations are strict, and the quality ceiling is also high. This is the category where the most interesting innovation is happening right now. Blending with other spirit styles, barrel finishing experiments, and direct-to-consumer sales channels are all finding their strongest footing here. I worked with a producer who was using ex-bourbon barrels that had previously held barrel-aged coffee milk. The resulting rum had a flavor profile that was unlike anything in the category and moved extremely well in specialty shops. That kind of product development takes time and experimentation, but the barrier to entry on the innovation side is lower than you'd think.
Get the Full Details
The Supply Side Problem Nobody Talks About
The biggest constraint on rum growth isn't demand. It's supply chain fragility. Caribbean distilleries operate on margins that leave almost no room for error. A single hurricane season can wipe out two years of inventory if the aging warehouse isn't properly secured. Climate change is making this worse, not better. The industry is still largely dependent on manual labor for harvest and bottling in several key producing regions, and labor costs are rising faster than revenue in places like Haiti and the Dominican Republic. I learned this the hard way when a supplier I was working with had their entire 2019 vintage lost to mold in storage. The warehouse roof had failed during a rain event, and the humid tropical climate turned thirty thousand gallons of aging rum into vinegar within three weeks. There was no insurance that covered this because the policy classified it as "improper storage" rather than natural disaster. The distillery went under eighteen months later. This isn't a rare edge case. It happens often enough that any serious entrant needs to model supply disruption into their projections, not as a hypothetical but as a baseline scenario.
How To Approach This Market If You're Building a Brand
Start with a clear positioning statement that isn't about the flavor profile. The rum market is saturated with descriptions like "smooth," "rich," and "full-bodied." Those words mean nothing to anyone. Pick a specific geographic origin, a specific production method, and build the narrative around that. Single-estate rum from a specific valley in Guyana with a noted distillation date is a far stronger brand foundation than "premium aged rum." Get your distribution channel right before you scale production. I've seen too many small distilleries bottle their way into a corner by going direct-to-consumer because it's easier upfront. DTC margins look better on paper, but they tie up your capital in fulfillment and customer acquisition. A well-negotiated relationship with a regional distributor who actually understands the category will move more volume faster and let you focus on production quality. The trade-off is thinner margins, but in the first three years, margin is less important than market presence. Age statements matter more in rum than in whiskey. A 12-year-old rum with a solid reputation will outsell a 15-year-old from an unknown producer. This is counterintuitive if you're coming from a whiskey background where age is less of a signaling mechanism. In rum, the age statement is the primary trust anchor for consumers who don't already know your brand. Don't skip it to save money. The barrel tax alone makes early release financially attractive, but the long-term brand damage from releasing young product is real and measurable.
The Regulatory Landscape
Each producing country has different rules about what you can label as rum. The EU has strict definitions tied to geographic indication. The US TTB allows more flexibility but requires specific disclosure if the rum is blended with neutral spirits. China's import regulations for spirits have tightened considerably since 2022, and clearance times have roughly doubled. If you're targeting Asian markets, budget at least six months for regulatory compliance work before your first shipment can legally move. Carbon labeling is becoming a requirement in several European markets. This is still emerging but it will affect your cost structure if you're exporting to the EU. I'd recommend getting ahead of this rather than reacting to it after you've already committed to a supply chain. The companies that are already tracking their carbon footprint per liter are the ones that won't be caught flat-footed when these regulations crystallize.
What The Data Doesn't Show
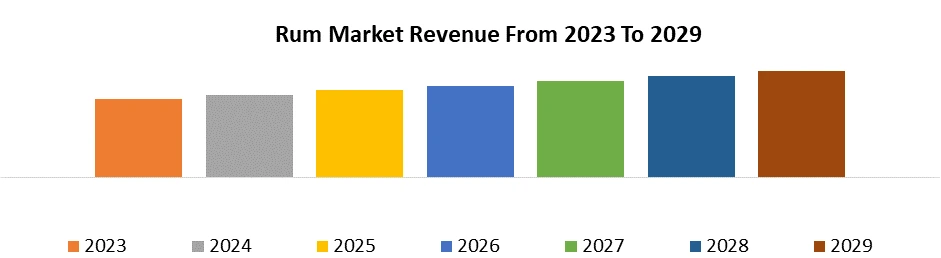
The growth numbers for rum look impressive, but they're skewed by a few large players. Bacardi and Diageo's Captain Morgan and Myers's portfolios account for a significant portion of the reported growth. If you strip out the consolidated players, the independent rum market is growing at roughly four to five percent, which is still good but nowhere near the headline numbers. This means the opportunity for a new entrant is real but smaller than the aggregate statistics suggest. Your addressable market is the growing premium segment, not the total market. Gen Z consumption patterns are also reshaping the category faster than the data reflects. This demographic is drinking less overall but preferring higher-proof, more flavorful spirits. Rum fits this profile well because of its natural sweetness and aromatic complexity. The implication is that the product format matters more than the price point for this cohort. A $40 small-batch rum in a striking package might outsell a $25 rum in traditional packaging. This is the opposite of how younger consumers behaved with tequila and gin a few years ago, where price was the dominant decision factor. The category is moving. The players are shifting. The supply chain is fragile. If you're entering this space with a clear strategy, solid product, and realistic expectations about the timeline, it's a viable market. If you're expecting a quick return based on the growth headlines, you'll be disappointed. The work is in the details: sourcing, aging, distribution negotiation, and regulatory compliance. Those are the things that separate the brands that survive past year three from the ones that don't.