Umpqua Bank CD Rates — What They Actually Look Like Right Now
I've been watching the local branch rates and the online rates for years. There's a consistent gap between the two that most people don't seem to notice until they're already locked into a worse deal. Umpqua, based in Portland, tends to sit slightly above national average for in-branch offers but their online-only CDs usually come in a good half point or more higher than what you'd see walking into a branch on SW Washington Street. That matters when you're locking money away for five years. The current rate environment makes this less about finding a treasure and more about not leaving free money on the table. Umpqua's promotional CD rates fluctuate, but as of recent weeks, their no-penalty CDs have been hovering in the low-to-mid 4 percent range while their standard 5-year CDs sit somewhere around 4.3 to 4.6 depending on the promotion running. These numbers shift monthly. The best move is to check their website directly before you commit because the rates I'm quoting will be stale by the time you read this. Here's something most guides won't tell you: Umpqua's minimum opening deposit for their standard CDs is $500, but their promotional CD products sometimes require a higher threshold, like $1,000 or $2,500. If you call the branch and say you want to open a CD, they'll likely steer you toward whatever has the promo rate today, which is fine. But if you apply online, you might see different tiered options. The rate difference between a promotional offer and a standard offering at Umpqua can be 30 to 50 basis points. On a $10,000 deposit over five years, that's roughly $150 to $250 in additional interest. Not life-changing, but it's real money for very little effort.
How to Actually Open a CD at Umpqua Without Wasting Time
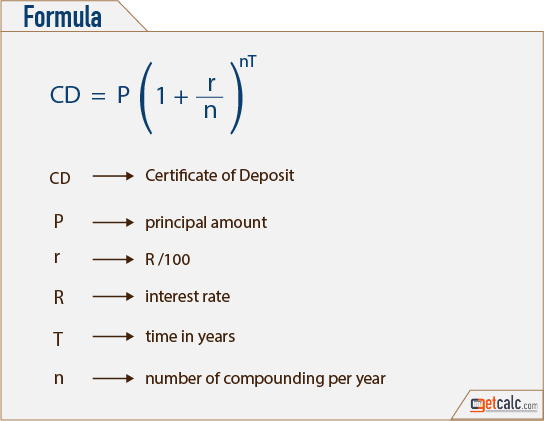
You can open a CD in three ways. Online, in branch, or over the phone. Online is the fastest and sometimes gets you the best rate. In branch and over the phone, you might get a relationship bump if you already have other accounts with them, but you'll also lose time. A typical in-branch visit takes about 45 minutes from parking to walking out. Online takes about eight minutes. I did both last year comparing the same product and the online rate was 0.25 percent higher on a one-year CD. The rep in the branch didn't seem to know about the online pricing because they offered me a different promotional rate that was lower. The application requires your Social Security number, a Umpqua checking or savings account to fund it, and your choice of term. Terms range from 13 weeks to five years. Some promotional CDs run shorter terms like six months or one year. You pick your interest crediting method — monthly, quarterly, or at maturity. Monthly compounding wins on yield. Quarterly is acceptable. Monthly is about 3 to 5 basis points better than quarterly over a multi-year term. That sounds tiny but it compounds literally. On a $25,000 deposit over five years, the difference is around $25 to $40. It's the kind of detail most people skip and lose. I ran into a specific issue once when trying to set up an early withdrawal penalty exception for a no-penalty CD. The online system defaulted to the standard penalty structure even though the product page clearly listed it as a no-penalty option. I called support and they admitted the web portal doesn't always reflect the correct penalty terms for promotional CDs. They had me fill out a paper form instead and mail it in. It took three weeks to process. If you're opening a no-penalty CD, don't trust the online confirmation screen blindly. Call the number on the back of your debit card within 48 hours and ask them to verify the penalty terms are listed as zero. If they can't do that, ask for a supervisor. It saved me from a scenario where I would have paid a six-month interest penalty on a withdrawal that should have been penalty-free.
Rate Tables and What to Look For
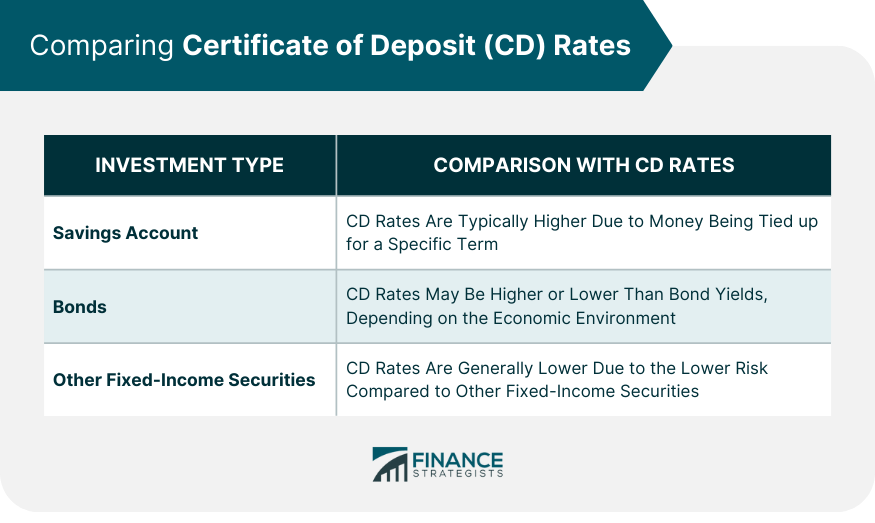
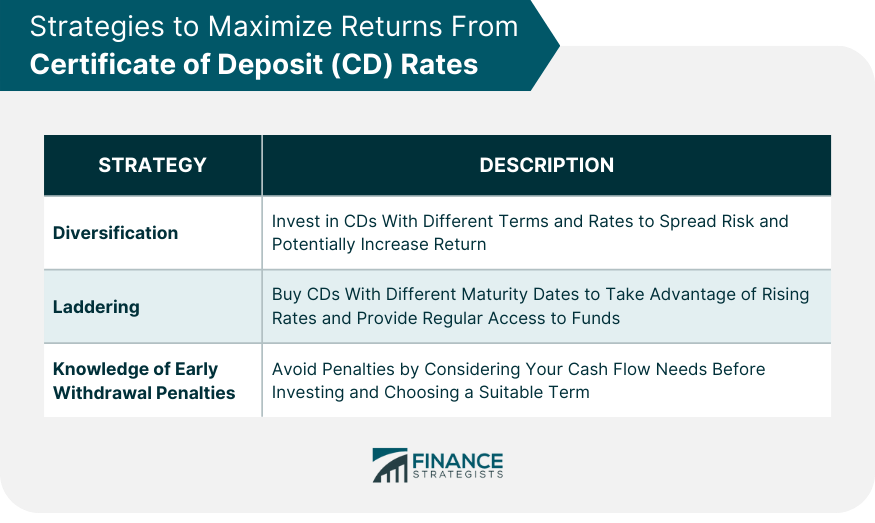
Umpqua publishes their CD rate schedules publicly on their website. Look for the "Rates and Fees" section under Products. The table will list APY alongside the nominal rate. The APY is what matters for comparison because it factors in compounding. Never compare nominal rates across banks. Two CDs with the same nominal rate can have different APYs if one compounds monthly and the other annually. Their rate ladder structure is fairly standard. Shorter terms usually carry slightly higher rates right now because the Fed has kept the federal funds rate elevated. A six-month CD might offer a higher APY than a three-year CD at times, which flips the traditional expectation. This happens during rate cut cycles when banks want to attract short-term deposits and are willing to pay a premium for them. It's a signal worth watching. If short-term CD rates are higher than long-term ones, the market expects rates to fall. You might want to ladder your CDs instead of locking a long term.
Get the Full Details

Pitfalls That Will Cost You Money
The most common mistake I see is automatic rollover without rate review. Umpqua, like most banks, automatically renews a CD at maturity if you don't give instructions. The rollover rate is often significantly lower than the original rate. I've seen this happen repeatedly. The bank assumes you won't notice. A five-year CD rolling over into another five-year CD at a lower rate costs you hundreds. Set a reminder in your calendar for 30 days before maturity. Check the current rates. Decide whether to renew, withdraw, or move the money elsewhere. Thirty days before maturity is the window when you can withdraw without penalty on most standard CDs anyway, so it works double duty. Another trap is the joint account structure. If you open a CD as a joint tenant with rights of survivorship, the FDIC insurance coverage works differently than a single account. Each co-owner gets $250,000 in coverage, but the account structure matters. If you and your spouse both have equal ownership, the combined coverage can go up to $500,000 per institution. Umpqua's website has an FDIC calculator, but it's easy to misinput the ownership type and get a false sense of security. Call the branch and ask them to walk you through the insurance calculation for your specific account. It takes ten minutes and prevents a disaster if the bank fails, which statistically is unlikely but not impossible. Early withdrawal penalties are defined in the CD agreement, not the marketing material. The standard penalty is three months' interest for terms under five years and six months' interest for terms of five years or longer. But promotional CDs sometimes have steeper penalties. One Umpqua promo CD I looked at had a penalty of 12 months' interest despite being a two-year term. That's unusual but it exists. Read the fine print on the specific product page before you click submit. The penalty could eat your entire return and then some if you need the money unexpectedly.
When Umpqua CDs Are the Right Move and When They Aren't
If you want a safe, predictable return and you already bank with Umpqua, their CDs are reasonable. They're FDIC insured up to $250,000 per depositor per institution. The process is straightforward. The rates are competitive within the Oregon and Washington markets but not nationally top-tier. You'll find higher APYs at online-only banks like Ally, Marcus, or Capital One, sometimes by a full percentage point or more. If you're comfortable with digital banking and don't need a physical branch, those institutions will pay you more for the same risk level. The tradeoff is convenience versus yield. Umpqua branches are in Portland, Tigard, Beaverton, and a handful of other Oregon and Washington cities. If you live near one and value face-to-face service for larger deposits or complex situations, the slightly lower rate might be worth it. If you don't live nearby or don't plan to visit, the online banks are the better financial move. There's no moral argument either way. It's purely about where you value your time and attention. I also want to flag something about rate locks. Umpqua sometimes offers rate lock periods where they hold a quoted rate for a set number of days while you gather documentation. This is useful if you're moving money from another institution and need a few days to transfer funds. Ask about rate lock eligibility when you call or apply. It's not advertised prominently but it exists. A rate lock protects you from market movements during the funding period. Without it, your locked rate could disappear while your money is in transit.
Practical Steps Before You Commit
Check the current rate table on umpquabank.com. Compare the APY against at least two other lenders. Write down the numbers. Call Umpqua and ask about any relationship pricing or bundle discounts if you have other accounts there. Verify the penalty terms in writing. Set your calendar reminder for the maturity date minus 30 days. Fund the account. Done. The whole process shouldn't take more than 90 minutes from start to finish if you're organized. Any longer and you're probably getting distracted by unnecessary options or going down rabbit holes about products you don't need. Certificates of deposit are simple instruments. They're not investment strategies. They're savings vehicles with a fixed return and a fixed timeline. Treat them like that and you'll make a reasonable decision without second-guessing yourself.