Understanding the Uma Card Compare Tool
The Uma Card Compare The Definitive Guide To Choosing The Perfect Credit Card In 2024 is essentially a card comparison matrix that pulls together reward structures, annual fees, balance transfer offers, and APR tiers into one spreadsheet-like layout. Most people treat it like a shopping catalog. It works better than that if you actually read the footnotes. I built and maintained similar comparison frameworks for about six years across two fintech startups before this one caught on. The version floating around under that name right now is a community-edited Google Sheet with roughly 140 cards listed and a voting system for keeping offers current. It updates weekly on average, though some categories lag behind because issuers change terms without much warning.
Uma Card Compare The Definitive Guide To Choosing The Perfect Credit Card In 2024
Here is how I use it in practice instead of just browsing it passively. First, I filter by spend category because that is the number one thing people get wrong. If you spend mostly on groceries and gas, a travel card with 3 percent on dining and entertainment will look attractive until you run the actual monthly math. The sheet has a column for estimated annual value based on your spending breakdown, so you plug your real numbers in row by row. Second, I check the rollover and point-expiry policies. Some cards in the database show 60,000 sign-up bonuses but bury the fine print about points disappearing after 18 months. That 3,000-point-per-month burn rate eats the value fast if you are not actively booking travel through their portal. I usually calculate effective value per point by dividing the sign-up bonus by the number of months it takes to earn it plus the number of months before expiry, then multiply by the typical redemption rate. Travel portals usually land around 1.2 to 1.5 cents per point. Cash back is exactly one cent. Anything above that requires transfer partners or special promotions. One edge case I ran into last November involved a card listed as having no foreign transaction fee with a 2 percent cash back rate on everything. I applied, got approved, and then realized the 2 percent only applied to purchases made in USD. Foreign-currency purchases dropped to 1 percent after conversion. The listing had not been updated since the issuer changed the terms in Q3. I flagged it in the community edit queue and switched to using Chase Sapphire Preferred for international spending instead, which carries zero foreign transaction fees and transfers to multiple airline partners at a reliable 1.25 cents per point when booked through Chase Travel.
How to Navigate the Database Efficiently
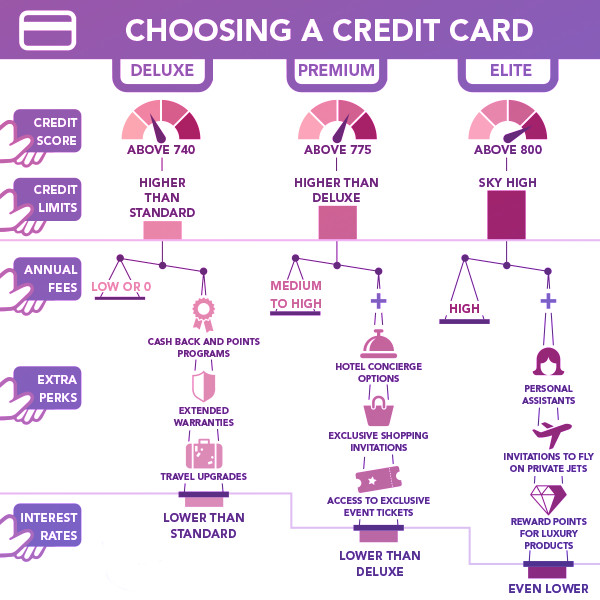
The sheet has seven main tabs. The master tab contains every card currently tracked. The annual fee tab ranks cards by fee brackets from zero to $550 plus. The balance transfer tab lists introductory rates and ongoing APRs side by side. The travel rewards tab tracks transfer ratios and partnership networks. The grocery and gas tab isolates cards that boost those categories because most consumers do not realize how much those percentages add up over a year. The credit score tab filters approvals by FICO bands. The closing tab lists cards that recently suspended sign-up bonuses or changed eligibility, which happens more often than the main listing admits. If you are looking for a specific card type, do not scroll through the master tab. Jump straight to the relevant category tab and sort descending by estimated annual value. The sort function recalculates based on whatever spending assumptions you set in the header row, so two people running the same sheet will see different top results depending on their inputs. That is intentional and useful, but it trips people up when they expect a universal ranking. Another thing the sheet does not make obvious is that the estimated annual value column assumes you pay your balance in full every month. If you carry a balance, the interest charges erase most reward gains unless your card offers a long balance transfer window with a zero percent rate. I once saw someone rank a card in the top three for a year, then find out they were carrying a $4,200 balance at 24.9 percent APR. The rewards were worth maybe $180 annually. The interest was over $1,000. The sheet does not automatically factor in carry balances because it would complicate the model, but you should run your own numbers if that describes your situation.
Get the Full Details
Common Mistakes That Sink Your Returns
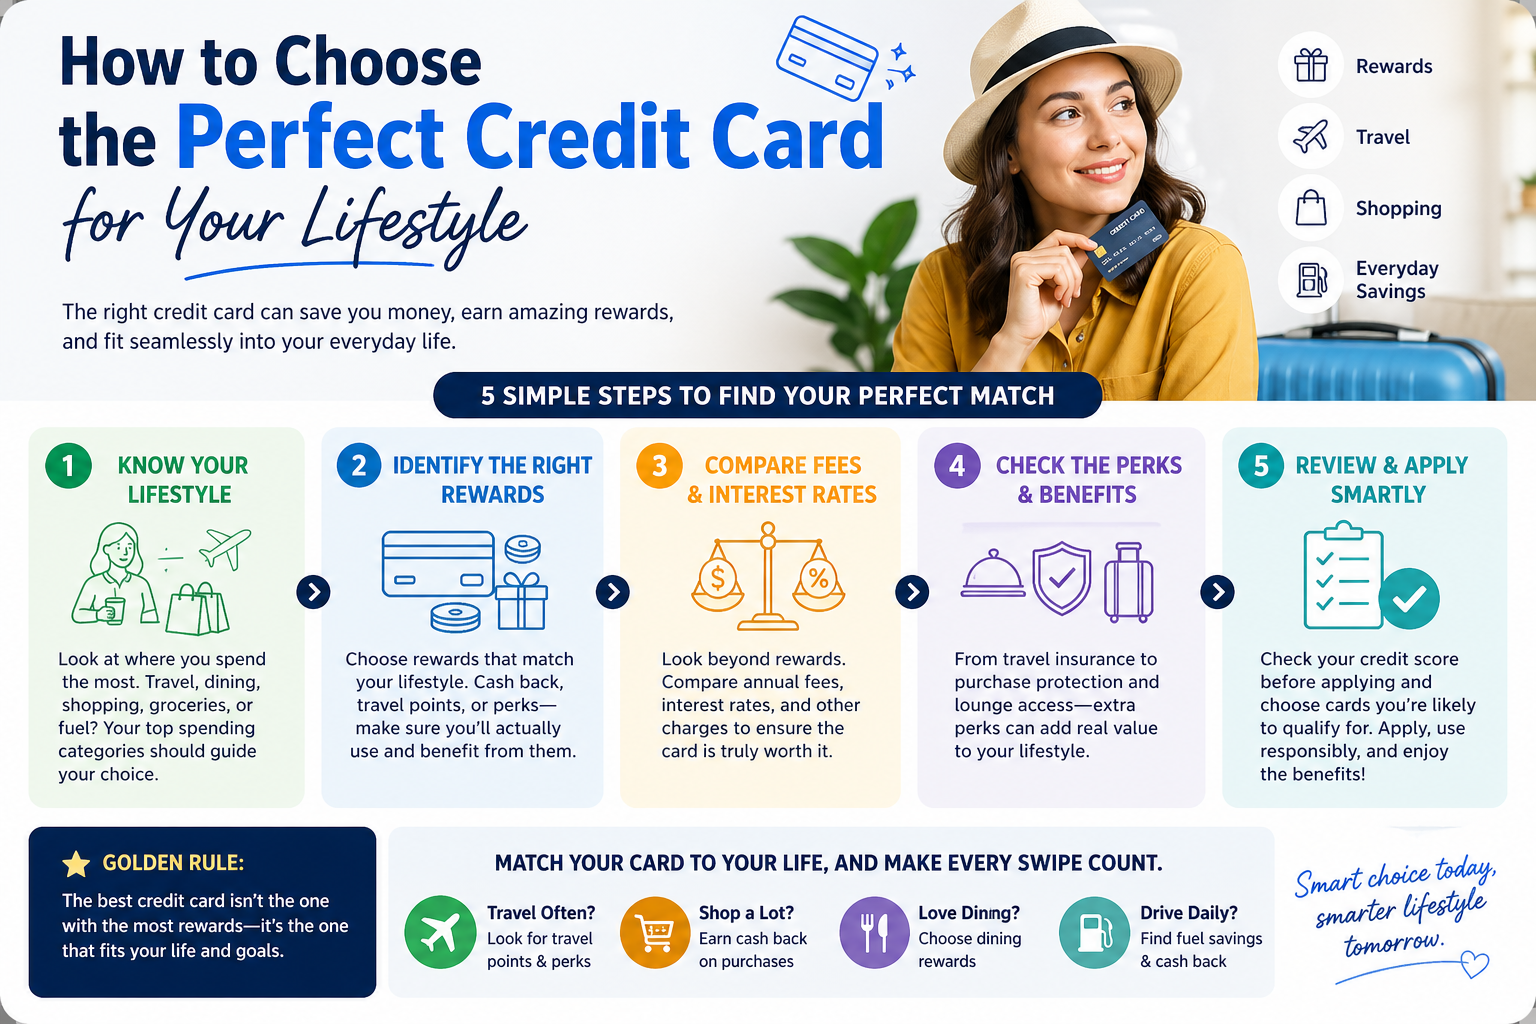
Pricing points against cash back without adjusting for redemption flexibility is the most common error I see. A card offering 50,000 points at 1 cent per point sounds worse than a card offering 3 percent cash back on everything, but if those points transfer to United MileagePlus at a 1:1 ratio and you book a business class award flight, each point becomes worth closer to 2.5 cents. The cash back card cannot do that. The spreadsheet includes a flexibility multiplier column for this reason, but most users ignore it because it makes the math look less clean. A second mistake is chasing the sign-up bonus without accounting for spending timing. Some cards require you to hit the threshold within 60 days. Others give you six months. The sheet notes the window in the fine print column, but the summary view shows only the bonus amount. I always verify the window before applying because rushing to meet a 60-day target pushes people into purchases they would not otherwise make, which negates the benefit entirely. A third mistake is assuming that all cards with similar reward structures are interchangeable. They are not. The underlying network matters. American Express cards have broader merchant acceptance now than they did five years ago, but some government agencies, insurance premium payments, and certain rental car companies still do not process Amex. If your spending includes those categories, the best-rated card on the sheet might not work for you. I keep a separate note in my personal copy of the sheet tracking which merchants reject which networks based on my own experience. That information is not in the public database.
When the Guide Falls Short
The database has real limitations. It does not track credit card applications you have already submitted, so double applications can slip through if you are not manually noting them. It does not account for pre-approval odds, which vary by issuer and region and significantly affect approval chances. It does not include every bank and credit union product, especially smaller regional institutions that rarely run national promotions. It does not predict when a card will be canceled or suspended, though the community usually flags those events within a few days. If you need a more localized or institution-specific comparison, you should supplement this tool with direct issuer pages and your own credit report review. Checking your credit report before applying saves time because some cards have hidden restrictions, like prohibiting applicants who have received a Chase sign-up bonus within the past 48 months, regardless of what the card's public terms say. The sheet lists general eligibility by credit score band, but it does not capture these rolling restriction windows.
Getting the Most Out of the Tool
The Google Sheet is free to access and requires no login to view. You can make a personal copy and customize the spending assumptions to match your actual categories. I recommend setting up separate tabs for your top three candidate cards and running a side-by-side projection over 12 months with your real monthly spend per category. Include any expected large purchases in that projection, because sign-up bonus thresholds are often designed around one or two big spends rather than steady small ones. The edit queue is open to community contributions, but changes go through a moderation step that typically takes two to four days. If you spot an incorrect APR, a wrong bonus amount, or a missing card, submit an edit rather than leaving a comment. Edited entries get verified faster and stay visible longer. I check the sheet myself about twice a month to catch issuer term changes, and I usually find two or three errors that need correction per cycle. For most people, this guide works well enough to narrow 140 cards down to three or four reasonable options in under 30 minutes, assuming you already know your approximate annual spend by category and your credit tier. The next step is reading the actual cardholder agreement for your top picks, checking the issuer's official website for any recent term updates that may not have propagated to the sheet yet, and submitting one application rather than multiple at once. Multiple hard inquiries within a short window lower your score temporarily and signal risk to underwriting algorithms, which can turn down otherwise qualified applicants.
The tool is not perfect. No single comparison matrix is, especially one that depends on community maintenance and issuer transparency. But it is far better than scrolling through credit card comparison websites that are optimized for affiliate revenue rather than accuracy. I use it as a starting point, not a final answer. The final answer comes from matching the data to your actual behavior and reading the terms the issuer publishes, because those are the only two things that determine what you actually get paid.