Paying Your Ulta Credit Card
I learned the hard way that Ulta's payment system doesn't always update in real time, even when you see confirmation on your screen. You can pay three different ways. The website through the account portal, the mobile app, and automated phone payment if you prefer not to type. Each one routes to the same account but processes at slightly different speeds depending on when you schedule the payment. Online payments posted same business day if you submit before 8 PM ET. Payments submitted after that window, or on weekends and holidays, hold until the next business day. I ran into a situation where a purchase happened Friday night using my card, the payment posted Saturday morning showing zero balance, but when I walked into the store Sunday for a return they couldn't process it because the transaction hadn't actually settled yet. The payment portal is accurate but the bank's settlement cycle is separate from what displays.
Where to Pay Your Ulta Credit Card Payment How To Pay Manage And Maximize Benefits
Log into ulta.com and go to the Ulta Credit Card section under your account dashboard. From there you can make a one-time payment or set up automatic monthly payments. The app works the same way if you have the My Ulta application installed. Phone payments require you to have your account number ready and call the number listed on the back of your card. They run through a voice system that asks for your account number, social security digits, and payment amount. Set up autopay if you want to avoid late fees entirely. You can choose the minimum due or the full statement balance. I recommend full balance. The minimum payment option keeps interest accruing and compounds over time. There's no penalty for paying early, so even if you auto-draft the full amount the day after your statement closes, it posts correctly and you won't carry a balance.
Managing Your Account
Your monthly statement breaks down purchases, returns, rewards redemption, and any interest charges. Review it each month when it arrives. There's a section near the bottom that shows available credit and current balance. If you've been making purchases all month and haven't paid anything yet, these two numbers look identical. After you submit a payment they split, which means your current balance reflects what you spent while available credit reflects what you could still spend. Checking your transaction history helps you catch duplicate charges, refunds that didn't apply correctly, or unauthorized activity. I once missed a $47 charge that posted twice for the same foundation purchase. It took three calls and eight minutes to get it reversed because I had the receipt with the transaction number handy. Without that receipt the verification process dragged on much longer. Two-factor authentication is available on the account portal. Enable it. You'll get a code via text or email whenever you log in from a new device. It adds about five seconds to your login process but prevents someone who got your password from accessing your billing information.
Get the Full Details
Rewards and Benefits
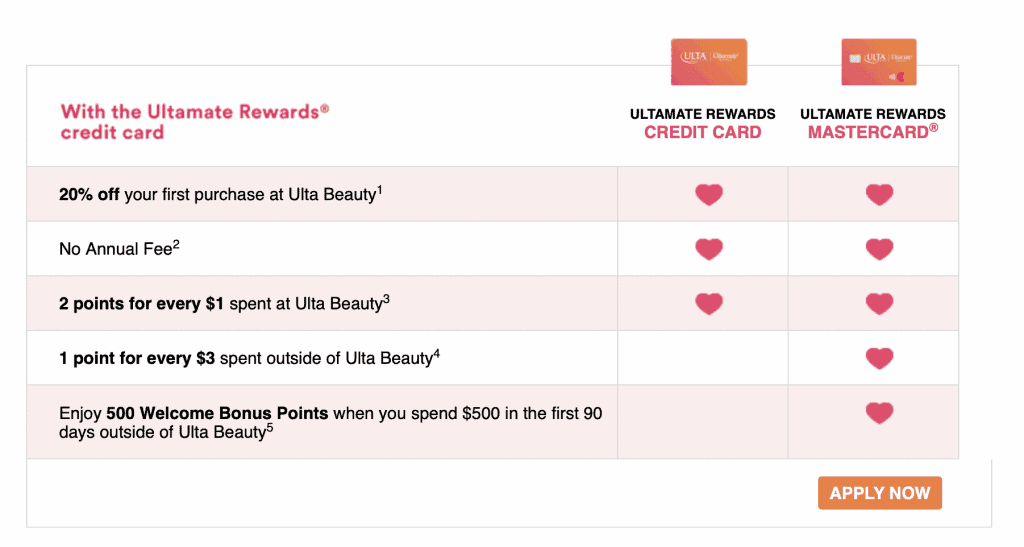
The Ulta Credit Card earns points on purchases. Standard rate is one point per dollar. You can redeem those points toward future purchases, and there are occasional bonus point promotions that temporarily boost the rate to two or three points per dollar depending on the campaign. Check the rewards section before you shop during a promotional period. I redeemed 3,000 points during a 3x promotion window and applied them to a high-ticket skincare purchase. The value per point was higher during that window than at any other time. There's an annual fee of zero dollars on the standard Ulta Credit Card. That's one of the reasons it's worth keeping open if you shop there regularly. You also get early access to sales events, including the half off sale that happens twice a year. Members get access a day before the general public. I've saved meaningful money by shopping the member-only window for select categories. Interest rates apply to carrying a balance. The rate is variable and tied to the prime rate, so it changes periodically. I wouldn't carry a balance on this card unless necessary. The rewards don't offset the interest cost if you're paying finance charges month to month. Pay in full each statement cycle and you extract maximum value without any downside.
Things That Go Wrong
Here are the problems I've encountered and how I handled them. Sometimes a payment shows as submitted but hasn't posted after 24 hours. Call customer service with your confirmation number. The representative can look up the batch file and confirm whether it's queued for processing or stuck. I had one instance where the payment sat in pending status for two days because of a routing mismatch between the portal and the bank. Another issue is rewards points not posting after a purchase. This happens more often than you'd think, usually when the merchant category code doesn't register correctly at checkout. If points are missing after seven business days, request a retroactive posting through customer service. Bring your receipt. They can usually add the points within a few days of submitting the request. Limits can feel tight if you're making large purchases close to your statement closing date. Your credit limit applies regardless of whether you've paid down the balance. A $500 purchase on a card with a $600 limit leaves you with $100 of headroom until that payment posts. I learned this after trying to buy a gift set and getting declined. Waiting until after the statement generated and paying down the balance cleared it up immediately.
Practical Tips
Pay before the due date, not on the due date. Processing delays happen and the system isn't foolproof. Submitting payment two or three days early gives you buffer. Set calendar reminders if you tend to forget. Keep digital receipts. The transaction history on the portal helps but having your own record of what you bought and when makes disputes easier to resolve. I screenshot every purchase over $50 now. It takes ten seconds and has saved me twice when something went wrong with returns or point postings. Watch for promotional financing offers. Sometimes Ulta runs seasonal deals where purchases above a certain threshold get deferred interest for six or twelve months. Read the fine print carefully. If you don't pay the full balance by the end of the promotional period, interest accrues retroactively from the purchase date. That can turn a seemingly good deal into an expensive one. I declined one of these offers because the math didn't favor me. The deferred interest meant I'd have to track multiple payment deadlines carefully. Not worth the complexity for my situation.

The card works at Ulta stores and online. It also works at some third-party locations that partner with the Ulta brand. Check before you use it outside the main retailer. I tried using it at a pop-up kiosk inside a department store and got declined because the merchant wasn't registered in the system. Returned to Ulta directly and the same purchase went through without issue.


