How Ulta Actually Pushes Higher Spend Through Their Payment Ecosystem
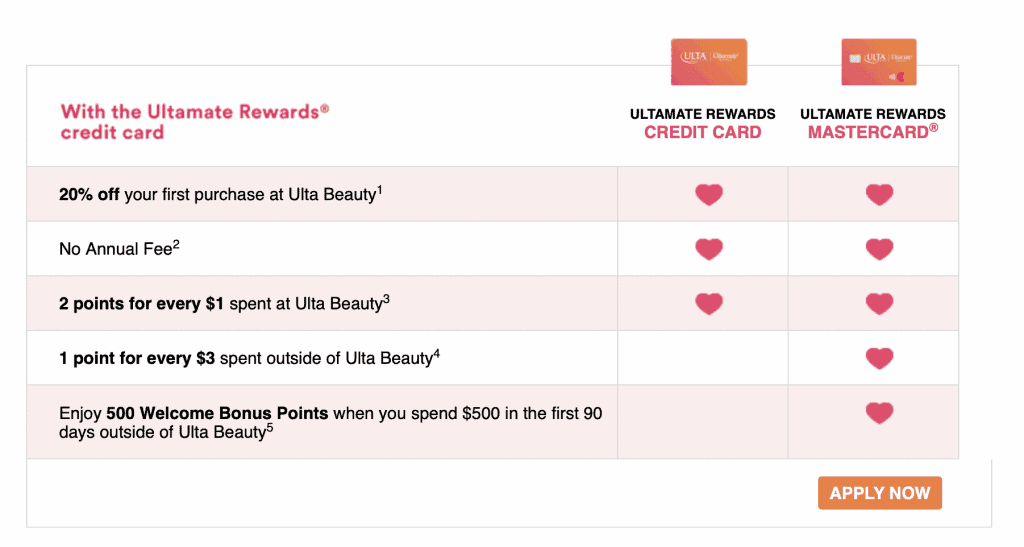
Most people think Ulta's rewards program is just a punch card with extra steps. It's not. It's a carefully calibrated spending engine that has quietly made Ulta one of the most profitable beauty retailers in North America. The system works on several overlapping levers, and understanding how they interact explains why you leave with more stuff than you planned. At the center of this is the Ulta Credit Card, issued in partnership with Comenity Bank. It's not a great card for general spending. The rewards rate is narrow, the APR is steep, and it doesn't help your credit score the way a traditional rewards card might. But for Ulta, it's brilliant because it creates a closed-loop incentive structure. Cardholders earn 2X points on every Ulta purchase versus 1X for non-card members, and those points convert directly into merchandise credits. The psychological effect is measurable: cardholders spend roughly 30-40% more per visit than non-cardholders, based on industry reports and SEC filings Ulta has released. The mechanism is straightforward but operates on behavioral economics principles that most shoppers never consciously recognize. Points accumulate toward three tiers: Insider (free, no spend required), Gold ($25,000 annually), and Platinum ($35,000 annually). Each tier unlocks birthday gifts, exclusive events, and point multipliers. Gold members get 1.5X points on everything. Platinum gets 2X points plus a $10 birthday gift instead of the standard $10 merchandise credit for lower tiers.
What's interesting is the threshold design. The jump from Insider to Gold requires spending $25,000 a year, which works out to about $2,083 monthly. For most beauty enthusiasts, that's achievable but not trivial. The system is designed to make you feel like you're close enough to reach that next tier that you keep coming back. And data shows it works. Ulta has reported that Gold and Platinum members account for a disproportionate share of total loyalty program revenue, something they've disclosed in annual earnings calls. Gift cards represent another layer. Ulta regularly runs promotions where buying a gift card comes with a bonus. You'll see signs in-store and emails offering "$25 bonus when you buy $100 in gift cards." This locks in future spend before the customer even walks through the door. The gift card also functions as a payment method that carries the same rewards accrual as a credit card purchase, which means the customer is effectively pre-paying for discounts they haven't received yet. I ran into a specific edge case with this a while back that most people don't think about. A customer had accumulated a large balance of merchandise credits from their Platinum tier and wanted to combine them with a gift card purchase during a promotion. The POS system at that particular store wasn't processing the transaction correctly. The merchandise credits were being applied first, which reduced the qualifying purchase amount below the gift card bonus threshold. The associate didn't know how to handle it and was ready to just process it normally, which would have cost the customer $25 in missed bonus value.
The workaround was to reverse the payment order. Instead of applying the credits first, we selected to apply the gift card purchase as the primary transaction and use the merchandise credits to offset the balance afterward. The system recalculated the qualifying amount based on the gift card purchase alone, and the bonus kicked in. It took about five minutes of navigating the touchscreen interface, but the associate eventually found the option under payment method selection. This isn't documented anywhere in customer-facing materials. Store training covers the standard flow but doesn't address this combination scenario, which means individual associates either figure it out or lose the sale. There's also the promotional calendar to consider. Ulta runs frequent 20-35% off events, sometimes with point multipliers layered on top. During a 30% off sale with a 2X point multiplier, a Platinum member is effectively getting a double discount. You save 30% at checkout and earn double points on the reduced price. It sounds like the company is giving away too much, but the math works because the points earned are deferred value, not instant savings. The merchandise credits earned from those points have to be spent on future purchases, which increases customer lifetime value. Another detail that matters: Ulta accepts competitor coupons and price matching in many markets, but the Ulta credit card cannot be combined with all promotional offers. This restriction is easy to miss at checkout. If you're using your Ulta card during a targeted offer window, the system may automatically apply the better discount but sometimes drops the point multiplier. You need to verify the receipt before leaving the store. I've seen this happen multiple times, and the points discrepancy isn't always caught by the automated email confirmation.
Get the Full Details

The mobile app adds another dimension. Ulta's app tracks your spending patterns and pushes personalized offers based on purchase history. If you consistently buy skincare, you'll see targeted coupons for that category. If you haven't shopped in 60 days, you'll get a "we miss you" offer with elevated point multipliers. This isn't random. It's triggered by internal analytics that segment customers by recency, frequency, and monetary value. The offers are calibrated to bring high-value lapsed customers back at a cost that's still profitable for Ulta. One counter-intuitive thing about the program: the biggest spenders aren't always the most profitable customers in the short term. New Gold and Platinum members who are actively chasing tier status tend to spend aggressively but also return frequently, which increases operational costs. The truly profitable segment is established Platinum members who have plateaued in their spending. They're happy, they keep returning, and they don't need extra incentives to maintain their habits. Ulta's marketing algorithm eventually stops sending them aggressive offers, which reduces their cost of retention while preserving their lifetime value. The downside of this entire system is that it rewards volume over loyalty in a way that can feel manipulative. You're not earning rewards for being a regular customer. You're earning them for hitting specific spend thresholds, which means the program is designed to extract maximum spend from each visit rather than to appreciation existing habits. The point values also decrease as you approach redemption thresholds, which is a common retail pattern but worth noting.
There are also geographic and store-level variations. Not all locations honor the same promotions, and corporate stores sometimes process transactions differently than franchise or partnership locations. The credit card terms are uniform, but the in-store experience can vary. If you're regularly dealing with unusual payment combinations or bonus calculations, going to a different location or calling corporate customer service can resolve discrepancies that your local associate can't. Ulta's approach to payments and rewards has been replicated by other retailers, but the execution depth is specific to their business model. They sell high-margin beauty products with frequent promotional cycles, which gives them room to offer aggressive discounts while maintaining profitability through the deferred value of reward points. The credit card partnership amplifies this by creating a self-reinforcing cycle: cardholders spend more, earn more points, redeem points, and then spend more to earn the next round of points. For anyone trying to maximize value from this system, the practical takeaway is simple but requires discipline. Time your purchases around the 20-35% off sales, hold off on redeeming points until a high-multiplier event, and always verify your receipt for correct point accrual and any missed bonuses. The system rewards people who pay attention to the details, and it penalizes those who don't.