
The Ulta Store Card and How Financing Actually Works
The Ulta Beauty credit card comes in two flavors, and people keep confusing them. The blue card is a standard store card you can use anywhere in the US at Ulta. The platinum card is invite-only and gives you more points per dollar, but you still can only use it at Ulta. Neither card works elsewhere. This matters because when you see an offer like "20% off your first order" or "free shipping," those apply differently depending on which card you have. The financing side is where things get messier. Ulta partners with Comenity Bank, and they offer promotional financing at checkout. You might see something like "10% off if you pay in full within 6 months" or "no interest if you pay within 12 months." The fine print on these offers is dense, and most people gloss over the parts that actually matter.
Ulta Beauty Credit Card Breakdown Navigating Financing Offers For Beauty Shoppers
I learned about the hidden trap with these offers after a friend bought a $400 skincare set during a holiday sale. She got the "no interest if paid in full within 6 months" deal, spent the next half-year paying the minimum balance each month, and when the promo period ended, Comenity Banks slapped retroactive interest on the entire original purchase amount. Not just the remaining balance. The whole $400. She owed about $80 in back-interest on top of what she still owed. That is how deferred interest works, and it is the single most common way people get burned by store card financing. Deferred interest is not the same as a standard zero-percent APR promo from a major bank. With a real bank card, you pay interest only on what you owe each month. With deferred interest, missing the target by even one day means the issuer recalculates the entire purchase as if you never had a promotional rate at all. The rate they apply is typically the standard purchase APR, which for the Ulta card sits around 29.99% as of my last check. That compounds daily, so the longer you miss, the faster it grows.
How the Promotional Offers Are Structured
Ulta runs several recurring promo tiers. The most common ones I have seen over the years: Pay in full within 6 months, no interest. This is the bread-and-butter offer, usually available on purchases over a certain threshold, typically $299 or more. The downside is that if you do not pay the entire balance by the end of month 6, you get hit with deferred interest on the full amount from the original purchase date. Pay in full within 12 months, no interest. Less common, usually reserved for larger purchases or seasonal promotions. Same deferred interest trap if you miss the deadline. The minimum purchase requirement is usually higher, often $599 or above.
Get the Full Details
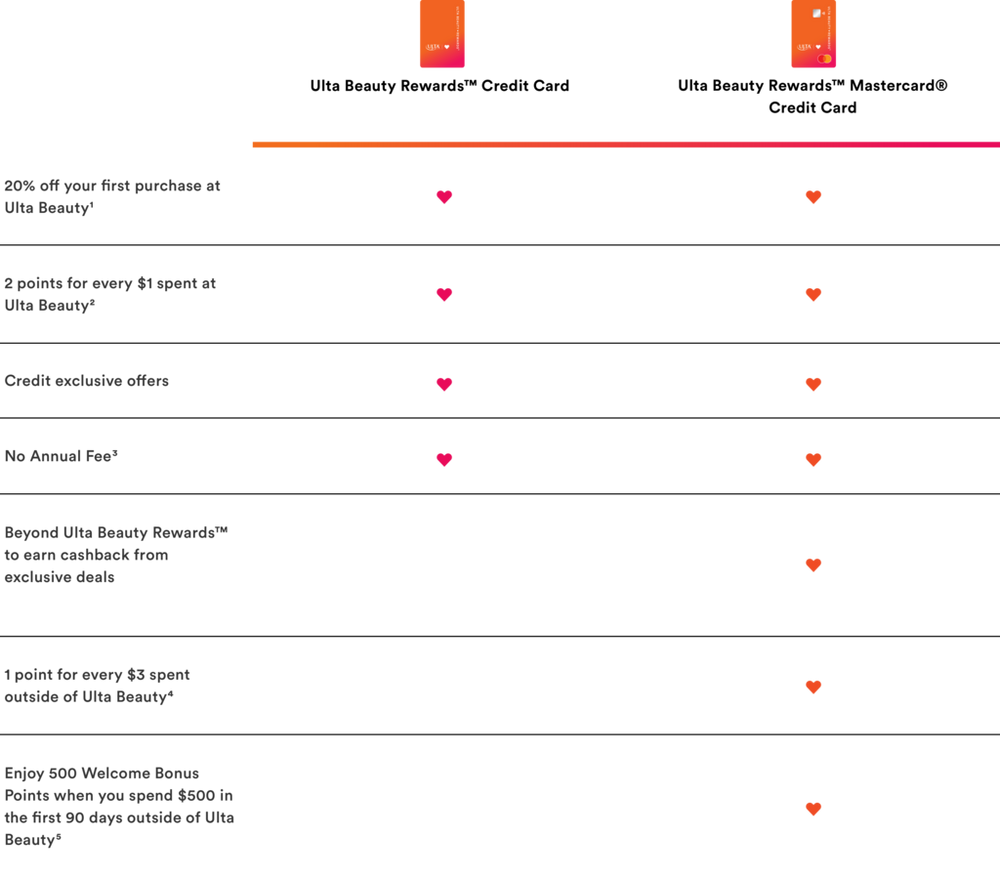
20% off your purchase if you open a new Ulta credit card. This is a sign-up bonus, not financing. You get the discount at checkout, but the card itself carries a high standard APR. The math works out okay if you pay the balance in full the next statement, but if you carry a balance, that 20% discount gets eaten quickly by the interest charges. Free shipping on orders over a certain amount. This applies to both card types but is more consistently offered to platinum members. It is not financial savings in the traditional sense, but it adds up over a year if you order frequently.
The Math Behind Deferred Interest
Let me walk through a concrete example. Say you buy $600 worth of perfume and skincare during a promotion that offers 12 months same as cash. You decide to pay $50 per month. After 11 months, you have paid $550. You still owe $50, so you make that final payment in month 11. Everything looks fine. Now suppose instead you pay $40 per month. After 11 months, you have paid $440. You still owe $160. You think you have time, so you pay $80 in month 11 and plan to clear the rest in month 12. You are wrong. The promotional terms require the FULL balance to be paid by the end of month 12. If you have even $1 remaining after month 12, the deferred interest clause triggers, and Comenity Bank recalculates interest on the entire $600 at your purchase APR from day one. At 29.99%, that is roughly $180 in interest over 12 months. You end up paying $780 for a $600 purchase. The workaround is simple but requires discipline. Set up automatic payments for the full monthly amount, or better yet, calculate the exact monthly payment you need before you check out. Divide the purchase total by the number of months in the promo, round up to be safe, and set a calendar reminder for the final payment date. Do not rely on memory.
What the Credit Score Requirements Actually Are
Comenity Bank does not publish official credit score requirements, and they never will. From what I have observed across applications and from friends who have been declined, you generally need a credit score in the fair range, which means roughly 640 to 699. People with scores below 600 get declined at a high rate. People with scores above 720 are almost always approved, sometimes even pre-approved. The Ulta platinum card tends to have slightly higher thresholds than the standard blue card. I have noticed this because friends with good credit but limited history got approved for the blue card and then later invited to upgrade to platinum after several months of responsible use. The invitation usually comes through mail or email, and you cannot apply for platinum directly without one. Hard inquiries matter here. Applying for the Ulta card triggers a hard pull on your credit report, which drops your score by a few points temporarily. If you are already shopping around for other credit products, stacking multiple applications within a short window compounds the damage. Space them out by at least six months if you can.

The Rewards Structure and Its Limits
The Ulta credit card earns points, not cash back. The standard card gives you 2 points per dollar on Ulta purchases and 1 point per dollar on everything else. The platinum card gives you 3 points per dollar on Ulta and 1 point everywhere else. Points convert to Ultamate Rewards certificates, and the current redemption rate is roughly 100 points equals $3.50 in rewards. So if you spend $1,000 a year on Ulta products with the standard card, you earn 2,000 points, which converts to about $70 in rewards. That is a 7% return on Ulta purchases, which sounds decent until you consider that most cash-back cards offer 2% on everything with no spending category restrictions. The Ulta card only gives you elevated returns at one retailer. The real value comes from stacking. Ulta runs 20X point events periodically, usually for certain brands or during sale periods. If you time your purchases to coincide with these events, you can effectively triple or quadruple your rewards rate. I track these events on a spreadsheet and only make larger purchases during the high-multiplier windows. It takes work, but the difference between earning 2 points per dollar and 20 points per dollar is massive over a year.
When the Ulta Card Is Not Worth It
There are clear scenarios where opening an Ulta credit card is a bad move. If you already carry debt on other cards, adding another account with a nearly 30% APR is irresponsible. If you tend to miss payment deadlines, the deferred interest trap will punish you. If you shop at Ulta less than once a quarter, the rewards will barely cover the hassle of managing another account. Also worth noting: Comenity Bank has a reputation for slow customer service and rigid dispute processes. If you have a billing issue, expect to wait on hold for 20 to 40 minutes, and be prepared to send documented proof via mail rather than resolving things over chat. I learned this the hard way when a promotional discount did not apply to my order and spent three weeks back and forth with their support before it was corrected.
Practical Steps Before You Apply
Check your credit score first. If it is below 620, you are unlikely to be approved and will only damage your credit with a hard inquiry. Run a free report through annualcreditreport.com or your bank's app and confirm the number matches what Comenity will see. Calculate your planned annual Ulta spending. If it is under $300, the rewards will not justify opening a new account. If it is over $600, the 2 points per dollar on the standard card starts making sense, especially if you can catch a 20X event. Set up payment reminders before you use the card for any financed purchase. Use your phone calendar, set two reminders: one for the monthly due date and one for three days before the promotional period ends. The third reminder is critical because it gives you time to make a partial payment and then clear the balance before the clock runs out.
Do not use the card for non-Ulta purchases if you are carrying a balance. The 1 point per dollar on outside purchases is worthless compared to the interest you will accumulate. Keep the card strictly for Ulta spending, and pay the full statement balance every month unless you are intentionally using a promotional financing offer that you have calculated to within a dollar. The platinum card is worth pursuing if you qualify and spend enough, but do not chase it aggressively. The invitations come on their own timeline, and repeatedly applying will not speed things up. Focus on maintaining on-time payments and reasonable utilization on the blue card, and the upgrade will arrive when Comenity decides you are ready.


