Understanding How Ulta's Credit and Bill Pay System Actually Works
Most people stumble into the Ulta Rewards Credit program without really reading what they're signing up for. I've seen it happen hundreds of times on forums and in customer service threads. You get distracted by the "20% off your first purchase" banner and swipe without thinking about the reward structure that kicks in after that initial splash. Let me walk through what it actually costs you, where the discounts hit, and what the convenience factor really looks like in practice. Ulta offers a few different payment options, and they're not all created equal. The main one people ask about is the Ulta Rewards Credit Card, which is issued by Comenity Bank. There's also the standard Ulta gift card system and the ability to pay with multiple forms of payment in a single transaction. When I first started dealing with this system back in 2019, I assumed the rewards credit card was just a straightforward store card. It's more layered than that, and the nuances matter if you're trying to actually save money rather than just spend it faster. The rewards credit card operates on a tiered earn-back system. You earn 2X points per dollar on Ulta purchases, 1X on everything else, and occasionally there are promotional boosts that push it to 3X or 4X on certain categories. The points convert to dollars at a rate of 100 points equaling $3. This means every $100 you spend nets you roughly $6 back in rewards under normal circumstances. That's not a bad effective discount if you were going to shop there anyway, but it starts to look different when you factor in the annual fee situation and the interest rates.
Fee Structure and What They Don't Tell You Upfront
There's no annual fee on the Ulta Rewards Credit Card, which is one of the reasons it's popular. But Comenity Bank charges a standard APR around 29.99%, which is on the high end for store cards. If you carry a balance month to month, that 20% discount evaporates quickly. I learned this the hard way in 2021 when I forgot to pay my statement in full for two consecutive months. The rewards I'd earned were completely wiped out by the interest charges, and I ended up paying more than I would have with a debit card. Never again. There are also foreign transaction fees of 3% if you use the card internationally, though this is rare since Ulta is primarily a domestic retailer. Late payment fees can reach up to $40 depending on your state and the severity of the delay. These aren't hidden in the fine print exactly, but they're buried deep enough that most people don't notice them until it's too late. The best approach is to set up autopay for at least the minimum payment, then manually pay off the full statement balance before the due date arrives.
The Convenience Factor and Real-World Friction Points
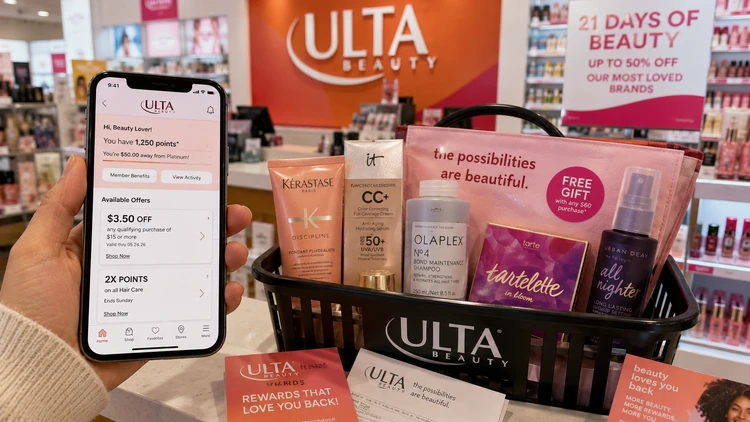
On the convenience side, the Ulta app lets you link your rewards account and credit card together, which streamlines checkout considerably. You can earn points automatically, track your rewards balance, and access exclusive member-only sales without having to present a physical card. The digital wallet integration works on both iPhone and Android. When you're in-store, you just show the barcode in the app and the cashier scans it. It takes about three seconds per transaction once you're used to it. However, I hit a real snag last year when trying to use my rewards credit card to pay down a previous balance while simultaneously making a new purchase during a mega sale event. The system wouldn't let me apply more than my available credit to the new transaction, even though I hadjust made a payment that should have restored my limit. I ended up having to call customer service, wait on hold for 22 minutes, and then the rep had to manually adjust something on their end. The workaround I found is to make sure any payments post fully before attempting large purchases. Wait at least 24 hours after making a payment before using the card for a big transaction. That single habit has saved me from this problem entirely since I discovered it.
Get the Full Details
Discount Strategies That Actually Work
The Ulta Beauty Club membership is free and gives you access to birthday rewards, early sale access, and occasional promotional codes. Stack this with the rewards credit card and you're looking at legitimate savings. I've run the numbers on several shopping trips and the combined discount typically lands between 15% and 25% off your total bill depending on sale timing and point accumulation. The trick is timing your purchases around Ulta's 21-day sale cycle, which happens roughly every three weeks. During these sales, you can often get 20% to 35% off select categories while simultaneously earning double points on the rewards card. Another strategy that works better than most people realize is the Gift Card stacking method. Ulta occasionally runs promotions where you get a gift card back when you spend a certain amount with the rewards card. I've seen offers like "spend $50, get a $10 gift card." If you plan your purchases around these offers and combine them with sale pricing and point earnings, the effective discount can exceed 30%. It requires more planning than impulse shopping, but the math checks out.
When the System Doesn't Work For You
Not everyone should use the Ulta rewards credit card. If you have a history of carrying credit card balances, this is a bad tool for you. The high APR will absorb any rewards you earn and then some. If you're someone who needs the discipline of a debit card to control spending, stick with that. Ulta also doesn't accept the rewards card for third-party payment processing on their website in all cases, which can be frustrating if you're trying to use points toward a large order that gets routed through a different payment gateway. There's also the issue of rewards expiring. Ulta points don't have an explicit expiration date according to their terms, but they do reserve the right to close inactive accounts after 12 months of no activity. If you use the card once a year and then forget about it, you could lose your accumulated points. Keep the account active with at least one small purchase every few months if you want to maintain your balance.
How to Set It Up Properly
Apply through the Ulta website or in-store. The in-store application is faster and the approval rate tends to be higher because the associate can submit your application with your membership data already pulled up. Once approved, link the card to your Ulta app account immediately. Enable autopay for the minimum payment to avoid late fees, then set a calendar reminder for five days before your statement due date to pay the full balance. This two-step process costs you nothing and protects you from the interest trap that catches most people. Track your rewards balance weekly in the app. Most people check it once a month or not at all, which means they miss opportunities to redeem before a sale ends or before they accidentally spend down to zero on an item they didn't need. A quick weekly check takes 30 seconds and prevents that mistake.