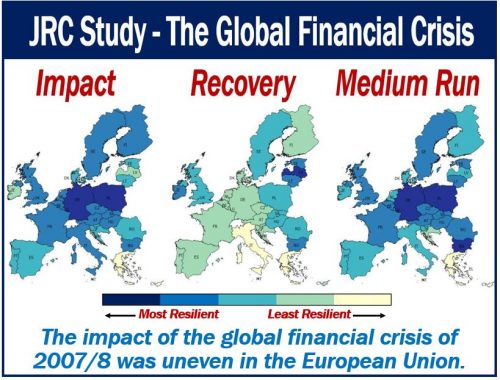
Understanding the UK's Financial Turbulence
The UK didn't have a typical recession in 2008. It had a banking crisis dressed up as a general downturn. That distinction matters more than most summaries let on. The root cause was straightforward enough: British banks were leveraged to somewhere between twelve and fifteen times their capital base, they held massive portfolios of mortgage-backed securities, and the housing market was the collateral backing most of it. When the US subprime market caught fire, UK banks were already breathing the smoke. I spent years working in credit risk around that period, and one thing nobody really explains well is how interconnected the UK banking sector was to its own housing market. It wasn't just that banks lent money to buy houses. They lent against houses that were themselves financed through the same lending chain. RBS alone had mortgage and lending exposure equivalent to roughly 150% of UK GDP at its peak. When asset values dropped, the entire system contracted simultaneously. There was no external shock to absorb the losses because the shock was internal. The Lehman Brothers collapse in September 2008 was the catalyst, but the UK would have been in serious trouble regardless. Interbank lending froze. Credit markets seized. The government had to guarantee interbank lending at short notice, then recapitalize four of the largest banks: RBS, Lloyds, HBOS, and Northern Rock. The total cost of the banking rescue eventually ran to over one hundred billion pounds, though the exact figure depends on whether you count unrealized losses on held assets and subsequent share price movements.
UKs Global Financial Crisis Causes Impact Recovery
The causes break down into three overlapping categories. First, the monetary policy environment of the early 2000s kept interest rates relatively low, which fueled demand for housing and encouraged excessive borrowing. Second, financial regulation had been deregulated since the Big Bang in 1986, and the Financial Services Authority operated under a light-touch philosophy that didn't stress-test institutions against severe housing market downturns. Third, there was a cultural dimension: UK households historically carry higher debt-to-income ratios than most European counterparts, and pre-2008 lenders were releasing credit with minimal verification in many cases. The impact hit differently across regions and demographics. London and the Southeast took the hardest immediate hit on banking employment and commercial real estate. The North and Wales saw deeper structural damage through manufacturing decline that predated the crisis but worsened significantly during the recession. Young people entering the job market in 2009 and 2010 faced unemployment rates above twenty percent in some sectors. Homeownership dropped sharply among under-thirty-five age groups, and it has never fully recovered to pre-crisis levels. I remember sitting through internal meetings in 2009 where senior risk officers were genuinely uncertain whether the bank would survive the next quarter. Not metaphorically. There were scenarios modeled where liquidity ran out before the government guarantee could be fully deployed. The worst-case estimates for RBS alone showed potential losses exceeding two hundred billion pounds at the time. What saved the institution was a combination of government capital injection, asset separation, and the fact that the Treasury essentially owned the bank for several years afterward.
The recovery phase was the most politically contentious part. Austerity measures introduced from 2010 onward aimed to reduce the deficit, but the timing and pace remain debated among economists. The Office for Budget Responsibility estimated that fiscal consolidation reduced GDP by roughly four percentage points cumulatively over the recovery period compared to a slower withdrawal scenario. That's not a small number. It translates to actual lost output, closed services, and prolonged hardship for vulnerable populations. On the positive side, UK banks were stress-tested more rigorously after 2009 than any previous era. The Prudential Regulation Authority and Financial Conduct Authority split responsibilities, leverage ratios improved, and liquidity coverage requirements brought the system closer to international standards. By 2015, major UK banks were passing the PRA stress tests with comfortable margins. Commercial lending resumed. GDP returned to pre-crisis trend levels by late 2017. But the recovery has significant caveats. Productivity growth in the UK has been stagnant since 2008, worse than almost any other advanced economy. Real wage growth didn't recover to pre-crisis levels until well into the 2020s, and even then it was modest. Regional inequality widened. The Bank of England's quantitative easing program, which expanded the monetary base by over seven hundred billion pounds, primarily supported asset prices rather than broad-based income growth. House prices in London and the Southeast rose dramatically, creating a new generational divide between homeowners and renters.
Get the Full Details
One thing I find consistently overlooked in summaries is the role of the swap mechanism with the US Federal Reserve. In October 2008, the UK secured a fifty billion dollar currency swap line that prevented a complete dollar funding freeze for British banks with USD operations. Without that, the crisis would have deepened substantially. Most people don't know this happened, and it deserves more recognition as a critical intervention point. The long-term structural consequences include a weakened pound post-Brexit referendum, which both compounded and was compounded by the original crisis damage. The UK's current account deficit, which widened significantly during the boom years, remains a vulnerability. Banking sector concentration is higher than it was before 2008, which creates systemic risk that hasn't been fully addressed. And the public debt-to-GDP ratio, which was around sixty-five percent before the crisis, has stayed elevated at between one hundred and one hundred ten percent depending on measurement methodology. If you're looking at this from a personal finance angle, the practical takeaway is that the crisis reshaped the UK's economic landscape in ways that are still playing out. Asset inflation has favored property owners. Wage stagnation has hit younger workers disproportionately. The regulatory environment is stricter but not fundamentally different in how risk is calculated. Banks are better capitalized but still prone to the same cyclical behavior that caused the crisis in the first place.
The recovery isn't complete in any meaningful sense for large sections of the population. It's statistically complete if you measure by aggregate GDP. The gap between those two statements is where the actual story lives.