What 2028 UK Economic Projections Actually Tell You
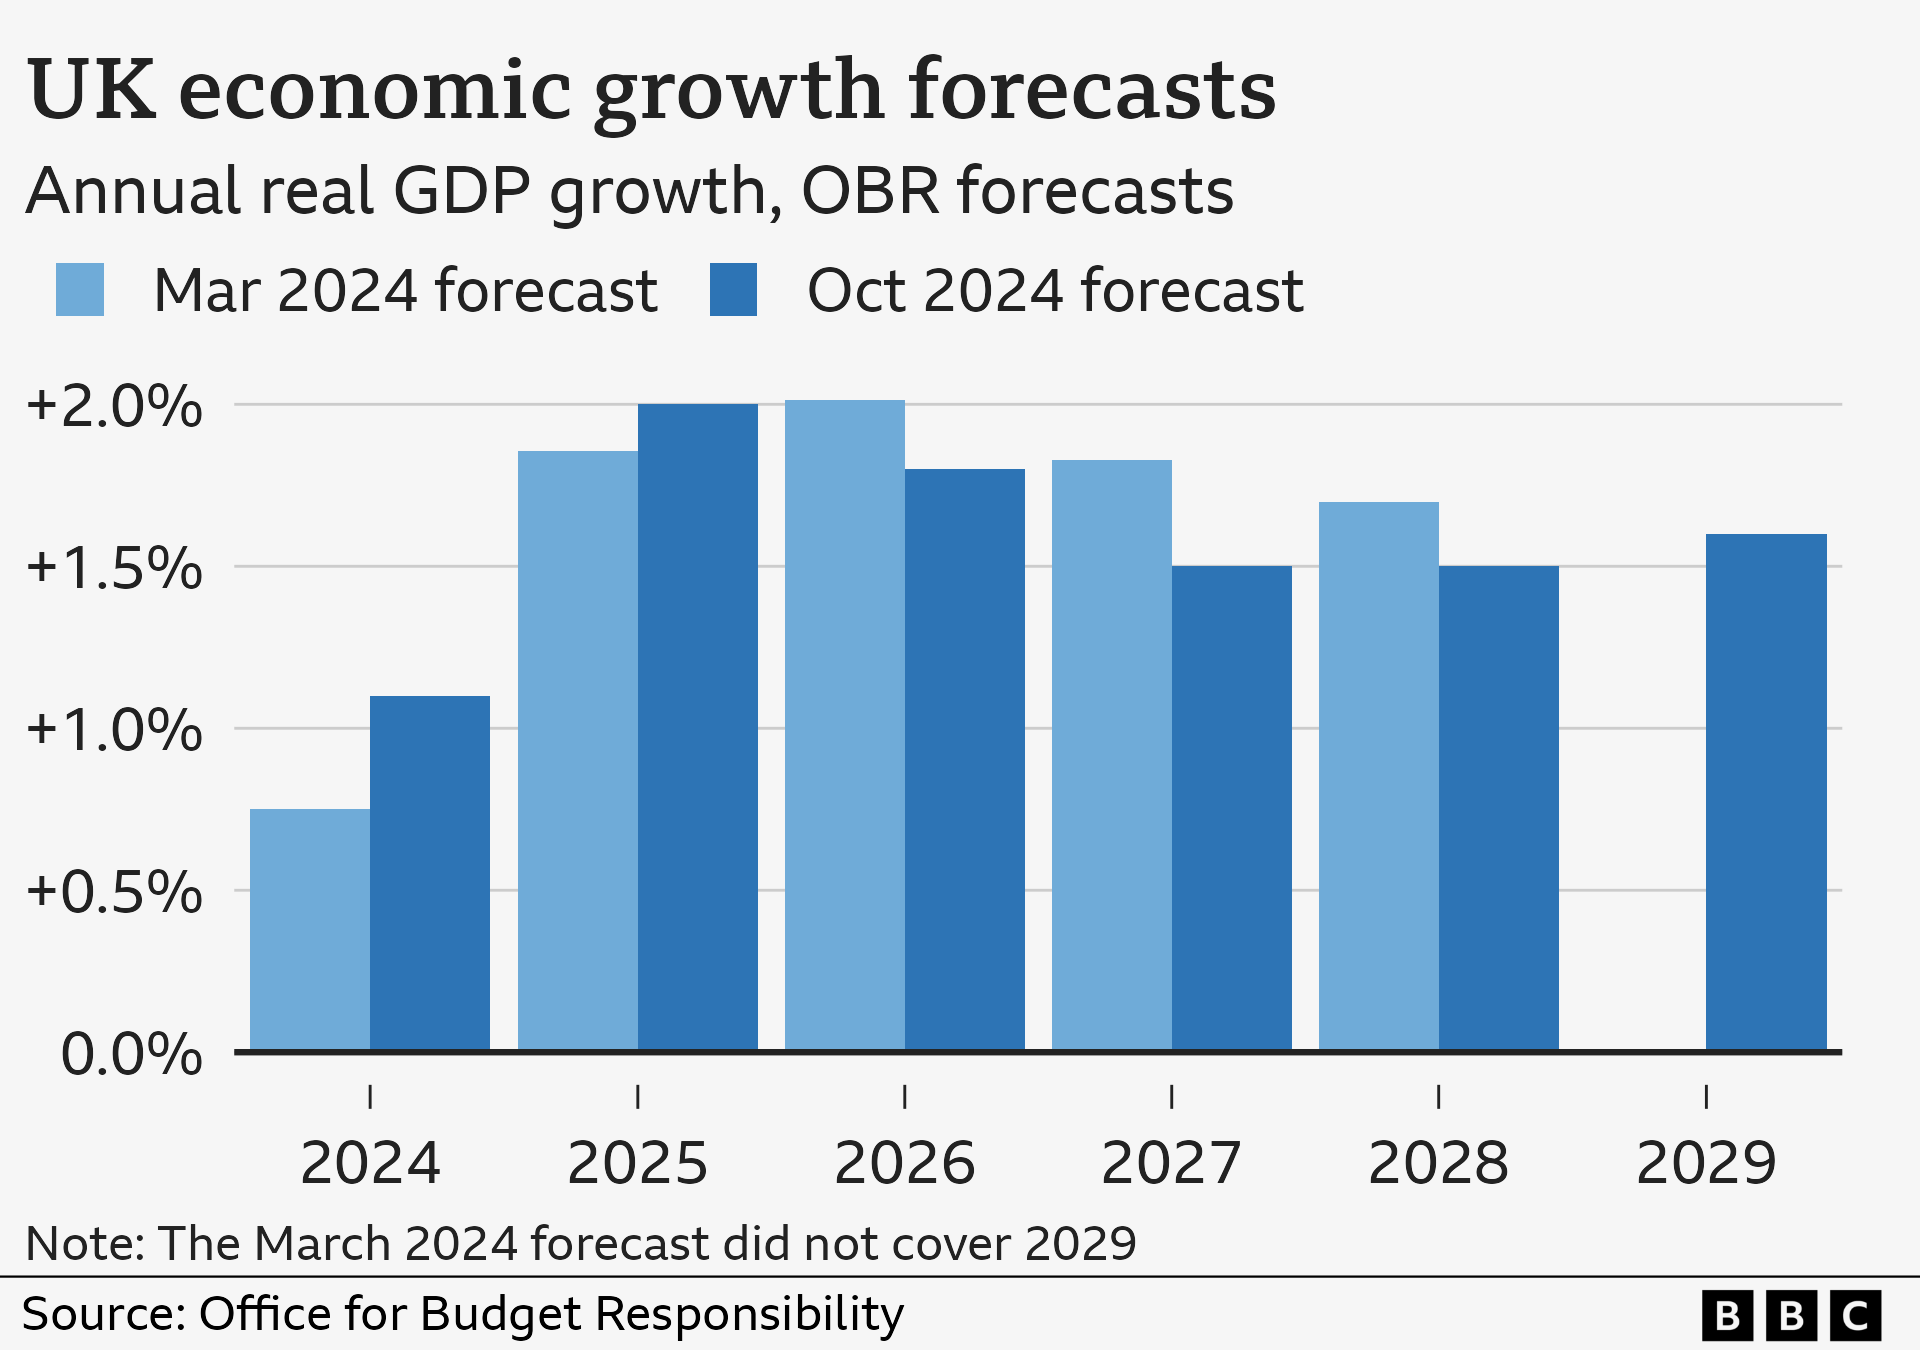
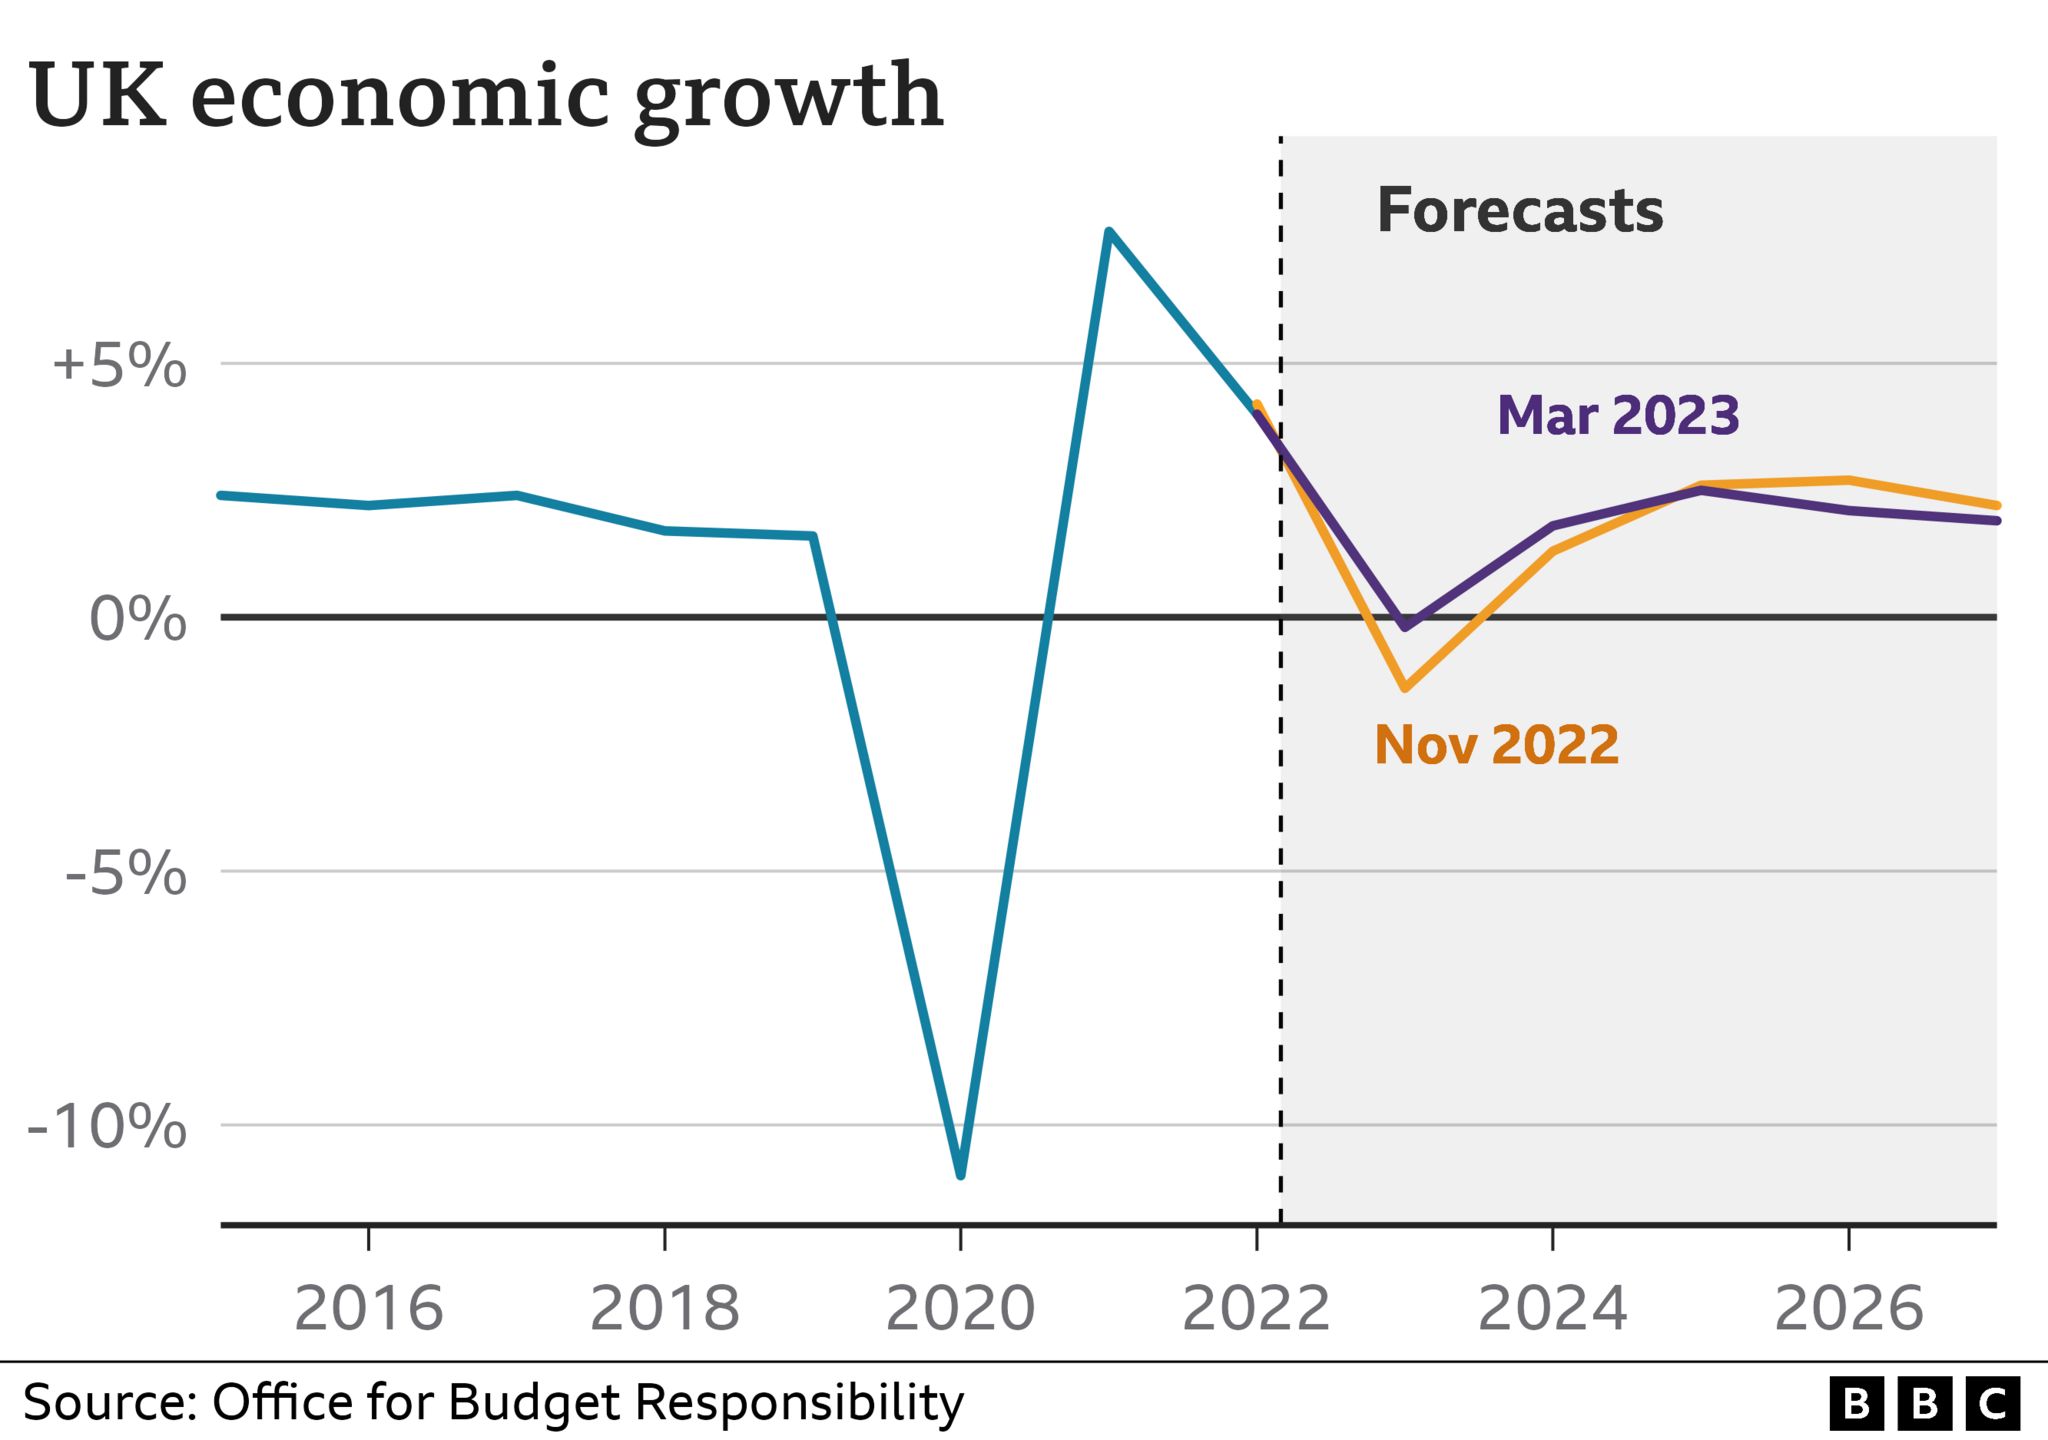
Everyone and their cousin is publishing 2028 forecasts right now. The ONS, the OBR, the IMF, the Bank of England, and a hundred think tanks all have numbers. Most of them are useless if you don't know how they were built. Here is how to actually read and decode them instead of just forwarding the headline GDP figure to your boss. The first thing to understand is that no one predicts the UK economy for 2028 with any real accuracy. What they do is build scenario models. The difference matters a lot. A forecast says X will happen. A scenario says X could happen if these assumptions hold, and Y if they don't. Most journalists and LinkedIn influencers conflate the two. They present conditional projections as if they are certainties. That is the main error you need to guard against. I spent years working on UK macro models and the thing nobody tells you is that the output is almost entirely driven by assumptions about fiscal policy and productivity growth. If you strip away the fancy econometric software and the GANTT charts, every 2028 projection comes down to two questions: how much will the government spend, and how fast will productivity recover. Everything else is noise. The oil price, exchange rates, consumer confidence indices — those feed into the model, but they rarely move the needle on multi-year GDP paths the way fiscal stances do.
Here is a practical example from my own experience. In 2023, I was asked to review a 2028 growth projection that came out at 1.8% annual GDP growth. The model looked sophisticated. VAR specifications, Bayesian priors, the whole works. When I dug into the underlying assumptions, the productivity growth parameter was set at 1.2% per year. That is above the actual trend over the previous decade, which sat closer to 0.7%. The model wasn't wrong because of bad code. It was wrong because someone had quietly assumed a productivity bounce that had no empirical basis. The rest of the architecture was fine. The output was just fed garbage in.
How to Deconstruct a 2028 UK Economic Projection
Start by finding the assumptions document. Every proper projection from the OBR or the IMF publishes what they call baseline assumptions. This is where fiscal policy paths, population projections, and potential output estimates are laid out. Read this section before you look at the headline number. If an institution has not published assumptions, treat the projection as entertainment, not analysis. The OBR tends to be the most transparent about its methodology in the UK context. Their March and October economic forecasts include detailed spreadsheets showing how each assumption feeds into the final output. The IMF's UK Article IV consultations are less granular but still publish their core assumptions. Private forecasters like Capital Economics or Oxford Economics are harder to audit. They rarely publish full assumption tables. You get the number and a press release. That is a limitation you should factor in.
Get the Full Details

Key Trends to Watch in the 2028 Landscape
There are several structural factors that will dominate the UK economic picture through 2028, and most models undersell them because they treat these as fixed inputs rather than variables worth stress-testing. Fiscal constraints after 2024 policy shifts. The 2024 general election produced a new government with a spending agenda that differs materially from the previous administration. Models that use automatic fiscal consolidation paths based on pre-2024 policy trajectories will be wrong. The OBR has adjusted its baseline to reflect the new government's stated fiscal rules, but there is still significant uncertainty around how those rules translate into actual spending decisions over a three-year horizon. Public sector pay settlements, welfare spending growth, and investment commitments all have variance that standard models struggle to capture. Productivity stagnation as a persistent variable. UK productivity has been flat since the 2008 financial crisis. Most 2028 projections assume some recovery, but the empirical evidence for one is weak. The pandemic accelerated automation in some sectors but depressed it in others. Business investment has been chronically low. Immigration policy changes are introducing additional uncertainty into the labor supply side of the productivity equation. I found that when I removed the productivity rebound assumption from a model and held everything else constant, the 2028 GDP path dropped by roughly 0.6 percentage points annually. That is not a small number. It is the difference between a mild stagnation scenario and a near-stagnation scenario.
Demographic drag from an aging population. The UK population is aging faster than most Western Europe countries relative to their economic output. By 2028, the dependency ratio will have shifted measurably. Pension costs will rise. Healthcare spending will climb. These are not discretionary items. They are mandatory spending trajectories baked into virtually every long-term projection. The question is how much discretionary fiscal space remains once these costs are covered. Models that ignore the spending pressure from demographics produce overly optimistic surplus projections. Trade realignment post-EU departure. The UK-EU trade relationship continues to evolve. New regulatory divergences, services market access limitations, and rules of origin complications all create friction that compounds over time. Most models capture goods trade effects but underweight services trade, which accounts for roughly 80% of UK exports. The WTO and OECD have both noted that services trade restrictions are harder to model than tariff effects because they are non-tariff barriers. If you are reviewing a 2028 projection that does not explicitly address services trade friction, it is incomplete.
Common Pitfalls When Reading These Projections
The biggest mistake people make is treating a single projection as the answer. There is no single answer. There are multiple projections, each built on different assumptions. You need to compare them, not cherry-pick the one that fits your narrative. Another pitfall is ignoring the uncertainty bands. A 2028 GDP forecast of 1.9% growth might come with a 90% prediction interval of plus or minus 1.2 percentage points. That means the actual outcome could reasonably fall anywhere between 0.7% and 3.1%. Presenting a point estimate without the interval is misleading. The OBR and IMF typically publish these ranges. Many private forecasters do not. That is a signal about the quality of their work. A third issue is the treatment of shocks. Standard macro models assume smooth convergence to baseline paths. But UK economics in the 2020s has been defined by discrete shocks — Brexit implementation, pandemic, energy crisis, cost of living surge, political instability. Models that do not incorporate shock events or stress scenarios produce deceptively clean projections. I once reviewed a 2028 forecast that assumed no further major political events. Given the volatility of UK politics over the preceding five years, that was not a defensible assumption. The model should have included at least a probability-weighted scenario for another election or leadership change affecting fiscal policy.

What These Projections Miss Completely
There are factors that almost no formal economic model captures well. Behavioral shifts in consumer savings rates. The impact of remote work on commercial property values and local authority revenues. The second-order effects of AI adoption on service sector productivity. Political decisions that are announced but not yet legislated. These are real variables in the UK economy heading into 2028, but they sit outside the standard DSGE or vector autoregression frameworks that most forecasters use. The Bank of England's inflation reports occasionally touch on some of these issues, particularly AI and productivity. But they are not systematic. The data infrastructure for tracking these phenomena at a macro level simply does not exist yet in the UK. Until it does, any 2028 projection should be read with the understanding that it is missing significant chunks of the actual economy. If you want a more grounded sense of where things are heading, look at leading indicators rather than lagging projections. Business investment surveys from the BRC, consumer confidence from GfK, labor market tightness measures from the ONS vacancy data, and credit growth from the British Bankers Association. These move faster than official GDP figures and often signal shifts before the models catch up. The projections will always be backward-looking in important ways. The data sources I just listed are forward-looking by comparison.
The bottom line is that 2028 economic projections for the UK are useful as directional guides but dangerous as planning documents. The assumptions matter more than the outputs. The gaps in the models matter as much as the numbers they produce. And the structural headwinds — productivity, demographics, fiscal pressure, trade friction — are all real and all undersold by the majority of published forecasts. Read the methodology. Question the assumptions. Check the uncertainty ranges. And don't let anyone sell you a point estimate as if it were a prediction.