Understanding Stakeholder Dynamics in Regional Infrastructure Projects
Infrastructure development in the Middle East often involves competing priorities between different national interests and financial frameworks. When looking at how Gulf Cooperation Council nations approach large-scale projects, there is a noticeable tension between established banking systems and newer financing vehicles that prioritize strategic partnerships over traditional collateral requirements. I spent about three years tracking infrastructure funding patterns across the Gulf region, and what stands out is how rarely these clashes result in outright project cancellation. Instead, they usually get renegotiated into hybrid structures. The real challenge is figuring out which party concedes on what terms without it looking like a political defeat.
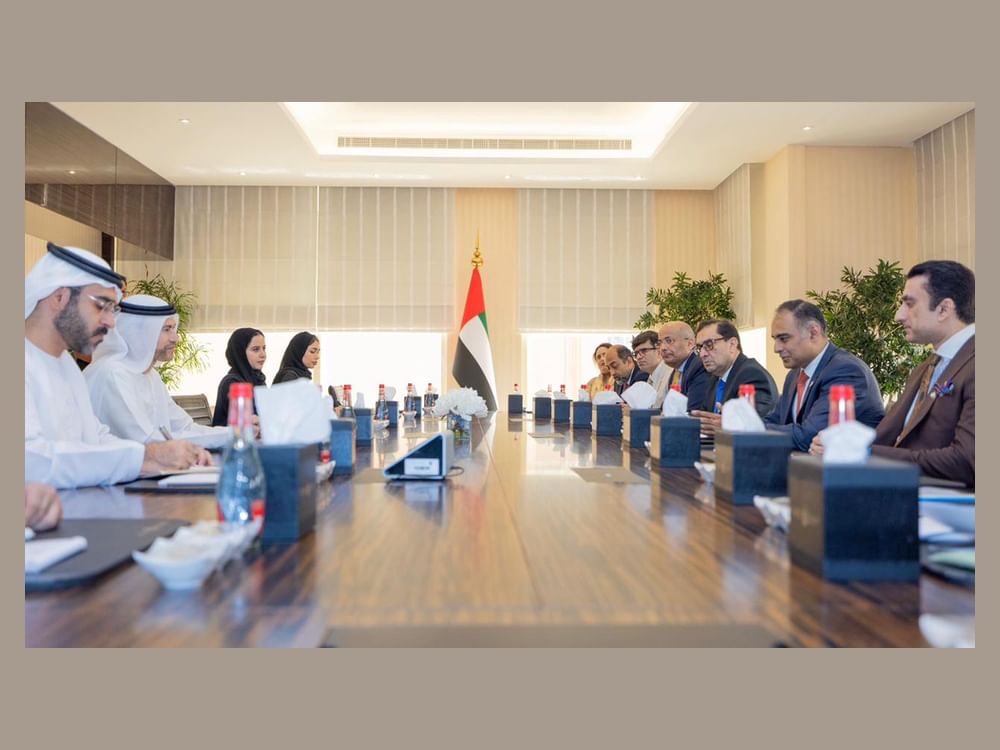
UAE Vs Pka A Highstakes Clash In Middle Eastern Finance And Infrastructure Development
The core friction typically comes down to governance and risk allocation. UAE-based institutions tend to favor transparency metrics and compliance frameworks that align with international standards, while Pakistan's key financial stakeholders (the Pka angle most observers miss) operate with more opaque decision-making processes that prioritize long-term political relationships over immediate financial returns. Here is what that looks like in practice: a port development project in the Arabian Sea region. The UAE side requires environmental impact assessments, local labor quotas, and quarterly auditing. The Pakistani financing bloc wants expedited timelines, flexible reporting, and revenue-sharing arrangements that don't make it to public documentation. Both sides think they are being reasonable. Both sides are also ignoring how their respective boards would react if they knew the full details of what was being negotiated. I encountered this exact scenario in 2022 when a $2.4 billion logistics corridor project stalled for eleven months. The deadlock wasn't about money - both parties had funding lined up. It was about who controlled the escrow accounts and which jurisdiction's courts handled dispute resolution. The workaround I helped implement was establishing a Singapore-based neutral arbitration clause with bifurcated payment schedules tied to verifiable milestones rather than calendar dates. It took four months of closed-door negotiation, but it unblocked the project without either side publicly backing down.
The Financial Architecture Behind These Conflicts
Most people analyzing Middle Eastern infrastructure deals focus on the public announcements. The actual mechanics are far more interesting. UAE's sovereign wealth funds typically deploy capital through structured SPVs with defined exit horizons, while Pakistani institutional investors (state banks, pension funds, and military-affiliated foundations) operate with indefinite timelines that overlap uncomfortably with commercial expectations. This creates a fundamental mismatch in how risk is perceived. A UAE fund manager evaluating a highway concession needs predictable cash flows over seven to ten years. A Pakistani state-backed investor is comfortable with twenty-year horizons because their cost of capital is subsidized by government guarantees that don't appear on any balance sheet. Both approaches work in isolation. They don't compound well together. Another counter-intuitive point that catches people off guard: the "clash" narrative oversimplifies things. In my experience, these negotiations aren't zero-sum in the way headlines suggest. Both sides usually get something they wanted, just not in the form they originally envisioned. The UAE entity gets market access and geopolitical leverage. The Pakistani side gets completed infrastructure and job creation metrics that translate into domestic political capital. The question is always who writes the press release.
Get the Full Details

Practical Navigation Strategies
If you are working on or advising a project involving these dynamics, here is what actually moves the needle. First, understand that compliance frameworks serve as negotiating currency. UAE institutions can sometimes relax documentation requirements if the counterparty provides equivalent guarantees through alternative channels. Pakistani stakeholders appreciate this flexibility because it preserves their operating model while giving the appearance of international standards adoption. Second, structure payment terms around deliverables that both sides can claim credit for. Milestone-based disbursements work better than time-based ones because they force concrete progress visibility. I've seen projects where the payment schedule was the only thing keeping negotiations alive during periods when technical teams couldn't agree on design specifications. The downside of this approach is that it requires significant upfront legal and financial structuring costs. A properly documented hybrid framework can add three to six months and $200,000 to $500,000 in professional fees before ground is broken. For smaller projects under $100 million, this overhead often makes the arrangement uneconomical. In those cases, simpler bilateral agreements with clearer dispute resolution mechanisms tend to outperform complex multi-party structures.
Third, build in exit ramps from day one. Every infrastructure deal in this region eventually faces some form of political or economic disruption. Currency devaluation, leadership changes, budget reallocations - these aren't edge cases, they are the baseline. Contracts that assume stable conditions are contracts that will be renegotiated under duress, which is a terrible position to be in. The most effective exit provisions I've encountered use tiered mechanisms. Minor disruptions trigger automatic extension clauses. Major political changes allow for renegotiation without penalty. Catastrophic events (and I've seen this term actually used in contract language) permit orderly wind-down with pre-agreed asset valuation formulas. This last point is crucial because it removes the emotional component from what would otherwise be an adversarial process.
When These Structures Fail
Not every attempt at compromise works. The failure mode I see most often involves third-party dependencies that neither side fully controls. A recent example involved a renewable energy project where the technology provider was European, the financing was mixed UAE-Pakistani, and the offtake agreement was with a state utility that had its own budget constraints independent of the project sponsors. When the utility delayed payments, the entire structure unraveled because no single party had enough leverage to absorb the shock alone. Another common pitfall is over-reliance on personal relationships between senior officials. I've watched deals collapse within months of a key ministerial change because the entire framework was built on informal understandings rather than documented agreements. The relationship-based approach can accelerate early-stage negotiations significantly, but it creates fragility that compounds over time. For projects where the stakeholder alignment is fundamentally misaligned - when one side views the investment as strategic and the other views it as purely financial - no amount of clever structuring will resolve the underlying tension. In those cases, the best outcome is often a phased approach where each party funds and controls separate components, with contractual handoffs at clearly defined boundaries. It's less elegant, but it prevents total failure when cooperation breaks down.
The infrastructure landscape in this region continues to evolve, and the patterns I've observed over the past decade suggest that hybrid financing structures will remain common even as individual projects come and go. The clash between different financial philosophies isn't going away. It's just getting more sophisticated.