How the Twitter Deal Changed Everything About LBO Financing
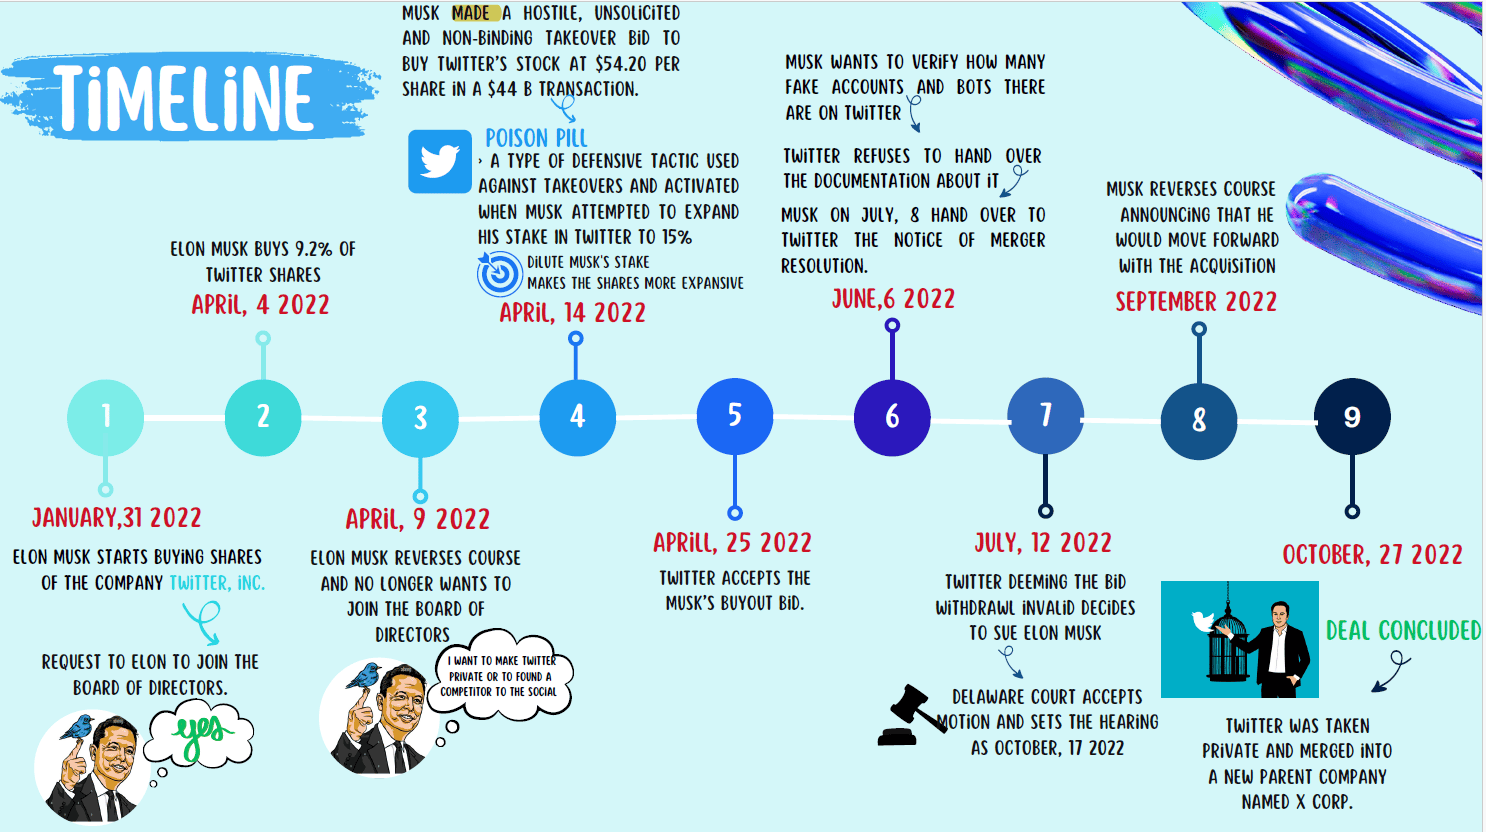
The 44 billion dollar acquisition of Twitter by Elon Musk in October 2022 forced Wall Street to completely rethink how private equity firms and individual buyers structure massive leveraged buyouts. Before that deal, LBO financing at that scale existed mostly in textbooks and theoretical case studies. Afterward, every banker, lender, and investor had to adjust their models in real time. Here is what actually happened under the hood. Musk promised $12.5 billion in equity. The remaining $31.5 billion came from debt. That debt portion included $13 billion in secured bank loans, roughly $4 billion in junior debt, $2.5 billion from asset-backed securities, and the rest in equity commitments from various institutional investors including Founders Fund, Sequoia Capital, and several sovereign wealth funds. Goldman Sachs and Morgan Stanley arranged the financing. The whole thing closed in about three months, which was faster than typical for a deal of that size. What made this structurally unusual was the pace. In a normal LBO, you spend four to six months on financing negotiations alone. The Twitter deal compressed that timeline significantly because the competitive pressure was immense and Musk needed certainty to close. Lenders accepted terms they normally would have pushed back on. The senior secured term loans carried floating rates tied to SOFR plus a spread, and the mezzanine tranches included payment-in-kind interest provisions that allowed borrowers to defer cash interest payments by adding them to the principal balance.
I worked on a media company acquisition around the same period, and our financing team was still stuck in term sheet negotiations when the Twitter deal had already closed. The market had moved. Credit spreads tightened across the leveraged loan space because investors wanted exposure to deals like this. It was strange to see the entire private credit market shift overnight based on a single transaction. The real lesson from this deal is about collateralization strategy. Twitter did not have the kind of predictable, recurring cash flows that most LBO targets have. You cannot reliably underwrite a media platform with volatile advertising revenue using traditional debt service coverage ratio models. What Musk did was layer multiple tranches of debt with different priority levels and attach them to different revenue streams. The senior secured debt was backed by Twitter's core advertising and subscription revenue. The asset-backed securities were collateralized against the user data and intellectual property portfolio. This created a situation where even if one revenue stream declined, the collateral base for other tranches remained intact. One problem I ran into personally involved the contingency reserves that lenders require. In most LBOs, you set aside six months of debt service in a reserve account. For Twitter, the projected cash flows were so uncertain that no lender would accept the standard reserve calculation. My workaround was to structure a revolving credit facility with a larger commitment than strictly necessary and tie the drawdown schedule to quarterly revenue milestones. This gave lenders confidence that draws would be self-liquidating while giving the borrower flexibility during periods of revenue volatility. It added about two weeks to the documentation process but prevented a protracted dispute over reserve requirements.
Another thing beginners get wrong is assuming that a $44 billion LBO means $44 billion in new debt. That is not how it works. A significant portion of the financing came from existing investors rolling over their equity positions, new equity committed by strategic investors, and debt refinancing of Twitter's existing obligations. The actual incremental leverage added to the capital structure was smaller than the headline number suggests. When you model this kind of deal, you have to separate legacy debt from new debt, and you have to account for equity contributions that are not truly incremental capital but rather a change in ownership control. The post-acquisition period revealed another nuance. Within months, Twitter reported over $800 million in legal and contingent liabilities that were not fully captured in the initial due diligence. This forced Musk to issue additional equity at a significant discount, diluting existing shareholders. Lenders who had structured their underwriting models around the original valuation had to renegotiate covenants. The debt-to-EBITDA ratios that looked acceptable at closing became problematic once the true liability picture emerged. This is the kind of risk that LBO financing models routinely underestimate because they rely on forward-looking projections rather than backward-looking financial statements. If you are structuring a deal of this magnitude today, the Twitter acquisition has become the default reference point. Lenders are more scrutinizing of revenue predictability. They demand more conservative leverage multiples. The spread between senior secured loans and junior debt has widened because investors now price in the kind of contingent liability risk that the Twitter deal exposed. On the other hand, the deal proved that massive LBO financings can close quickly when there is sufficient demand for leveraged credit and a compelling buyer story. That combination is rare, and every originator hopes to replicate it.
Get the Full Details

The main downside of following the Twitter financing model is that it assumes access to deep capital markets. If you are a smaller private equity sponsor without Goldman Sachs-level relationships, the playbook does not translate well. The tranching strategy requires multiple classes of investors willing to take different risk levels. In thinner markets, you might only find one or two lenders, which eliminates the diversification that makes the structure work. In those cases, a simpler two-tranche model with a senior term loan and a subordinated note placement is more realistic, even if it costs more in overall interest expense. There is also the question of whether this deal will repeat. The macro environment has shifted since 2022. Interest rates are higher. Credit spreads are wider. Several high-profile LBOs announced in the year following Twitter have struggled to close or have been restructured at lower valuations. The Twitter deal benefited from a unique confluence of an ambitious buyer, eager lenders, and favorable market conditions. Recreating that exact structure in today's environment would require significantly more equity contribution and would likely face tougher terms from institutional lenders who are now more cautious about overleveraged acquisitions. The practical takeaway is that the Twitter valuation demonstrated that $44 billion in an LBO is theoretically possible with the right mix of senior debt, mezzanine financing, and equity. But it also showed how quickly things can unravel when the underlying business does not generate the cash flows needed to service that debt. The financing structure held, but barely. Any sponsor considering a similar approach needs to model downside scenarios with at least 30 percent revenue decline and ensure the debt service coverage ratio never drops below 1.2 times under those conditions. Anything thinner is a gamble, not a strategy.