Understanding a 3x Inverse Dow ETF
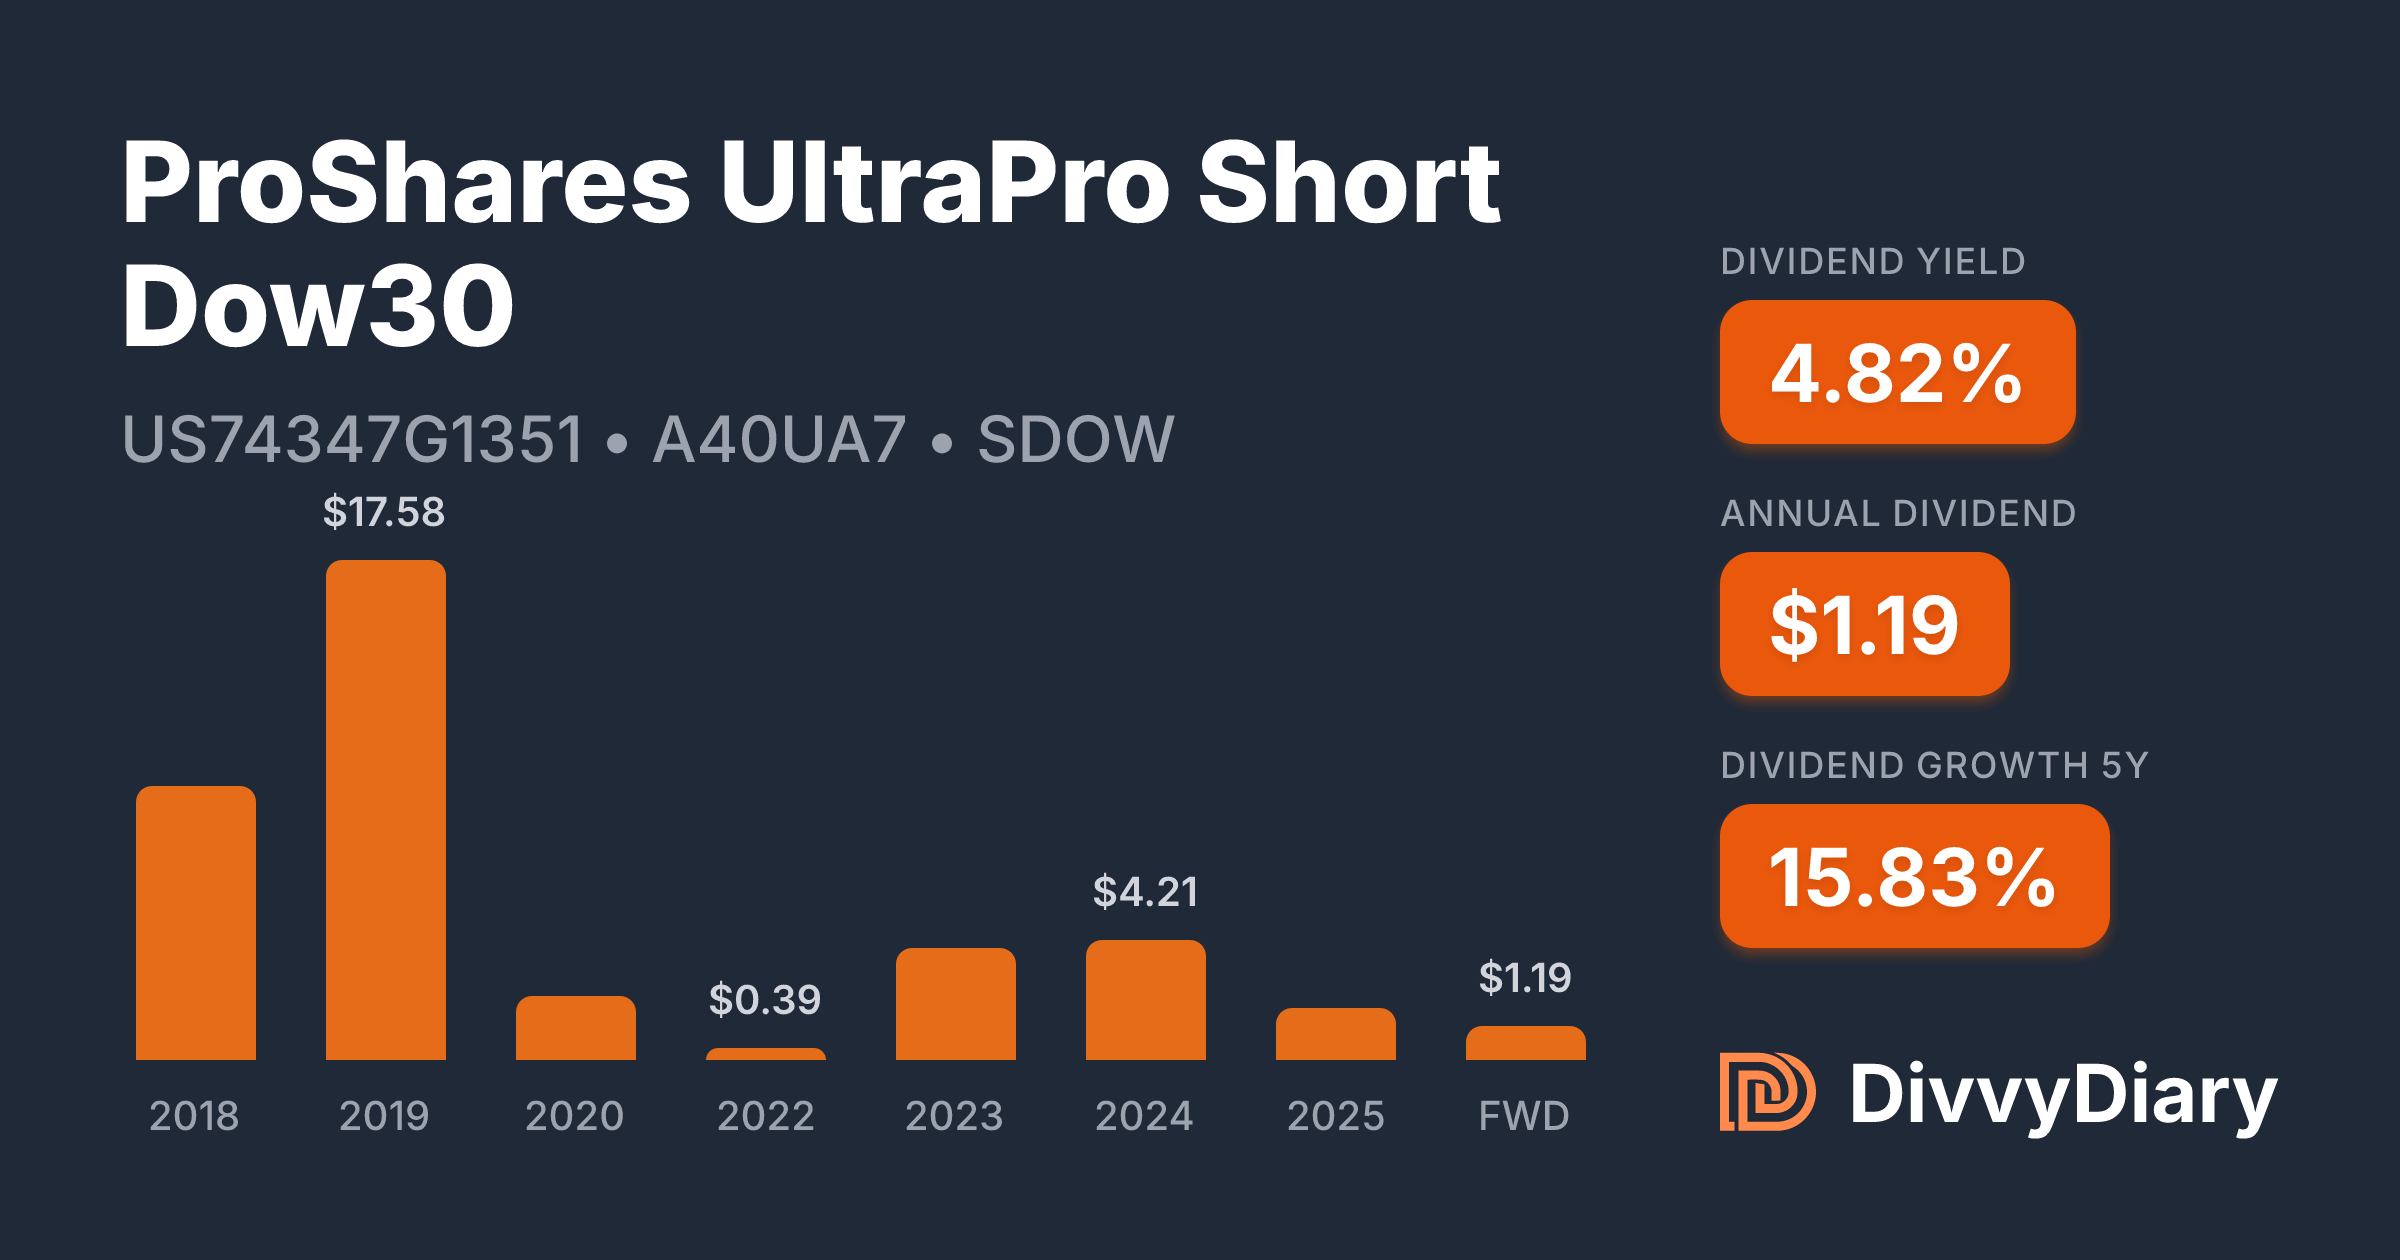
The ProShares UltraPro Short Dow30 (ticker: SDOW) tracks the daily inverse performance of the Dow Jones Industrial Average by a factor of three. If the Dow drops 1% in a day, SDOW is supposed to gain roughly 3%. The opposite is equally true. This is straightforward in theory. It becomes complicated fast once you hold it past a single day. The appeal is obvious to someone watching the market go down. You put up money, the index drops, and your position triples the gain on paper. During the early part of 2022 when rates were climbing and equities sold off hard, SDOW was one of the easiest hedges people could buy without touching options. It sat in regular brokerage accounts. You clicked buy. No margin call waiting to happen. The mechanics behind that are what actually matter. ProShares uses total return swaps and futures contracts to generate the exposure. The fund rebalances its derivative positions every single trading day to reset the leverage ratio back to three times the index move. That daily reset is the entire reason this thing works for a day trade and destroys you if you treat it like a long-term bet.
I spent about six months trading SDOW through the volatility of late 2022 into early 2023. What I learned was mostly about what goes wrong rather than what goes right. Here is the practical breakdown.
How It Actually Works in Practice
The fund publishes a prospectus, which most people never read. The key detail is in the compounding section. The returns are not simply three times the cumulative return of the index over any period longer than one day. Volatility decay does the rest. Let me give you a concrete example. Say the Dow drops 5% on Monday, rises 5% on Tuesday, and ends flat on Wednesday. The Dow is basically back where it started after three days. Now look at SDOW. Monday it's up 15%. Tuesday the Dow is up 5%, so SDOW drops 15%. Three times 5% is 15%, so that tracks. But you're compounding from a smaller base. After Tuesday, SDOW is down roughly 3.75% from its starting point. After Wednesday it is further underwater. The index barely moved. The fund lost meaningful money. This is called volatility drag and it eats compounding returns alive over time.
Get the Full Details
What Most People Miss
The expense ratio on SDOW is roughly 0.95%, which sounds normal for a regular index fund but is brutal for an inverse leveraged product. You are paying nearly 1% a year just for the privilege of holding the ticker. On top of that, the daily rebalancing creates implicit transaction costs. ProShares absorbs most of the swap costs, but the fund still trades futures and rolls positions, and that bleeding shows up in the net asset value over time. Another thing nobody warns about is the liquidity picture. SDOW has solid average daily volume, usually between 2 and 5 million shares. The bid-ask spread can widen to 3 to 5 cents in normal markets, which is manageable. But during sharp selloffs when everyone wants in at once, spreads can go wider and slippage becomes real. I learned this the hard way on March 10th, 2023, when bank stock fear sent the Dow down hard. I tried to enter a position and got filled well above the quoted midprice because the order book was thin at that moment. The execution cost added up fast.
When It Works and When It Fails
SDOW performs exactly as advertised in strong downtrends with low day-to-day whipsaw. The problem is whipsaw. Markets chop most of the time. A sideways or oscillating market is where this fund bleeds. The constant daily rebalancing forces the fund to buy high and sell low relative to the index. Each cycle extracts value. I ran into a specific edge case that took me a while to fix. I was using SDOW as a short-term hedge during a Fed meeting window in mid-2023. The day before the announcement, the Dow was slightly up. I had already been holding SDOW for three days and it had quietly lost about 4% to volatility decay. The Fed held rates steady, the Dow opened higher, and SDOW dropped another 2% intraday. My intended 3x hedge was underwater by roughly 6% before the market even moved in my favor. The decay had already eaten the edge I was counting on. The workaround was simple but easy to overlook. I started measuring the VIX and the Dow's average true range before entering. If the market was in a low-volatility grind, I would not hold the position overnight regardless of direction. I also switched to using SDOW calls instead of the ETF itself when I wanted directional exposure around event windows. Options let me capture the move without the daily decay building against me while I waited. For actual portfolio hedging, I moved to individual put options on DIA rather than holding a leveraged ETF through multiple days.
Who Should Use This
This product is for traders who understand leveraged ETF mechanics and use it strictly as a tactical tool. Day traders and swing traders who enter and exit within a few days at most can make it work. Long-term investors should stay far away from it. There is no scenario where holding a 3x inverse ETF for months makes mathematical sense unless you are extremely lucky with timing and the market trends hard in one direction. If you want the same short exposure without the daily compounding distortion, you could consider SPDR Dow Jones Industrial Average Put and Call ETF (DXF) or simply trade put options on the Dow via futures or the ETF. Those instruments do not reset daily. They track the underlying more linearly. The execution is more complex, but the economics are cleaner.

The Bottom Line
SDOW does what it claims. The claim is the problem. It claims to deliver three times the daily inverse return of the Dow. That means exactly one day. Anything beyond that and the math stops being friendly. The fund is a blunt instrument. It is useful in crisis conditions when you need immediate downside exposure and cannot be bothered setting up options chains. It is a terrible investment vehicle for anyone treating leverage as a long-term strategy. The fees, the decay, and the daily rebalancing are all structural headwinds that compound against the holder over time. Use it sparingly, measure it against volatility, and get out before the whipsaw takes another bite.


