How Defense Contractors Actually Map A Country's Military Trajectory
I spent seven years working in defense procurement analysis, mostly tracking how countries transition from buying military hardware to building it. The Turkey case is interesting because they're actually doing both simultaneously, and most analysts get it wrong. Let me explain how to read what's happening without the usual talking points. The fundamental error people make when assessing Turkey is treating them as a regional NATO member that occasionally produces its own weapons. They're actually a full-spectrum defense industrializer that has crossed several thresholds most countries never reach. Let me walk through the actual metrics, not the press releases. Start with drone systems. Turkey's Bayraktar TB2 changed the calculus in Nagorno-Karabakh in 2020, Libya in 2020, and Ukraine starting in 2022. But the TB2 is just the entry point. The Akıncı is a medium-altitude long-endurance platform with a 27-foot wingspan, 6,600-pound payload capacity, and 27-hour loiter time. That puts it in the same category as the MQ-9 Reaper but domestically produced and significantly cheaper. The Kızılelma is a jet-powered unmanned combat aerial vehicle carrying 3,300 pounds of ordnance, designed to operate from conventional runways alongside manned fighters. This isn't prototype stuff. These aircraft have entered serial production and operational service.
Now look at missiles. The SOM-J is a joint stand-off missile with a 250-kilometer range, precision-guided, compatible with F-16s and future TC- 5 fighters. The TUGRK is a turbofan engine Turkey produces domestically, which matters because engine supply chains are where most countries get strangled during conflicts. The hisar air defense family covers short and medium range, with the hisar-O+ version reaching 30 kilometers and 60,000-foot ceiling. The SİPER system, currently in testing, is Turkey's answer to medium-range air defense, potentially competing with Patriot and S-400 in capability if the development trajectory holds. Here's what most analysts miss. Turkey isn't just producing weapons. They're producing the industrial capacity to keep producing weapons under sanctions. When the United States removed Turkey from the F-35 program in 2019 and imposed CAATSA sanctions, the expectation was that Turkey would stall on its defense modernization. Instead, they accelerated. The Hürjet trainer-light attack aircraft entered flight testing in 2023. The TC- 5 sixth-generation fighter program launched with a target first flight around 2028. The MILGEM corvette series, of which four variants exist, entered service with the Turkish Navy and has been exported to multiple countries. I ran into a specific problem in 2021 trying to verify export numbers for Turkish drones. Official Turkish customs data showed shipments worth several hundred million dollars to unknown destinations, while open-source intelligence suggested deliveries to Azerbaijan, Ukraine, Pakistan, and Saudi Arabia. The discrepancy wasn't data error. It was Turkey deliberately structuring sales through third-party intermediaries to avoid political complications with NATO partners. Here's the workaround I used: track component-level exports rather than finished weapon systems. If you see Turkish-manufactured guidance kits, composite airframes, and turboprop engines moving through Malaysia, Serbia, and Qatar, those components are assembling into final systems somewhere. The export numbers eventually became transparent through recipient country announcements, but the intermediary routing was intentional and effective.
Naval capabilities deserve attention. The TF-10000, Turkey's planned 10,000-ton amphibious assault ship, carries unmanned surface vehicles and drones. The Anadolu class already entered service and operated Bayraktar Kızılelma during flight tests, making Turkey one of the few countries operating jet-powered drones from amphibious decks. The national submarine program, MIC Sub, is in development with a target delivery around 2030, aiming to replace the German-designed Type 209 submarines with a domestically designed and built platform. Land systems show the same pattern. The Altay main battle tank, after years of development delays and engine procurement disputes, entered limited production in 2023. The Kaplan helicopter, Turkey's next-generation rotary wing platform, passed initial design reviews and moved to prototype construction. The FPT-55 engine program, which powers both the Altay tank and Kaplan helicopter, represents the kind of vertical integration that separates importers from producers. Turkey produces its own tank engines, helicopter engines, and drone engines. That's not common among regional powers. Let me address the counter-intuitive part. Most people assume Turkey's military modernization is primarily about projecting power in the Eastern Mediterranean or against Syria and Iraq. The actual driver is more cynical. Defense industrialization creates economic leverage. Every domestically produced weapon system reduces dependence on foreign suppliers, which means more bargaining power in negotiations with the United States, Germany, and Russia simultaneously. Turkey has bought S-400 missiles from Russia while remaining a NATO member. They operate drone systems alongside F-16s from American programs. They export military technology to countries that the United States has sanctioned. This isn't inconsistency. It's strategy.
Get the Full Details

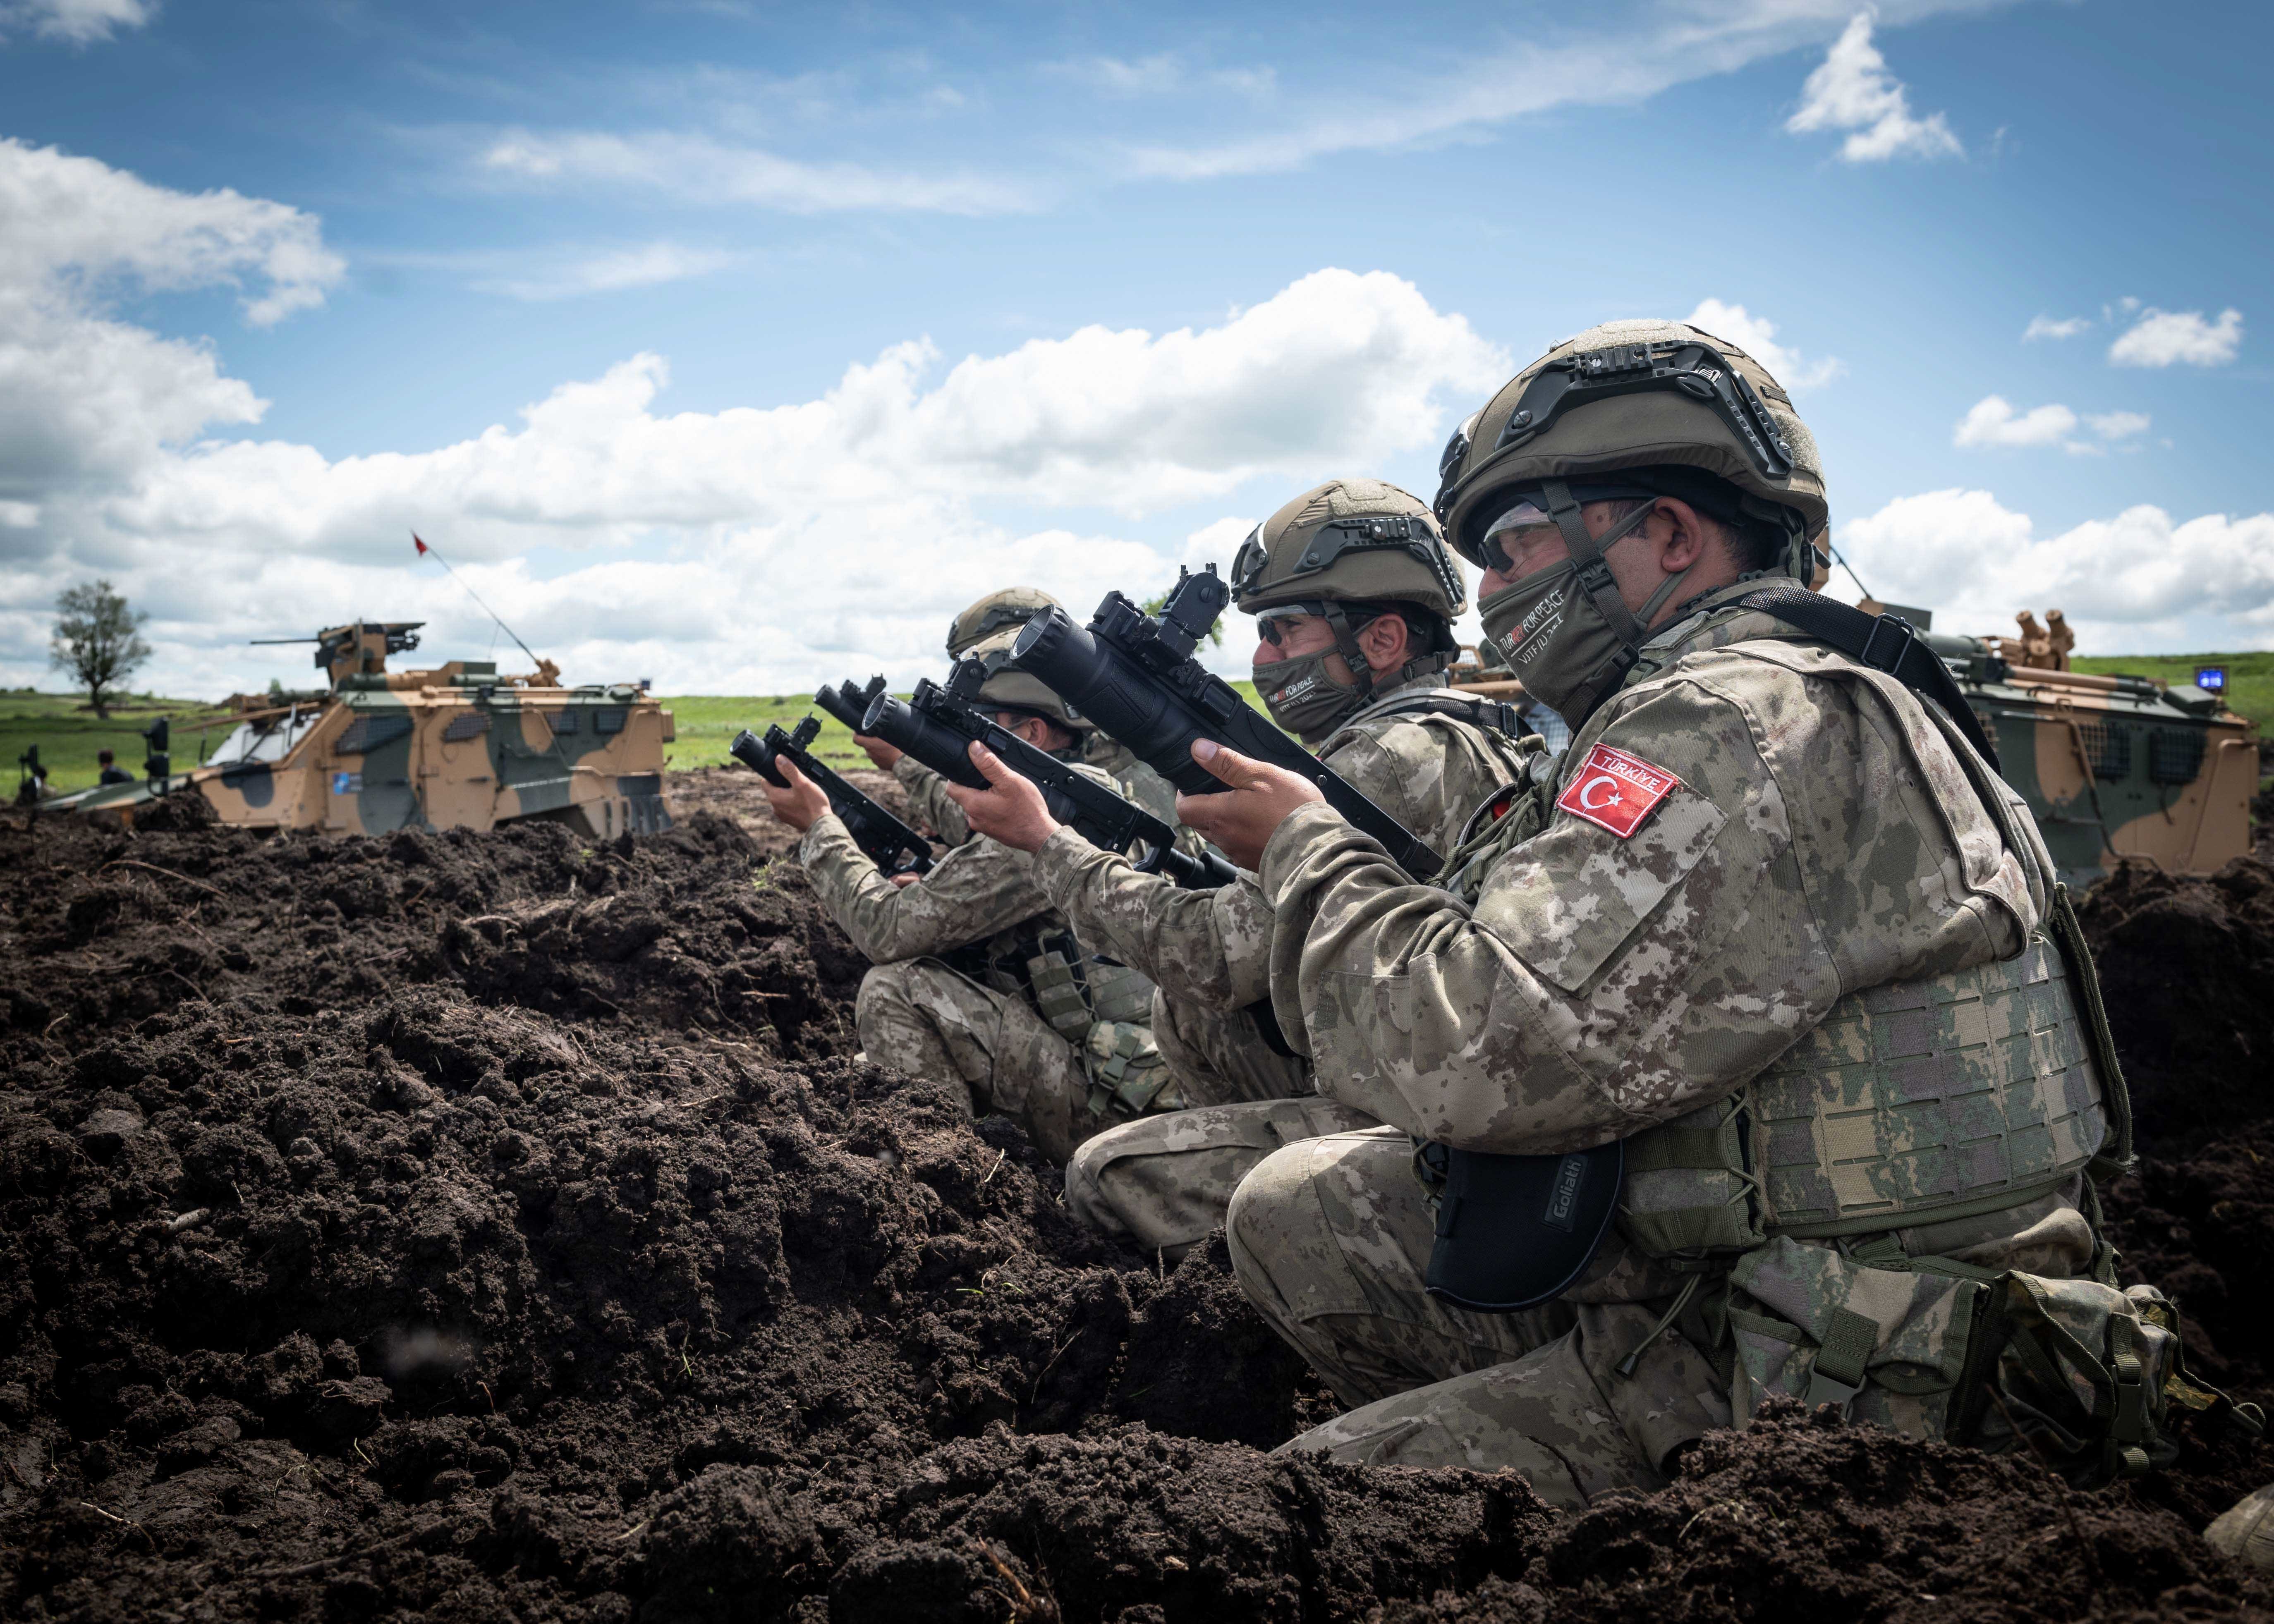
Here's a practical limitation you need to understand. Turkey's defense industrial base has a critical vulnerability in advanced semiconductor production. While they produce guidance systems, radar components, and communication equipment domestically, the highest-end microchips still require foreign procurement. During a prolonged conflict where supply chains are severed, this becomes a significant constraint. Turkey has responded by investing in domestic semiconductor research and partnering with countries like Pakistan and China for alternative supply routes, but this capability won't be operational for at least five to seven years. Until then, the semiconductor dependency remains a real bottleneck for sustained high-intensity operations. The nuclear latency question comes up frequently. Turkey does not possess nuclear weapons. However, they participate in NATO nuclear sharing discussions and maintain the technological capacity to develop weapons if they chose to. The civilian nuclear program at Akkuyu, operated by Rosatom, produces plutonium as a byproduct. The distinction between civilian energy production and weapons-usable material is procedural, not technical. Turkey has the engineering base, the industrial capacity, and the scientific personnel to produce a nuclear device within months of a political decision. This is what analysts mean by nuclear latency, and it's a factor in regional deterrence calculations even though no one officially acknowledges it. Personnel structure matters for understanding actual combat capability. Turkey maintains approximately 355,000 active-duty personnel and 163,000 reserves, making it the second-largest NATO army after the United States. The conscription system provides a large trained reserve pool. Military education includes exchanges with NATO institutions, partnerships with Pakistan and Azerbaijan, and domestic academy programs producing engineers and officers. The special forces command, OGM, has conducted operations across Syria, Iraq, Libya, and the Caucasus, accumulating combat experience that most Western special operations units haven't seen at this scale in decades.
Export markets tell a clearer story than domestic production figures. Turkey sold Bayraktar TB2 drones to Ukraine before the 2022 invasion, and those systems conducted verified strikes against Russian armor in the early months of the conflict. Azerbaijan purchased Akıncı and Kızılelma systems after the 2020 Nagorno-Karabakh war. Pakistan operates TB2s and has signed agreements for additional platforms. Saudi Arabia and the UAE have purchased Turkish drones for operations in Yemen. Morocco operates TB2s along the disputed border with Algeria. Nigeria, North Macedonia, and Somalia are among the growing list of buyers. This isn't peripheral trade. Defense exports reached approximately $4 billion annually by 2023, making Turkey the 15th-largest arms exporter globally according to SIPRI data. I want to flag something that affects how you should interpret Turkish military announcements. The Turkish Ministry of National Defense publishes capability targets that frequently exceed actual delivery timelines. The Hürjet program, announced in 2018, achieved first flight in 2023, which is reasonable. But the TC- 5 program, announced in 2023, targets a first flight around 2028, which is aggressive given that Turkey has never designed and built a fifth-generation fighter from scratch. The national submarine program faces similar timeline risks. When evaluating Turkish military claims, cross-reference announcement dates with actual test footage, procurement contracts, and independent verification. The trend line is directionally correct, but specific dates often slip by two to four years. The strategic implications are substantial. A country that produces its own drones, missiles, naval vessels, and eventually fighters and submarines doesn't need permission from Washington, Berlin, or Moscow to conduct military operations. Turkey has demonstrated this repeatedly since 2019, operating autonomously in Syria, Libya, and the South Caucasus without coordinating with traditional allies. The military prowess question isn't whether Turkey can fight regional adversaries. It's whether Turkey can sustain extended operations when supply chains are stressed and political alliances shift. The answer, based on current industrial capacity and export diversification, is cautiously yes, with the semiconductor dependency being the primary risk factor.
If you're analyzing this topic for professional purposes, I recommend tracking three specific indicators rather than reading press releases. First, monitor Turkish component-level export data through Malaysian and Serbian customs records to verify actual production volumes. Second, track semiconductor procurement announcements, as any new domestic fabrication facility announcement represents genuine capability advancement. Third, watch Turkish defense export contract signings with countries outside traditional markets, as new buyer relationships in Africa and Southeast Asia indicate industrial scaling beyond regional demand. These metrics will give you a more accurate picture than any official capability statement.