
Understanding Trumbull County Sheriff Sales
Trumbull County Sheriff Sales A Lucrative And Painful Market For Homeowners In Distress represent one of those areas where the public-facing description bears almost no resemblance to what actually happens on the ground. A sheriff sale is a foreclosure auction conducted by the Trumbull County Sheriff's Office following a court-ordered judgment of foreclosure. The property goes to the highest bidder, and the winning bid typically extinguishes most junior liens, including second mortgages and home equity lines of credit that were not addressed during the foreclosure proceedings. The process starts when a lender files a foreclosure action in Trumbull County Court of Common Pleas. Once the court enters a judgment of foreclosure, the case gets docketed for a sheriff sale. That part alone can take anywhere from four to eighteen months depending on how backed up the court calendar is and whether the homeowner has filed any stay motions or bankruptcy petitions along the way. A Chapter 13 filing will pause the entire process. A Chapter 7 usually does not, unless there is equity to administer for the trustee.
Trumbull County Sheriff Sales A Lucrative And Painful Market For Homeowners In Distress
For investors, these sales offer properties that often sell below market value because most bidders lack the time, capital, or patience to deal with the complications that follow the auction. For homeowners who have lost their homes, it is painful in ways that are difficult to describe without sounding dramatic, so I will just say this: you lose whatever equity you had left, you get a cash sum that is usually far less than what you owed, and you still may owe a deficiency balance if the sale price did not cover the full amount of the debt. The deficiency judgment is where a lot of people get blindsided. I will walk through the sequence as it plays out in practice, because the official paperwork does not always reflect the reality of timelines and procedures. First, the plaintiff's attorney files the foreclosure complaint. The homeowner gets served, and they have twenty-eight days to answer or file a motion to dismiss. Most homeowners in Trumbull County do not have counsel at this stage. They receive a summons and complaint by mail and then they either respond poorly or not at all, which is when the court enters a default judgment. After the default judgment, the case moves to the marshal's phase. The sheriff's office publishes a notice of sale in a local newspaper once a week for three consecutive weeks. The sale date is set at least thirty days after the first publication. On sale day, the auction happens at the Trumbull County Courthouse in Youngstown. Bidders usually need to register beforehand and post a deposit of ten percent of their opening bid in cash or cashier's check. The actual bidding starts at the amount of the judgment debt plus costs and works upward from there.
If the property receives no acceptable bid, it reverts to the foreclosing lender as real estate owned. That is not uncommon. Lenders sometimes let the property pass in at the auction and then try to sell it through a real estate agent later, which is how you end up seeing a bank-owned house listed at a price that seems oddly high for a distressed property. That pricing gap exists because the lender is trying to recover the full debt balance, not because the market supports that valuation.
Get the Full Details

What Homeowners Need To Know Before The Auction Date
There are a few things that matter more than most people realize. The right of redemption in Ohio is extremely limited for judicial foreclosures like the ones handled through Trumbull County. Unlike some states where you can redeem a property for a year or more after the sale, Ohio basically does not offer a post-sale redemption period for most residential foreclosures. The window to stop the sale is during the litigation itself, through a voluntary mortgage modification, a short sale, a deed in lieu of foreclosure, or a bankruptcy filing. Once the sheriff's sale happens, those options are largely closed. Homeowners should also understand that the sale does not automatically wipe out all obligations. A federal tax lien survives the foreclosure sale regardless of when it was recorded. State tax liens behave the same way. The homeowner remains personally liable for any deficiency unless the court explicitly waives it, which is rare in Trumbull County unless the lender agrees to a stipulation. I once worked with a homeowner whose property sold for $42,000 at the sheriff sale. Her original mortgage balance was approximately $168,000. She assumed the sale would end her obligation. It did not. The lender pursued a deficiency judgment and eventually obtained one for roughly $140,000 after accounting for accrued interest and costs. She ended up in wage garnishment for two years before reaching a settlement. That is a normal outcome, not an edge case, and most people do not know it until it is too late.
Common Mistakes That Make Things Worse
The most frequent mistake I see is homeowners waiting until the last possible moment to act. They hear about the sale date and then scramble to find legal help or explore options that simply are not available at that point. Filing a motion to vacate the judgment of foreclosure based on improper service is theoretically possible, but the standard for setting aside a default judgment in Ohio is strict. You need to show a meritorious defense and that the failure to appear was not your fault. Courts do not grant these motions lightly, especially when the foreclosure complaint was properly served and the homeowner had actual notice of the proceedings. Another mistake is assuming that showing up at the auction will somehow protect the home. It will not. The homeowner has no voting rights at the sale and no special standing to block the auction on the day it happens unless there is already a stay order from the court. If you are desperate to stop a sale, the only reliable route is a temporary restraining order or injunction, and those require actual grounds such as procedural defects or a pending loan modification that the lender is refusing to honor in good faith.
A Specific Problem I Encountered and How I Handled It
I dealt with a case where a property in Niles was scheduled for sheriff sale, and the homeowner claimed she had submitted a loss mitigation application to the servicer six months earlier. The servicer's documentation showed the application was received but never assigned to a loss mitigation processor. The sale was eleven days away. Filing for bankruptcy would have provided an automatic stay, but the homeowner had no income to support a Chapter 13 plan and Chapter 7 would not have saved the house because there was no equity and the lender had already obtained a summary judgment. The workaround was to file a motion to continue the sheriff sale on the grounds that the servicer was in violation of federal regulation requiring proper processing of a completed loss mitigation application before proceeding to foreclosure. The motion did not guarantee a postponement, but it gave the homeowner's attorney leverage to negotiate a seventy-two-hour continuance, which was enough time for the servicer to assign the file and begin preliminary review. The sale was pushed back sixty days. The homeowner ultimately did not qualify for a modification, but the additional time allowed her to complete a short sale instead of walking away from a deficiency judgment. The short sale reduced her remaining obligation by approximately eighty-five percent compared to what a deficiency judgment would have looked like.
The Deficiency Judgment Issue Worth Understanding
Ohio is a recourse state, which means lenders can pursue deficiency judgments after a sheriff sale. The calculation is straightforward in theory: take the total debt including interest, fees, and costs, subtract the sheriff sale price, and the difference is the deficiency. In practice, lenders sometimes miscalculate or overstate the amount, which is why homeowners should never ignore a deficiency judgment without reviewing the supporting affidavit. I have seen affidavits that included late fees that were never properly assessed and legal costs that appeared to be duplicated across multiple line items. Settlement is almost always possible if the homeowner engages before the lender files a separate collection lawsuit. Lenders generally prefer to recover a portion of the deficiency rather than spend additional legal fees pursuing collection through garnishment or levy. A negotiated settlement for twenty to thirty-five percent of the reported deficiency is typical in Trumbull County, though the exact number depends on the lender's internal recovery policies and whether the homeowner has any assets worth pursuing.
Red Flags That Indicate Something Is Wrong With The Sale Process
If the notice of sale was published fewer than three times, the sale date falls within thirty days of the first publication, or the property description in the notice does not match the legal description on the deed, these are procedural defects that can be challenged. Ohio law requires strict compliance with the publication and notice requirements under Revised Code Section 2329.20. Deviations are common enough that I encounter them regularly, but most homeowners and even some attorneys do not catch them because they focus on the substance of the debt rather than the procedural details. Another red flag is when the scheduled sale price appears to be set far below the outstanding balance without any explanation. Sometimes this happens because the court has already determined the property's fair market value and the sale is being confirmed at a percentage of that value rather than at an open auction. That is less common in Trumbull County but it does occur, and it changes the dynamics significantly for both the homeowner and any potential bidders.
What Happens After The Property Sells
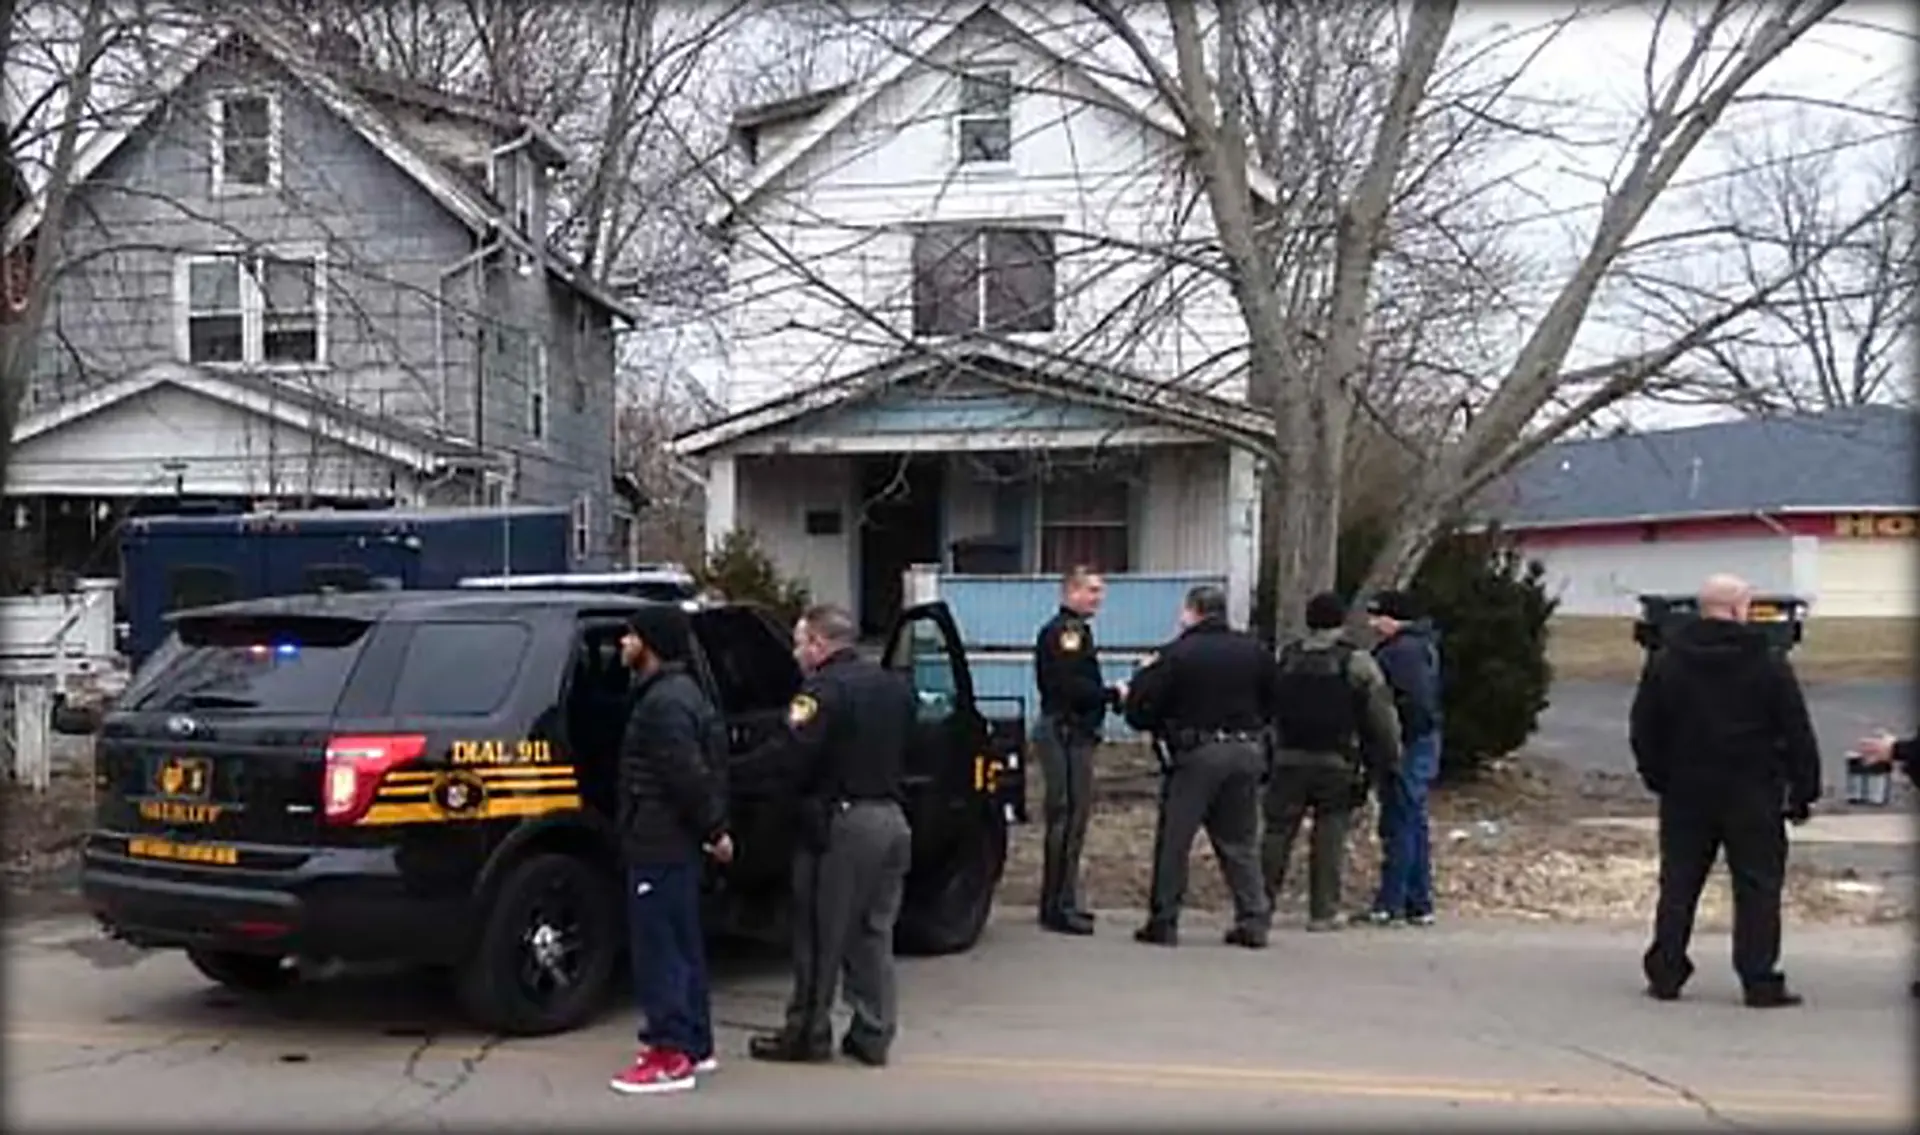
Once the highest bid is accepted, the sheriff prepares a deed and delivers it to the purchaser after the sale is confirmed by the court. Confirmation typically happens within thirty days of the auction, though it can take longer if there are objections or if the court's docket is congested. The purchaser must pay the full balance of the winning bid, usually within ten business days, or they forfeit their deposit and the sheriff reoffers the property at a new auction. For the former homeowner, the eviction process begins after the new owner obtains the deed. The sheriff's office handles the eviction, which usually means a seventy-two-hour notice to vacate followed by a physical removal if the homeowner does not leave voluntarily. This part is unavoidable and happens whether the homeowner has a lease, a pending sale, or an active bankruptcy case that did not properly stay the eviction. I have seen tenants who purchased a foreclosure property at the sheriff sale but failed to record the deed before discovering an occupancy issue, which complicated the eviction timeline considerably.

Practical Steps If You Are Facing A Sheriff Sale
Get the exact sale date from the Trumbull County Sheriff's Office website or by calling their marshal division directly. Public notices are posted there, and the dates are accurate. Then review the complaint and judgment of foreclosure to check for service defects or calculation errors. File a motion to stay the sale if you have identified a viable legal basis. Explore loss mitigation with the servicer even if you think it is too late, because incomplete applications or processing delays can sometimes create a window for intervention. Consult an Ohio foreclosure attorney before taking any action, and do not rely on free legal hotlines or generic online advice for decisions that affect your financial liability. If you are considering purchasing at a Trumbull County sheriff sale, do your title search before bidding. Liens that survive the sale include federal tax liens, certain municipal liens, and judgment liens that were not properly extinguished by the foreclosure judgment. You will also need to account for occupant rights, which can delay possession by weeks or months if tenants or former owners refuse to leave and the new owner must go through a formal eviction proceeding. Factor in repair costs, property taxes that may have accumulated during the foreclosure period, and the possibility that the homeowner has stripped the property during the final stages of occupancy. I have seen houses where the copper piping, HVAC units, and built-in appliances were removed before the sale, leaving nothing of value behind.


