Navigating Modern Banking Without Losing Your Mind
I spent three years managing payment processing for a mid-market logistics company before moving into the banking advisory side. The last thing I needed was another platform promising to simplify the chaos. Most of them just add more tabs to click through. Truist's digital infrastructure, when it actually works the way it should, sits somewhere between legacy bank friction and genuinely useful automation. Here's what that looks like in practice. The guide itself is mostly a content hub rather than a tool. It covers account setup, mobile features, business banking workflows, and some deeper treasury management topics. The most useful section is the business banking piece, which walks through ACH origination, wire setup, and merchant services integration. If you're just opening a personal account, you can probably skip most of it. The guide assumes you're already slightly confused, which is fair because that's where most people start. One thing the guide doesn't address directly: the difference between Truist's consumer-facing interface and their commercial banking portal. They're separate logins, separate dashboards, and the user experience varies significantly between them. I learned this the hard way when I tried to set up a business ACH batch through the consumer app and spent twenty minutes looking for features that simply don't exist outside the commercial portal. The workaround is straightforward — just bookmark the commercial login at the outset. It saves you the initial confusion about which system you're actually using.
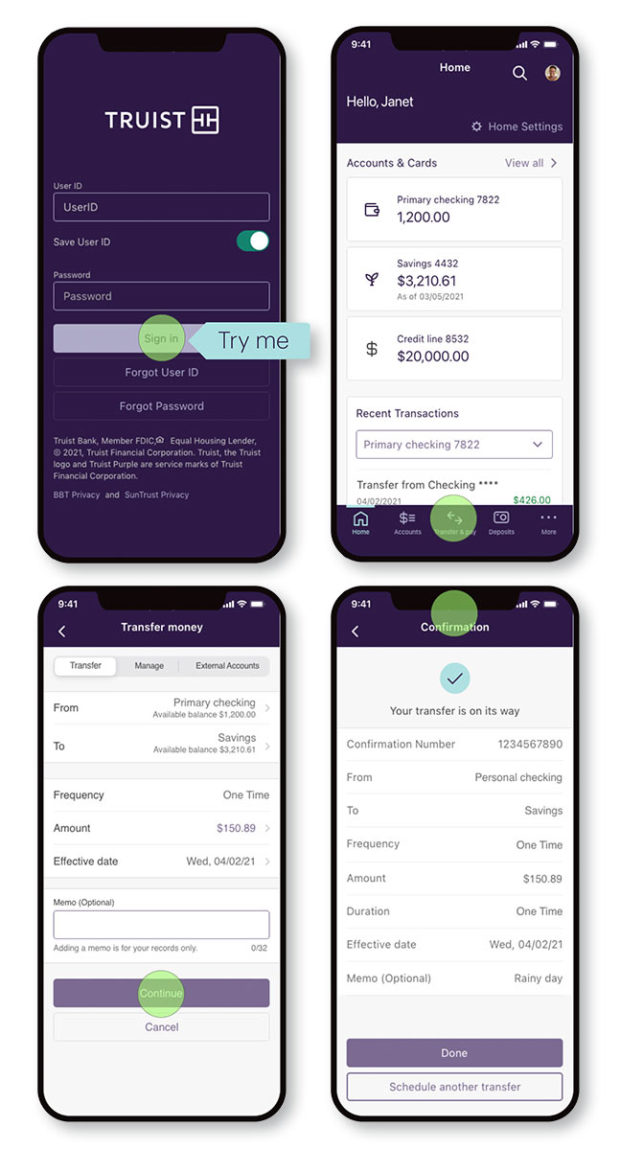
The mobile check deposit feature is adequate but has a strict limit that nobody talks about until you hit it. Standard accounts can deposit up to $25,000 per day and $75,000 per month through the app. If you're running a business that processes client payments through mobile deposits, this constraint will bite you within the first quarter. The fix is setting up a standing credit line or requesting a limit increase through your relationship manager, which usually takes two to three business days and requires some supporting documentation about your deposit patterns. Don't wait until you're stuck. Here's something counter-intuitive about Truist's online bill pay that most users miss. When you schedule a payment through the app, it goes through their internal mail-out system by default unless you explicitly choose the electronic delivery option. That means a payment you think is instant could take five to seven business days if you accidentally select the paper check route. The interface hides this choice fairly well — it's buried in the payment details screen rather than flagged upfront. I've watched people miss payment deadlines because of this, then call support and get told it was processed correctly, which technically it was, just not the way they expected. The Zelle integration is fine for personal transfers but limited for business use. Truist supports Zelle through both consumer and business accounts, but business-to-business Zelle transactions lack the audit trail and documentation that commercial banking workflows require. If you're moving anything over $5,000 regularly between business accounts, stick to ACH or wire. Zelle's dispute resolution process for business accounts is practically nonexistent compared to the formal channels available through the commercial platform.
The automatic fraud monitoring is reasonably aggressive. I had a client who ran a landscaping supply business and noticed that roughly one in every forty transactions got flagged for manual review. Most were false positives from routine vendor payments to out-of-state suppliers. The review process itself is fast — usually resolved within a few hours if you have the right documentation ready — but the hold on funds during that window can cause cash flow issues if you're relying on those payments to cover payroll. Having a backup line of credit that you can draw on during these holds is worth the minimal cost, especially if your transaction patterns are geographicall diverse. The treasury management tools in the commercial portal deserve more credit than they get. The cash concentration and sweep features are solid for multi-account businesses. You can set up automated overnight sweeps from operating accounts to investment accounts with specific thresholds, which means idle cash starts earning immediately without manual intervention. The downside is that the interface for configuring these rules is dated and the error messages when you misconfigure something are not helpful. I once spent forty-five minutes trying to figure out why a sweep wasn't triggering, only to discover that one of the source accounts had a negative balance due to a pendingACH debit that hadn't posted yet. The system won't let you save the configuration if any source account shows insufficient funds, but it also won't clearly tell you which account is the problem. Customer support through the app routes you to chat first, which is faster than phone support for simple questions. For anything involving account restrictions, fraud holds, or commercial lending inquiries, you need to call the dedicated line. The wait times vary wildly depending on the time of day — early morning and late afternoon on weekdays tend to be worse, while Tuesday and Wednesday mid-morning are generally manageable. Average hold time for a live representative is about twelve minutes during off-peak hours.
Get the Full Details

The mobile app itself gets regular updates and the recent redesign improved navigation noticeably. Account linking between personal and business accounts works but requires separate authorization for each connection. There's no bulk linking option, which is a minor inconvenience when you're setting up multiple accounts for different entities in your business structure. If you're evaluating whether to migrate to Truist from another institution, the account opening process through the guide's recommended path typically takes about twenty minutes for a standard checking account and forty-five minutes to an hour for a business account with documentation requirements. Fund transfers from external accounts usually post within one to two business days for standard ACH, though some accounts offer next-day availability depending on your history with the sending institution. There's no single feature here that makes Truist stand out dramatically from regional competitors, but the combination of functional mobile banking, reasonable commercial tools, and a support structure that responds within normal business hours makes it a viable option for individuals and small to mid-size businesses who want something more capable than a big national bank without the complexity of a full-service correspondent banking relationship. The guide is a useful reference but not comprehensive enough to replace actually learning the platform through use.